AI
Pakistan Warns UN Security Council of AI Risks to Global Peace and Equality

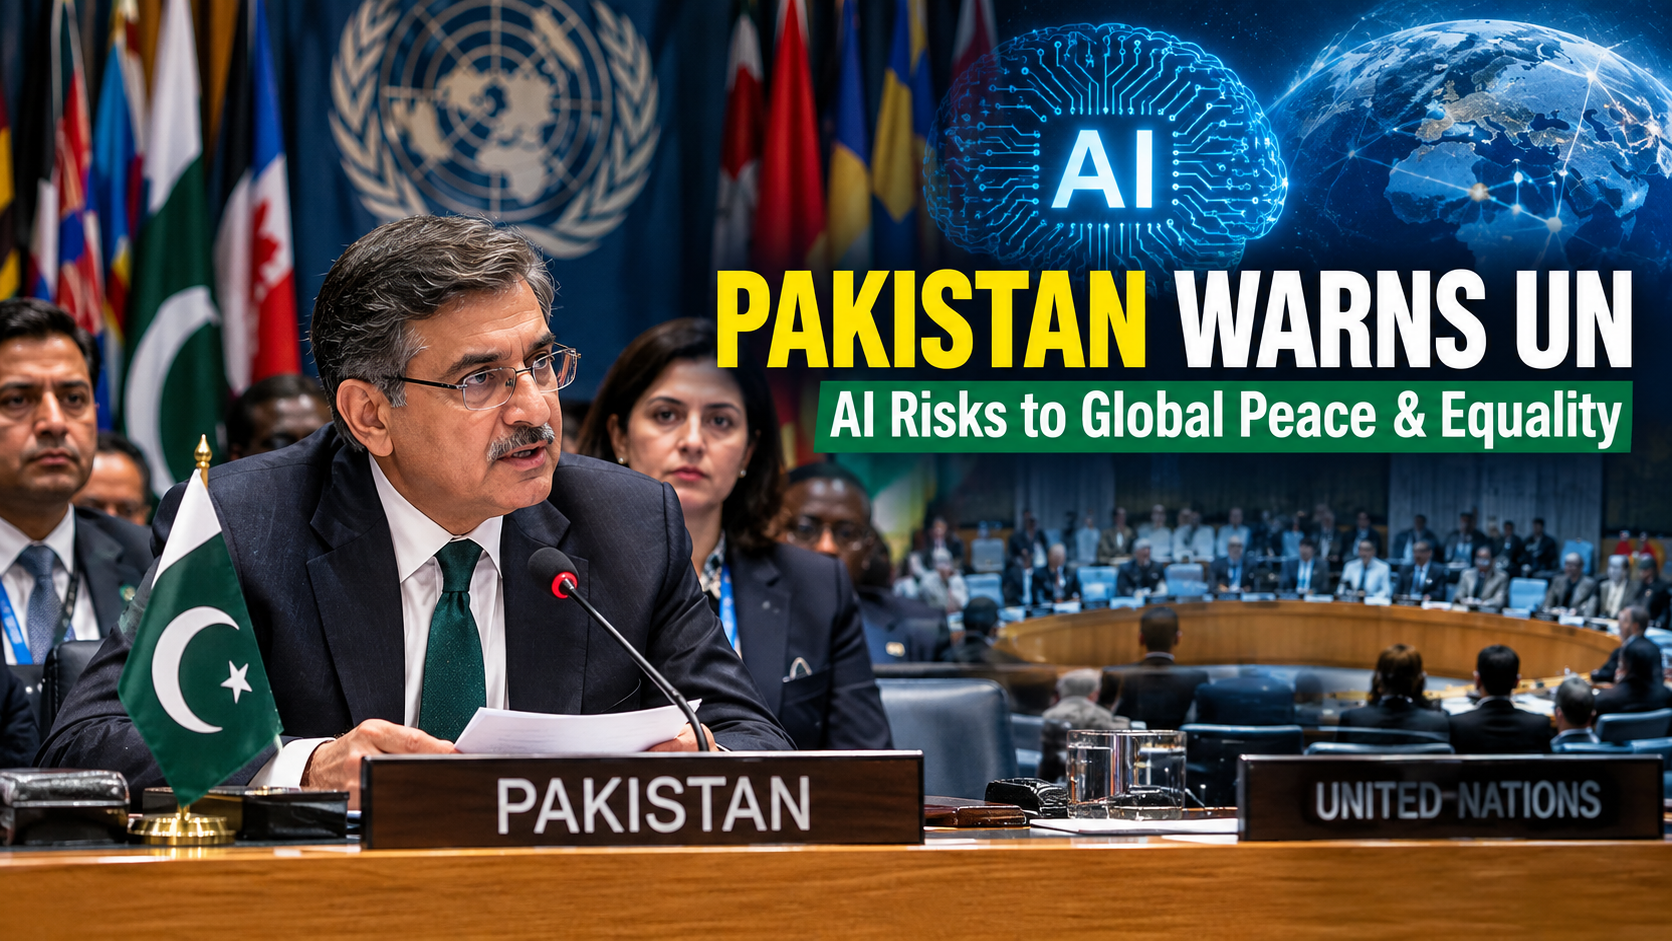
UNITED NATIONS — September 24, 2026: Pakistan has warned the United Nations Security Council that the rapid and insufficiently regulated development of artificial intelligence could deepen global inequality while creating new risks to international peace and security.
Speaking during a Security Council briefing on “Artificial Intelligence and International Security,” Pakistan’s Deputy Prime Minister and Foreign Minister Senator Mohammad Ishaq Dar called for stronger international safeguards, regulatory frameworks and governance mechanisms to address the risks associated with increasingly powerful AI systems.
Dar emphasized that the international community needs coordinated action to establish guardrails around artificial intelligence, particularly as AI technologies become increasingly relevant to military decision-making, information systems and national security.
Table of Contents
Pakistan Calls for International Guardrails on Artificial Intelligence
Pakistan’s intervention comes as governments and international institutions increasingly debate how AI should be governed across borders.
Dar stressed the importance of restraint and confidence-building measures in the military domain, particularly because AI-assisted systems could compress decision-making timelines and increase the danger of miscalculation.
The concern is significant because artificial intelligence is no longer confined to civilian applications. AI is increasingly being examined in relation to cyber operations, intelligence analysis, autonomous systems, information warfare and other security-sensitive areas.
The United Nations has also warned that AI can create substantial risks when technological development moves faster than international governance.
The UN’s existing AI framework emphasizes responsible, accountable, transparent and human-centered development, while calling for effective human oversight of AI systems.
Why AI Is Becoming a Security Council Issue
The Security Council has previously considered artificial intelligence as a potential factor affecting international peace and security, but the technology has developed rapidly since those early discussions.
A recent analysis by the independent Security Council Report identified several security implications, including AI’s ability to facilitate malicious cyber activity, accelerate the creation and distribution of misinformation and disinformation, and influence military operations.
The organization also highlighted concerns surrounding increasingly autonomous weapons systems, shortened decision-making timelines and questions about human oversight and accountability.
These concerns help explain why AI has moved beyond being primarily a technology-policy issue and increasingly become a subject of international security diplomacy.
The challenge for governments is that AI can simultaneously create opportunities and risks.
AI could help countries identify emerging conflicts, improve humanitarian operations, monitor ceasefires and analyze large quantities of information. At the same time, poorly governed systems could amplify security threats or make already complex conflicts more difficult to manage.
Pakistan Highlights the Global Inequality Dimension
Pakistan’s message to the Security Council went beyond military applications.
Dar also emphasized the need for AI development to be representative, transparent and inclusive, reflecting concerns among developing countries that the benefits of advanced artificial intelligence could become concentrated among a relatively small group of technologically advanced states and companies.
That concern is already reflected in the United Nations’ Global Digital Compact.
The Compact calls for closing digital divides, expanding access to the benefits of the digital economy and strengthening international governance of artificial intelligence. It specifically calls for full and equal representation of countries, including developing nations, in international AI governance.
This makes AI access and governance part of a broader development question.
Countries with advanced computing infrastructure, large datasets, sophisticated research institutions and substantial private-sector investment are positioned differently from nations that remain dependent on imported technologies and have limited domestic AI capacity.
If that gap widens, AI could potentially reinforce existing economic and technological inequalities rather than reduce them.
UN Framework Already Calls for Inclusive AI Governance
The debate at the Security Council is taking place alongside a broader UN effort to develop international mechanisms for AI governance.
The Global Digital Compact, adopted as part of the Pact for the Future, established a framework for international cooperation on digital technologies and AI.
The United Nations has subsequently established an Independent International Scientific Panel on Artificial Intelligence and a Global Dialogue on AI Governance.
The first annual Global Dialogue took place in Geneva in July 2026, bringing together governments and other stakeholders to discuss international cooperation, AI opportunities and emerging risks.
The UN says the dialogue is intended to ensure that AI governance reflects the priorities of all nations rather than only those with the greatest technological capabilities.
For developing countries such as Pakistan, this process provides an avenue to raise questions about technological access, capacity-building, data governance and participation in international rule-making.
AI and Military Decision-Making Raise Particular Concerns
One of the most sensitive areas in the AI debate is military decision-making.
AI can process enormous volumes of information far faster than humans. That capability could potentially assist military planners and governments, but it also raises questions about what happens when decisions involving force are increasingly influenced by automated systems.
A shorter decision-making cycle can create pressure to respond before human officials have fully evaluated the available information.
That is why Pakistan’s emphasis on restraint and confidence-building is significant in the context of international security.
The broader UN position has also stressed the importance of retaining meaningful human control over decisions involving the use of force.
The central issue is not simply whether AI should be used in security applications, but how governments can establish accountability when AI-assisted systems contribute to consequential decisions.
Disinformation Adds Another Layer of Risk
AI-generated content presents another challenge for governments and international organizations.
Generative AI can make it easier to create convincing text, images, audio and video at scale. In a conflict environment, such capabilities could complicate efforts to distinguish authentic information from manipulated material.
The UN has identified misinformation and disinformation among the major concerns surrounding artificial intelligence, particularly where manipulated content can affect public trust, human rights or humanitarian operations.
For international institutions, the problem is therefore both technological and political: governments must develop mechanisms capable of addressing harmful AI-generated content without undermining legitimate expression or access to information.
Global AI Governance Is Becoming More Urgent
The current Security Council discussion reflects a larger international shift.
AI governance is no longer being discussed solely in terms of innovation, investment and economic competitiveness. Governments are increasingly considering questions involving national security, international stability, human rights, development and inequality.
The United States and China, for example, continue to compete technologically while also discussing mechanisms for AI safety and communication.
Meanwhile, the UN is developing a more inclusive multilateral framework intended to give countries a role in shaping international AI governance.
That creates an important distinction between AI development and AI governance.
The first concerns how quickly capabilities advance. The second concerns the rules, safeguards and institutions that determine how those capabilities are developed and deployed.
What Pakistan’s Position Means for Developing Countries
Pakistan’s intervention highlights an issue that is likely to remain central to future AI negotiations: who gets to shape the rules governing artificial intelligence?
Developing countries have an interest not only in managing AI-related risks but also in ensuring access to the technology’s potential benefits.
The UN’s Global Digital Compact recognizes the need for capacity-building, technology cooperation and support for developing countries to access, develop, use and govern AI systems.
That approach is particularly relevant as AI becomes increasingly connected to education, healthcare, agriculture, financial services, public administration and economic productivity.
Without adequate access to computing infrastructure, skills, data and investment, developing countries could find themselves primarily consuming technologies designed elsewhere.
Pakistan’s call for representative and inclusive AI governance therefore places technological development and international security within the same broader conversation.
The Challenge Ahead: Rules That Keep Pace With Technology
The Security Council’s latest discussion illustrates the central difficulty confronting policymakers.
Artificial intelligence is developing faster than many traditional regulatory processes can respond.
International rules must address security risks without unnecessarily blocking beneficial innovation. They must also account for differences between developed and developing countries while maintaining fundamental principles such as human rights, transparency and accountability.
The United Nations’ emerging governance architecture is an attempt to address that challenge through scientific assessment, international dialogue and greater participation by countries around the world.
Pakistan’s intervention adds another voice to that debate, particularly on the consequences of unequal access to AI capabilities and the risks associated with AI-assisted military decision-making.
Conclusion
Pakistan’s warning at the UN Security Council underscores the increasingly international character of the artificial intelligence debate.
The issue is no longer simply how quickly AI can advance. It is also about how the technology is governed, who participates in setting the rules, how military risks are controlled and whether the benefits of AI are distributed broadly enough to avoid deepening existing inequalities.
As AI becomes more deeply integrated into security, economies and public institutions, international cooperation will become an increasingly important part of managing both its opportunities and its risks.
For Pakistan and other developing countries, the emerging global AI governance system will be particularly important because the rules established today could influence access to technology, economic opportunities and participation in future international decision-making for years to come.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


The dominant narrative around artificial intelligence investment has always centred on equity valuations — Nvidia’s market capitalisation, hyperscaler earnings multiples, the concentration of the S&P 500 in a handful of AI-exposed names. That narrative is now incomplete. The more consequential shift underway in 2026 is happening in credit markets, and regulators are starting to say so explicitly.
An Unprecedented Pace of Capital Deployment
The Bank of England’s July 2026 Financial Stability Report puts it plainly: the pace of AI-related investment is unprecedented historically, with AI companies increasingly turning to the financial system — and specifically to debt financing — to fund infrastructure buildouts. This marks a meaningful departure from the equity-heavy funding model that characterised the first wave of the AI boom, when cash-rich technology giants largely self-funded expansion from balance-sheet reserves.
Why Debt, and Why Now
The shift toward debt financing reflects simple scale economics: data-center construction costs have grown large enough that even the best-capitalised technology companies are choosing to preserve equity and cash flexibility by tapping bond and private credit markets instead. This dynamic accelerated sharply through the first half of 2026, coinciding with the same window in which China’s export data showed chips, computer parts and power equipment accounting for roughly half of the country’s export growth — evidence that the AI infrastructure buildout is now a genuinely global capital-expenditure cycle, not a US-only phenomenon.
The Leverage Concentration Problem
The Bank’s Financial Policy Committee has flagged a specific structural fragility: equity gains in AI-related names have been driven in significant part by a narrow, concentrated set of companies, with a substantial increase in the use of leverage tied to these positions. That combination — narrow concentration plus rising leverage — is precisely the mechanism that has historically turned isolated valuation corrections into broader, self-reinforcing liquidity events.
Separately, the Bank’s broader assessment of credit markets warns that vulnerabilities in risky asset valuations, sovereign debt markets and risky credit segments — including private credit specifically — remain, with some having become more pronounced since its previous report, as globally higher interest rates and energy-driven cost increases add pressure on corporate borrowers across the board, AI-related or otherwise.
The Sovereign Debt Connection
Perhaps the most significant — and least discussed — finding from the Bank’s analysis concerns how an AI-related equity correction could interact with sovereign bond markets. In its modelled scenario, debt-to-GDP ratios rise following a hypothetical AI valuation correction, but the Bank notes that both the US Treasury market and UK gilt market continued to function well under the scenario tested — with an explicit warning that had those markets come under pressure instead, the consequences could have been considerably more severe.
That finding sits uncomfortably alongside the Federal Reserve’s own hawkish pivot under Chair Kevin Warsh, detailed elsewhere in this series. A Fed moving toward rate hikes rather than cuts directly raises the cost of the debt financing now underpinning much of the AI infrastructure buildout — a tightening that could pressure highly leveraged data-center financing structures at precisely the moment the sector’s borrowing needs are accelerating.
What Regulators Are Doing About It
Rather than attempting to directly restrain AI-related credit growth — not typically a central bank mandate — the Bank of England is focused on strengthening the plumbing that would need to absorb a shock if one occurs. It points specifically to reforms already announced for money market funds across the UK and Europe, alongside exploratory changes to bolster resilience in the gilt repo market, as the primary tools available to prevent an AI-financing-driven credit event from cascading into broader market dysfunction.
The Investor Takeaway
For fixed-income investors and credit allocators, the practical shift is this: AI exposure can no longer be assessed purely through equity valuation multiples. The debt structures financing data-center buildouts — their leverage ratios, their sensitivity to a hawkish Fed, and their concentration among a narrow set of borrowers — now represent a distinct and growing risk factor in global credit markets, one that central banks on both sides of the Atlantic are actively modelling, even as they stop short of calling it a bubble outright.
Featured Snippet
Is AI infrastructure being funded by debt or equity in 2026? AI companies are increasingly relying on debt financing rather than equity to fund data-center buildouts, a shift the Bank of England describes as historically unprecedented in pace, raising new financial stability questions around leverage concentration and credit market resilience.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
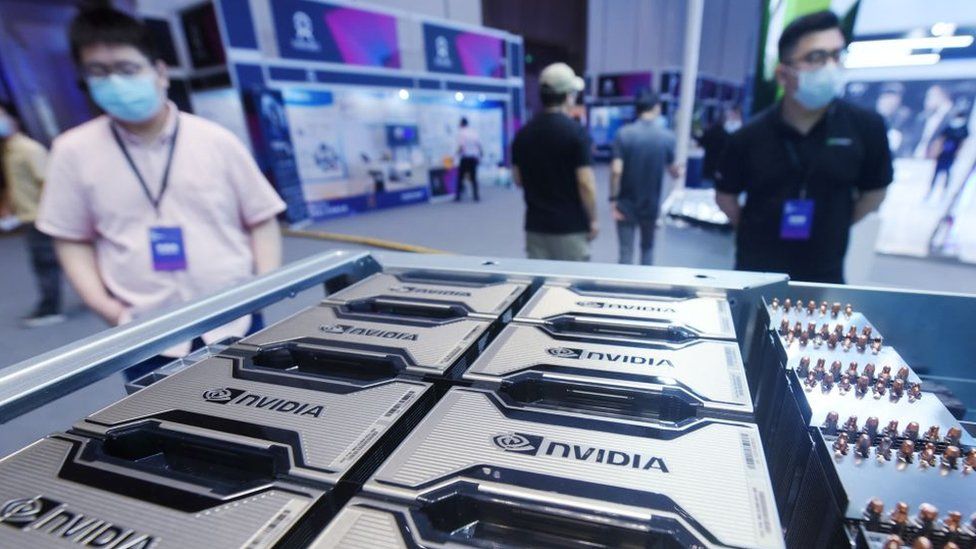
New guidance from the US Department of Commerce issued in late May 2026 has tightened licensing requirements for Nvidia’s most advanced processors, including its Blackwell series, closing a loophole that let Chinese firms acquire restricted chips through overseas subsidiaries — and putting Singapore and Malaysia squarely in Washington’s crosshairs as the two Southeast Asian hubs most exposed to diversion risk (NaturalNews).
A Trillion-Dollar Market, and a Widening Grey Zone
Under the current three-tier US export framework, Singapore and Malaysia sit in “Tier 2” alongside roughly 120 other countries, including India and the UAE, meaning firms there must obtain individual licences or validated end-user authorisation before accessing the most advanced AI chips (Asia Times). That has not stopped both markets from becoming critical waypoints in the global AI supply chain: Singapore alone accounted for roughly one-fifth of Nvidia’s $215.9 billion in revenue for the fiscal year ended January 2026, making it the company’s second-largest market after the United States.
The scale of the enforcement challenge became public in May 2026, when the US Department of Justice charged three individuals connected to a technology supplier in a scheme involving roughly $2.5 billion worth of Nvidia-powered servers, allegedly routed to Chinese brokers using dummy replicas to defeat physical audits (Model Diplomat). That case echoes an August 2025 indictment involving chip shipments transiting through Malaysia and Singapore en route to Hong Kong, underscoring how the region has become a persistent pressure point for US export enforcement.
Malaysia Moves First, Thailand Lags Behind
Regional responses have diverged sharply based on exposure and regulatory capacity. Malaysia acted earliest, introducing a mandatory Strategic Trade Permit in July 2025 covering the export, transshipment and transit of high-performance US-origin AI chips — a move widely read as Kuala Lumpur choosing to tighten oversight rather than risk its reputation as what one Eco-Business analysis calls a “weak link” in the compliance chain (Eco-Business).
Thailand has proven more exposed. In May 2026, US authorities publicly flagged a Bangkok-based firm tied to the country’s national AI initiative for allegedly helping divert billions of dollars’ worth of Nvidia-powered servers to Chinese companies including Alibaba — a case that illustrates how national AI ambitions and export-control compliance can pull governments in opposing directions.
Beijing’s Answer: Building Around the Restrictions
China’s response to tightening controls has increasingly been to accelerate domestic substitution rather than simply seek workarounds. Nvidia CEO Jensen Huang told CNBC in May that he had effectively “conceded” the Chinese data-centre market to Huawei, with the company now assuming zero data-centre chip revenue from China going forward — a remarkable admission given that the Chinese market generated an estimated $12–15 billion in H20 chip sales as recently as 2024 (Model Diplomat).
China’s own supercomputing ambitions received a symbolic boost in June 2026 when the domestically built LineShine supercomputer, developed at Shenzhen’s National Supercomputing Center, reclaimed the top spot on the global TOP500 ranking, surpassing the US-built El Capitan system. Analysts tracking China’s fifteenth five-year plan note that Beijing has explicitly directed its AI sector to develop “extraordinary measures” to defeat export controls, with domestic players Huawei, Cambricon and SMIC forecast to reach at least 50% market share within China by the end of 2026.
Why Southeast Asia Cannot Simply Pick a Side
Chatham House’s assessment of the broader export-control strategy is unusually blunt: rapid global demand growth for AI compute makes enforcement extraordinarily difficult, and countries like Malaysia and Singapore have become de facto grey markets whether or not their governments intend that outcome (Chatham House). The US Chip Security Act, working its way through Congress, aims to close some of these gaps by requiring companies to verify that chips remain in authorised locations — but even proponents acknowledge that legislation alone cannot fully police a supply chain running through dozens of jurisdictions with varying regulatory capacity.
For Singapore and Malaysia, the dilemma is structural rather than merely diplomatic: both governments actively court data-centre investment from American and Chinese firms alike, because both flows generate genuine economic value, jobs and technology transfer. Neither wants to be forced into an exclusive alignment with Washington or Beijing on chip policy, yet the political and legal risk of appearing to enable diversion is rising sharply with each new DOJ indictment. The likeliest trajectory for the rest of 2026 is not a clean resolution but an intensifying game of regulatory whack-a-mole, with Southeast Asian governments tightening rules just fast enough to avoid becoming Washington’s next enforcement headline, without fully closing the door on Chinese capital.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
The screen bled red across the trading floors of Lower Manhattan on Tuesday, pulling the curtain down on a euphoric 18-month rally. As the closing bell rang, a brutal Nasdaq AI stock sell-off had wiped out 3% of the index’s value, vaporising hundreds of billions in market capitalisation in mere hours. Yet, step away from the glare of the tech titans, and the picture shifts entirely. Small-cap industrials, regional banks, and consumer staples quietly advanced. This was not a panic. It was a surgical, deeply concentrated liquidation event targeting the very silicon and software giants that have single-handedly dragged global markets to record highs.
To understand the severity of this capital rotation, one must look at the immense concentration risk that preceded it. By late May, just five artificial intelligence bellwethers accounted for roughly 30% of the S&P 500’s total market weighting. This is a historical anomaly surpassing even the dot-com peak of early 2000. Institutional portfolios had become dangerously top-heavy. When momentum cracked, the reversal was violent.
Data from financial market trackers at Reuters revealed that trading volumes for semiconductor equities surged 45% above their 30-day moving average during the afternoon session. This mass exit eclipsed the broader market’s reality. According to global market analysis from Bloomberg, the S&P 500 equal-weight index actually closed in positive territory, highlighting a stark bifurcation. Investors aren’t fleeing equities; they’ve simply decided to cash out their AI lottery tickets and move funds into the forgotten corners of the real economy.
The mechanics of a Nasdaq AI stock sell-off rarely start with a scream; they start with a whisper in the options market. On Monday evening, institutional hedging activity spiked, signalling that major funds were quietly locking in profits on their semiconductor and cloud computing holdings. By Tuesday morning, that defensive posturing erupted into outright selling.
The trigger was a combination of stretched valuations and exhaustion. Nvidia, which had priced in a near-perfect trajectory of endless exponential growth, saw its forward price-to-earnings multiple rejected by the market. When shares of the chipmaker plunged, it dragged the entire semiconductor index down with it. A market analysis brief from the Financial Times noted that almost $400 billion in semiconductor market capitalisation evaporated in the first 90 minutes of trading alone.
That is roughly equivalent to the entire GDP of Denmark vanishing before lunch.
Still, the destruction was highly selective. Software-as-a-service providers that had recently slapped artificial intelligence onto their investor decks without demonstrating corresponding revenue growth faced the harshest penalties. Valuations in this speculative tier contracted by double digits. The market is abruptly demanding proof of concept. Generative models are expensive to train, and Wall Street won’t fund the capital expenditure without a clear line of sight to immediate profitability.
Analysts at the International Monetary Fund recently warned of this exact vulnerability, calculating that tech sector multiples had become unmoored from historical norms, leaving them acutely exposed to sudden sentiment shifts. When the narrative changed, the algorithmic trading desks amplified the slide, triggering a cascade of automated stop-loss orders. Yet, the devastation was quarantined. Outside the tech-heavy indexes, the Dow Jones Industrial Average held steady, buoyed by traditional blue-chip stocks. This divergence reveals a market that isn’t experiencing a macro-economic failure, but rather a violent recalibration of pricing in its most overextended sector.
Why a Tech Sector Correction Was Inevitable
To view Tuesday’s rout as a sudden shock is to ignore months of flashing warning lights. The market had entered a phase of inelastic exuberance. Every mention of machine learning by a Chief Executive on an earnings call was met with a blind surge in share price, creating a dangerous feedback loop of capital misallocation. The fundamental laws of financial physics were suspended, but only temporarily.
Why are AI stocks dropping? They are falling because investors have realised that the timeline for artificial intelligence to generate enterprise-level profits is vastly longer than the timeline required to build the infrastructure. Valuations priced in immediate perfection, leaving no margin for delayed adoption, regulatory hurdles, or rising capital expenditure costs.
This tech sector correction is a symptom of market digestion. The “Magnificent Seven” and their supply chains had absorbed nearly all available retail and institutional liquidity over the past year. But as the third quarter approaches, the burden of proof is shifting. Companies are now expected to demonstrate exactly how their massive investments in graphics processing units translate into bottom-line free cash flow. For many, the math simply doesn’t add up yet.
That said, the rotation out of these names is structurally healthy. When capital pools exclusively in one sector, it starves the rest of the market of investment. The fact that capital is flowing from overvalued tech darlings into energy, materials, and healthcare suggests that the underlying economy remains resilient, even if the speculative edge has been blunted. The current semiconductor stock drop is stripping the froth from the market, punishing tourists who bought the ticker symbol rather than the balance sheet. We are witnessing a transition from a momentum-driven market to one that prioritises earnings quality. The era of the blank cheque has officially closed.
The downstream consequences of this capital rotation will reshape venture capital, corporate strategy, and perhaps even monetary policy over the next 12 months. The immediate victim will be the private markets. Startup founders who have spent the last year riding the coattails of public market valuations will face a brutal awakening. Seed funding rounds that previously commanded astronomical valuations based on a sleek demo will now face rigorous due diligence. The hurdle rate for new capital just went up.
For corporate boards, the message is equally stark. The market will no longer reward performative spending. Executives who have engaged in an arms race to acquire compute power will now be pressured by activist investors to justify those expenditures. If the infrastructure doesn’t yield margin expansion or significant productivity gains, those tech budgets will be slashed. This creates a secondary risk for the chip designers and cloud providers: their current revenue run-rates are highly dependent on this very corporate arms race. If enterprise spending slows, the revenue models of the tech giants will need to be drastically revised.
From a macroeconomic perspective, this deflation of the AI market bubble may actually provide the Federal Reserve with a measure of comfort. According to research published by the World Bank, hyper-concentrated equity rallies can create artificial wealth effects that complicate inflation targeting. By cooling off the most speculative corners of the market, the central bank may find it easier to manage the broader economic glide path without triggering a deep recession. The destruction of paper wealth in Silicon Valley doesn’t immediately translate to job losses on Main Street. Instead, the normalisation of a Nasdaq 100 decline removes a significant source of systemic risk. The coming quarters will be defined by an intense focus on margins, operational efficiency, and the arduous task of turning a dazzling science project into a viable corporate utility.
What follows, however, is fiercely debated. Not everyone interprets this sell-off as a return to fundamental sanity. A vocal contingent of market strategists argues that abandoning the trade now is akin to selling internet infrastructure stocks in 1998 — a premature exit from a generational wealth-creation cycle.
Their argument rests on the sheer scale of the technological shift. Generative models aren’t merely a new software vertical; they are a general-purpose technology comparable to the internal combustion engine or electricity. A recent analysis by the OECD points out that artificial intelligence integration could increase global labour productivity by up to 1.5 percentage points annually over the next decade. If that thesis holds true, the current valuations of the top silicon producers and cloud hyper-scalers are actually conservative, not stretched.
From this perspective, Tuesday’s decline is nothing more than a momentary blip. It is viewed as a liquidity-driven shakeout designed to clear weak hands from the market. The bulls argue that the massive capital expenditures by the tech giants aren’t a sign of excess, but a necessary moat-building exercise. They contend that the broader market is overestimating the risk of delayed adoption and underestimating the exponential curve of computing power. If they are right, the capital rotating into defensive stocks today will eventually be forced back into the tech sector at a severe premium, missing the next massive leg of the rally.
The tension between these two realities — the undeniable long-term transformative power of machine learning and the immediate, punishing math of overextended equity valuations — will dictate market dynamics for the foreseeable future. Tuesday’s brutal correction was not an indictment of the technology itself, but a rejection of the timeline investors had assigned to it. The market is demanding a return to financial gravity. Capital hasn’t evaporated; it has simply grown impatient, seeking refuge in the unglamorous, cash-generating sectors of the old economy while the new economy figures out its business model.
The AI revolution is far from over, but the easy money has already been made.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Pakistan Warns UN Security Council of AI Risks to Global Peace and Equality

Fortress Diplomacy: How China’s Secretive Hongqi N701 Matches America’s Legendary “Beast”

Jennifer Garner’s Latest Projects: Business Ventures Beyond Hollywood

Horror Box Office Economics: ROI, Market Share and the 2026

Inside Pete Hegseth’s Pentagon Speech Requirements: Structural Reforms and Defense Strategy

Remembering Eliana Moreno: The Legacy of NBC LA’s “Eli in the Heli”

Rep. Thomas Massie’s Impeachment Push Against Pete Hegseth, Explained

Bloodhound Q50: Remembering the Tragic Loss of Chicago’s Rising Drill Star

iOS 27 Release Date & Siri AI: The Ultimate Tech News Guide for iPhone 18 Users

Johnny Ray and Nicole Mississippi: Attala County Case Explained

Best iPhone 18 Pro Max Cases: Premium Protection for Apple’s 2026 Flagship

2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover

Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown
Bloodhound Q50: Remembering the Tragic Loss of Chicago’s Rising Drill Star
Remembering Eliana Moreno: The Legacy of NBC LA’s “Eli in the Heli”

2026 Midterms: How Democrats Are Competing in Deep-Red Senate Seats

RFK Jr. Confirmation Investigation 2026: Health Policy Fallout Explained

North American Tariff Standoff 2026: Supply Chain Guide
-

 Featured5 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Democracy5 years ago
Missing You! SPSC
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills