Analysis
As America’s Influence in Asia Wanes, Asian Economies Are Integrating

Table of Contents
Introduction
In the 21st century, Asia has emerged as a global powerhouse, both economically and geopolitically. The region, with its diverse cultures, languages, and histories, has seen a remarkable transformation over the past few decades. One of the most significant trends is the increasing integration of Asian economies as America’s influence in the region appears to wane. This phenomenon has wide-ranging implications for the global economy, politics, and the future of international relations.
The United States, for much of the post-World War II era, played a dominant role in shaping the political and economic landscape of Asia. The American presence was felt through alliances, trade partnerships, and military bases across the region. However, in recent years, we have witnessed a gradual shift in the balance of power. As America’s focus turned inward, and its foreign policy priorities evolved, Asia began to chart its own course. This article will delve into the factors driving the integration of Asian economies and how it is redefining the dynamics of the region.
I. The Changing Geopolitical Landscape
A. The Rise of China
One of the most significant drivers of the changing dynamics in Asia is the rise of China. With its rapid economic growth, China has become an economic juggernaut and a global superpower. Its Belt and Road Initiative (BRI) is reshaping the infrastructure and trade landscape across Asia, connecting China to countries throughout the region and beyond. The BRI, coupled with China’s increasing military capabilities, has significantly altered the balance of power in Asia.
China’s assertiveness in the South China Sea, its territorial disputes with neighboring countries, and its growing influence in international organizations have all raised concerns among its neighbors and global powers like the United States. The perception of a more powerful and assertive China has prompted Asian countries to rethink their alliances and seek greater economic and political autonomy.
B. U.S. Policy Shifts
The United States, for decades, played a pivotal role in ensuring stability and security in Asia. Its military alliances with countries like Japan and South Korea provided a strong deterrent against potential threats. However, recent shifts in U.S. foreign policy have raised questions about its long-term commitment to the region.
The “America First” policy of the Trump administration signaled a more transactional approach to foreign relations, leading many Asian countries to seek alternative partnerships. Furthermore, the U.S. withdrawal from the Trans-Pacific Partnership (TPP) and its reluctance to fully engage in regional trade agreements like the Regional Comprehensive Economic Partnership (RCEP) left a void that Asian nations were eager to fill.
II. Economic Integration in Asia
A. Regional Trade Agreements
One of the most visible manifestations of Asian economic integration is the proliferation of regional trade agreements. The RCEP, signed in November 2020, is the world’s largest trade pact, covering nearly one-third of the global population and GDP. It includes countries like China, Japan, South Korea, Australia, and the ten member states of the Association of Southeast Asian Nations (ASEAN).
The RCEP is just one example of the growing trend of Asian countries coming together to promote economic cooperation. These agreements are seen as a way to reduce dependence on any single market, diversify export destinations, and promote economic growth. They also provide a platform for dialogue on non-economic issues, further deepening regional integration.
B. Supply Chain Resilience
The COVID-19 pandemic exposed vulnerabilities in global supply chains, prompting many Asian countries to rethink their economic strategies. The desire for supply chain resilience has led to a reevaluation of trade relationships and an emphasis on regional production networks.
Countries like Japan, for instance, have introduced policies to encourage companies to diversify their supply chains away from overreliance on China. This has opened up opportunities for greater economic integration within Asia, as countries seek to build more robust and diverse supply chains by collaborating with neighboring nations.
C. Infrastructure Investment
Infrastructure development is another key driver of Asian economic integration. China’s BRI, as mentioned earlier, is a prime example of the massive infrastructure investments taking place across the region. These projects not only promote connectivity but also foster economic interdependence.
In response to China’s BRI, Japan has launched its own infrastructure initiative, the Partnership for Quality Infrastructure (PQI). Other countries, such as India, are also investing heavily in infrastructure development to enhance regional connectivity.
III. Implications of Asian Economic Integration
A. Economic Growth and Prosperity
The integration of Asian economies has the potential to drive significant economic growth and prosperity. By increasing trade and investment flows among nations, economies can benefit from the comparative advantages of their neighbours. This can lead to increased innovation, higher productivity, and ultimately, improved living standards for millions of people in the region.
B. Geopolitical Implications
As Asian economies become more integrated, they also become more interdependent. This interdependence can act as a stabilizing force, reducing the likelihood of conflicts among nations. However, it can also create challenges if disputes arise, as economic ties can be used as leverage in diplomatic negotiations.
The changing dynamics in Asia have also led to shifts in alliances and partnerships. Some countries are hedging their bets by maintaining strong ties with both the United States and China, while others are aligning more closely with one or the other. This fluidity in alliances is a reflection of the evolving power dynamics in the region.
C. Global Trade and Investment
The integration of Asian economies has far-reaching implications for global trade and investment. As Asia becomes more economically cohesive, it strengthens its position as a global economic powerhouse. This, in turn, affects the balance of power in international institutions like the World Trade Organization (WTO) and the International Monetary Fund (IMF).
Moreover, the rise of regional trade agreements in Asia challenges the traditional dominance of global trade agreements. The WTO, which has struggled to reach meaningful agreements in recent years, faces competition from regional pacts like the RCEP that set their own trade rules.
IV. Challenges and Considerations
A. Economic Disparities
While economic integration offers numerous benefits, it also brings to the forefront issues of economic inequality within and among countries. Not all nations in Asia are on an equal footing, and some may struggle to keep up with the pace of integration. Addressing these disparities is crucial to ensuring that the benefits of integration are shared more broadly.
B. Political Differences
Asia is not a monolithic bloc, and political differences among nations persist. Historical rivalries, territorial disputes, and differing political systems can create tensions that hinder deeper integration. Resolving these political differences will be an ongoing challenge for the region.
C. External Factors
External factors, such as the United States’ foreign policy decisions, global economic trends, and geopolitical developments, can all influence the trajectory of Asian economic integration. The region must navigate these uncertainties while pursuing its integration goals.
Conclusion
As America’s influence in Asia undergoes a transformation, the integration of Asian economies is gaining momentum. The rise of China shifts in U.S. foreign policy, and a growing emphasis on regional cooperation are reshaping the geopolitical and economic landscape of the continent. This integration has the potential to drive economic growth, enhance regional stability, and redefine the global balance of power.
However, the journey toward greater economic integration in Asia is not without its challenges. Economic disparities, political differences, and external factors all present obstacles that must be navigated carefully. Nevertheless, the determination of Asian nations to shape their own destiny and assert their influence on the world stage is a defining feature of the 21st century.
In today’s changing world, it is crucial to closely monitor the growth of Asia and its economic integration. The choices made by Asian nations in the upcoming years will not only impact their own futures but also have significant consequences for the global community. With the evolution of America’s role in Asia, the narrative of Asian economic integration will undoubtedly steer the direction of the 21st century.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


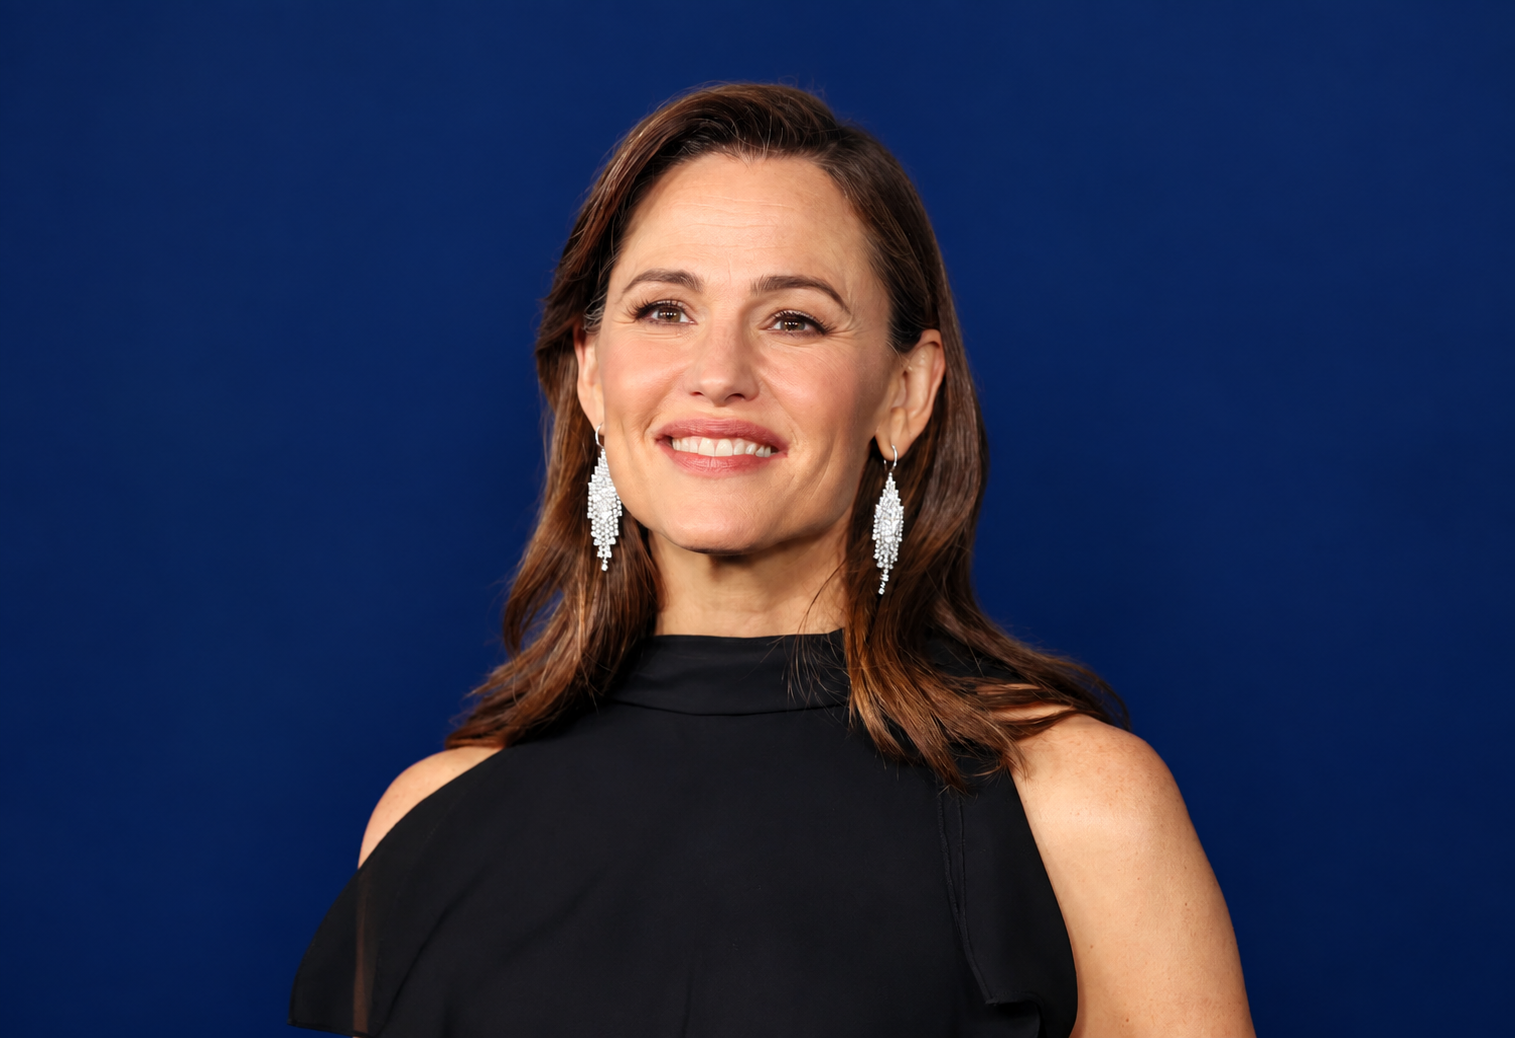
Most celebrity business ventures are licensing deals wearing a founder’s costume. The name goes on the label, the cheque clears, and an operating company nobody has heard of does the actual work.
Jennifer Garner’s is not that. On 6 February 2026, she rang the opening bell at the New York Stock Exchange as Once Upon A Farm went public at $18 per share with a valuation of $724 million.
The company she co-founded is now a listed public entity with audited financials, a board seat in her name, and a stock price that has since gone down. That last detail is the most interesting part of the story.
Key Takeaways
- The IPO: Once Upon A Farm listed on the NYSE as OFRM, raising $197.9 million at the midpoint of its marketed range.
- The pop: shares closed day one up about 17%, then traded at $25.10 by 9 February — nearly 40% above the listing price.
- The reality check: the stock was down about 15% for the year by August 2026.
- The business is real: $225 million in annual revenue for the year ending September 2025, up more than 40%.
- Her role is contractual and disclosed: board director, co-founder and spokesperson, with compensation set out in the S-1.
What Once Upon A Farm Actually Is
The company sells organic, cold-pressed refrigerated food for children — pouches, smoothies, applesauce and oat bars — through grocery retail and direct-to-consumer channels.
It was founded by serial entrepreneurs Cassandra Curtis and Ari Raz, with Garner and CEO John Foraker joining as co-founders two years later. Foraker’s background matters to the credibility of the operation: he ran Annie’s Homegrown for more than a decade and served as a president at General Mills.
Note: founding-date reporting varies between 2011 and 2015 depending on the source. Verify before publication.
The Financial Trajectory
| Metric | Figure |
|---|---|
| Annual revenue (yr ending Sept 2025) | $225 million |
| Year-on-year growth | Over 40% |
| CAGR since 2018 | More than 60% |
| IPO valuation | $724 million |
| Capital raised | $197.9 million |
| Shares sold by company | ~7.6 million |
| Shares sold by existing holders | ~3.4 million |
| Lead bookrunners | Goldman Sachs, JPMorgan Chase |
A compound annual growth rate above 60% sustained over seven years is not a celebrity endorsement outcome. It is a consumer packaged goods outcome — and CPG is one of the hardest categories in which to build distribution from scratch.
What Her Actual Job Is
This is where the Once Upon A Farm story diverges most sharply from the celebrity-brand template, because the terms are public.
The S-1 discloses that Garner serves on the public company’s board of directors and continues as co-founder and spokesperson — “Farmer Jen” — a role for which she was paid $1 million in the prior year, with $2 million to $3 million in expected annual compensation through 2028, separate from stock options and an IPO-linked bonus.
She also worked the roadshow directly. Garner described the investor meetings to Forbes as rooms full of existing customers, noting that families already trusted the product.
That is a meaningful distinction for anyone assessing celebrity-backed companies. There is a difference between a founder who licenses a likeness and a founder who sits on the board, pitches institutional investors and has compensation disclosed in a registration statement.
The Mission Structure
Once Upon A Farm is a public benefit corporation — the “PBC” in its legal name — which means its charter permits management to weigh mission alongside shareholder returns.
Garner has framed the IPO itself as a mission decision. Selling to a major food conglomerate would have cost the existing team control of the business; a listing preserved it while raising capital.
The concrete expression of that mission is WIC certification. Getting products approved so low-income families can purchase them through the federal nutrition programme has been a stated priority, and the brand now holds that distinction in more than 20 states. Garner has called it the company’s north star.
It connects to a longer track record — she had been a trustee for Save the Children for several years before joining the company in 2017.
The Risks the Prospectus Discloses
A public listing forces disclosure that private celebrity ventures never face. Three risks stand out.
Tariff and sourcing exposure. The prospectus highlighted risks related to tariffs and trade barriers, particularly against Mexico and South America, from where the company sources a significant portion of its fruit and vegetable ingredients.
Key-person concentration. A brand built substantially on one founder’s public identity carries a risk no diversified CPG company does.
Acquisition framing. Ahead of the listing, Hedgeye analyst Bennett Cheer characterised the company as an acquisition “play” — a view that treats the IPO as a staging post toward a strategic sale rather than a destination.
The Post-IPO Slide, and What It Tells You
The stock’s path is the honest part of this story. Priced at $18, up 17% on day one, close to $25 within a week, then down roughly 15% for the year by August.
Garner’s stated response has been to ignore the daily price and focus on execution — her position being that the stock follows the mission rather than the reverse.
Whether or not one finds that convincing as investor communication, the underlying pattern is common and worth understanding. Consumer IPOs frequently pop on scarcity — the listing was described as a rare food offering that excited investors — and then reprice once the float settles and quarterly results replace the narrative.
For investors, the lesson generalises. A founder’s celebrity generates demand at listing. It does not generate gross margin.
The Broader Commercial Portfolio
Beyond Once Upon A Farm, Garner’s commercial activity follows a consistent pattern: long-term brand relationships rather than one-off endorsements.
She has been the recurring face of Capital One’s advertising campaigns, continuing through 2026. She brokered Once Upon A Farm’s first sports sponsorship in 2024 — a multi-year deal making it Angel City FC’s exclusive children’s snack partner.
She was named to the Forbes 50 Over 50 class of 2026 at age 54, alongside continued acting work.
What This Means for the Global Market in 2027
Coverage of celebrity businesses stops at the launch. Here is what actually determines outcomes.
Public listing is the real test of a celebrity brand. Private valuations are negotiated; public ones are voted on daily. Expect more celebrity-founded consumer companies to attempt listings after this precedent — and expect most to trade below their debut.
Governance disclosure becomes the differentiator. Once Upon A Farm published its founder compensation structure. Investors evaluating the next celebrity IPO should ask for the same and treat its absence as a signal.
Tariff exposure is the underpriced risk in food CPG. Companies sourcing produce from Mexico and South America face input volatility that margin models built in a stable trade environment do not capture.
The PBC structure will be tested. A public benefit corporation’s mission commitments have not yet been stress-tested against a sustained share price decline. Once Upon A Farm may become the case study.
Acquisition remains the likely endgame. If the Hedgeye thesis holds, a strategic buyer eventually acquires the brand. The question for shareholders is whether that happens above or below the $18 listing price.
Frequently Asked Questions
What company did Jennifer Garner found?
Garner is a co-founder and chief brand officer of Once Upon A Farm, an organic children’s food company. She joined in September 2017 alongside CEO John Foraker; the business was originally founded by Cassandra Curtis and Ari Raz.
When did Once Upon A Farm go public?
The company listed on the New York Stock Exchange under the ticker OFRM on 6 February 2026, pricing at $18 per share for a valuation of $724 million and raising $197.9 million.
How much revenue does Once Upon A Farm generate?
The company reported $225 million in annual revenue for the year ending September 2025, representing growth of more than 40% year-on-year and a compound annual growth rate above 60% since 2018.
Is Jennifer Garner paid by Once Upon A Farm?
Yes, and the terms are disclosed. She was paid $1 million in the year before the IPO, with $2 million to $3 million in expected annual compensation through 2028, separate from stock options and an IPO-linked bonus.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
Horror took 12.1% of US ticket sales in 2025, up from 9.8%. Inside the ROI gap between indie horror and studio blockbusters, and what 2026 changed.Horror is the only major genre currently increasing both its supply of films and its total grosses, while mid-budget production declines everywhere else. That single fact explains most of what is happening to theatrical distribution strategy.
Executive Summary / Key Takeaways
- Horror accounted for 12.1% of US domestic ticket sales in 2025, up from 9.8% in 2024, generating $843.88 million and 14.91% of total box office revenue through August 2025.
- Horror generated roughly $16 million per film in 2024 — about four times the drama average of $4 million and 33 times the documentary average.
- Indie economics are the extreme case: Terrifier 3 turned a $2 million budget into $51.6 million domestic, a 43.5x return, while Longlegs turned $10 million into $74.4 million.
- 2025 produced three $100 million-plus domestic horror titles — Sinners, Weapons and Final Destination Bloodlines — with Sinners delivering the largest horror domestic gross since It in 2017.
- 2026 sustained the run: Backrooms sits at $394.1 million worldwide on the all-time horror list, and studios now treat horror as a year-round release category rather than a seasonal one.
Through August 2025, horror films accounted for 14.91% of total box office revenue, generating $843.88 million, and the genre’s share of domestic ticket sales rose from 9.8% in 2024 to 12.1% in 2025, according to industry data compilations. In 2023 horror accounted for more than 10% of box office revenue, having doubled its share in a decade.
The efficiency figures are more striking than the share figures. Horror ranked fifth by gross in 2024 at $847 million but generated $16.0 million per film — four times the drama average and 33 times the documentary average — and produced 9.84% of domestic box office from just 7.8% of total releases, per the Screamwire Horror Industry Report.
2. Core Financial Analysis
2.1 The ROI ladder
| Film | Budget | Domestic / worldwide gross | Multiple | Category |
|---|---|---|---|---|
| Terrifier 3 | ~$2m | $51.6m domestic | 43.5x | Micro-budget indie |
| Longlegs | ~$10m | $74.4m domestic | ~7.4x | Indie / specialty |
| M3GAN | $10–20m | $126.9m | 6–12x | Studio genre (Blumhouse model) |
| Weapons | Mid-budget | $269.9m worldwide | — | Studio original, R-rated |
| Sinners | Mid-budget | $370.2m worldwide | — | Studio original, R-rated |
| Final Destination Bloodlines | Franchise | $317.8m worldwide | — | Franchise reboot |
| The Conjuring: Last Rites | Franchise | $499.1m worldwide | — | Established universe |
| Backrooms (2026) | A24 | $394.1m worldwide | — | IP adaptation |
Gross figures compiled from Wikipedia’s horror film records and the all-time list; budget and multiple data from the Screamwire report.
The distribution is bimodal, and that is the important structural point. Micro-budget indie horror delivers extraordinary multiples on small absolute returns. Franchise horror delivers large absolute returns on modest multiples. The squeezed middle — the $40–70 million genre film with no IP and no breakout hook — is where losses concentrate, which is the same squeeze killing mid-budget production across every other genre.
2.2 The 2025 originals
The most commercially significant development was the performance of original R-rated horror. Weapons became the second original R-rated film of the year to reach $100 million domestically after Sinners, at a time when the wider genre was under pressure, according to The Hollywood Reporter. Weapons reached the $100 million North American mark in its fourteenth day against nine days for Sinners, which opened to $48 million, and narrowly bested Jaws on an unadjusted basis to rank as the top-grossing R-rated horror film domestically — though its worldwide tally sat well behind Jaws globally.
Sinners‘ domestic gross of roughly $279.6 million was the largest for a horror film since It reached $328.8 million in 2017.
2.3 What 2026 looked like
The year front-loaded unusually. January and February accounted for the overwhelming majority of the genre’s Q1 revenue, buoyed by Scream 7, Send Help, Iron Lung and Primate, before March went quiet outside a few smaller titles, per IndieWire. The publication’s key observation: in 2026, studios are still treating horror as a year-round attraction rather than a seasonal afterthought.
By mid-year, horror had become one of the year’s dominant commercial stories, with Obsession — a Focus Features psychological thriller from Curry Barker — leading the genre and A24’s Backrooms adapting an internet creepypasta into a major release, according to trade roundups.
3. Structural Drivers and Competitor Gaps
Performance intensity is a budget line that pays. The commercial argument for immersive, physically demanding performances in genre film is not artistic — it is marketing efficiency. A transformation performance generates earned media, awards-adjacent coverage and word-of-mouth that a $40 million marketing spend would otherwise have to buy. Terrifier 3‘s 43.5x return did not come from advertising; it came from a performance and a reputation that travelled without it.
Horror is countercyclical in a specific way. Its economics do not depend on premium formats, international star recognition or family co-viewing — the three things a contracting theatrical market damages most. That is why horror supply is rising while mid-budget production falls generally.
Franchise universes compound. The Conjuring universe has grossed roughly $2.4 billion worldwide across eight films. Once an established universe exists, each subsequent entry carries lower marketing cost per dollar of gross, which is why studios pursue universe construction over one-off successes even when the one-offs have better multiples.
Streaming is a complement, not a substitute. Shudder set viewership records in 2024, doubling total hours, and horror’s October streaming share reached 15.8%. The genre appears to sustain both theatrical and at-home demand simultaneously, which is not true of most categories.
The gap in most coverage. Analysts consistently report horror’s revenue share without reporting its revenue efficiency. Share is a demand statistic; efficiency is an investment statistic. A genre producing 9.84% of domestic box office from 7.8% of releases is outperforming on a per-slot basis, and that ratio — not the headline share — is what should drive greenlight decisions.
4. Key Implications for Stakeholders
Entertainment investors. The barbell is the actionable structure: micro-budget indie horror for multiple, established franchise horror for absolute return, and nothing in between. The $40–70 million original genre film is the category to avoid.
Film industry observers. Watch whether 2026’s originals replicate 2025’s. The genre’s health currently rests on original R-rated titles performing at franchise levels, which is historically unusual and may not persist.
Distributors. The seasonal assumption is obsolete. January and February carried the majority of Q1 2026 horror revenue, and studios releasing horror year-round are capturing calendar slots that used to be conceded to family and awards product.
Producers. Casting for transformation is a defensible budget allocation in this genre specifically, because the performance itself functions as a marketing asset in a way it does not in most categories.
5. Frequently Asked Questions
Q1: How much of the box office is horror?
Horror accounted for 12.1% of US domestic ticket sales in 2025, up from 9.8% in 2024, and 14.91% of total box office revenue through August 2025 on $843.88 million of gross.
Q2: Is indie horror more profitable than studio horror?
On return multiple, yes. Terrifier 3 turned roughly $2 million into $51.6 million domestic — about 43.5x — while franchise titles like The Conjuring: Last Rites deliver far larger absolute grosses at lower multiples.
Q3: What was the highest-grossing horror film of 2025?
Among dedicated horror titles, The Conjuring: Last Rites led at $499.1 million worldwide, followed by Sinners at $370.2 million and Final Destination Bloodlines at $317.8 million.
Q4: Why are studios releasing horror year-round now?
Because the seasonal model left revenue on the table. In 2026, January and February produced the overwhelming majority of Q1 horror revenue, confirming that demand is not confined to autumn.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
Analysis
Inside Pete Hegseth’s Pentagon Speech Requirements: Structural Reforms and Defense Strategy
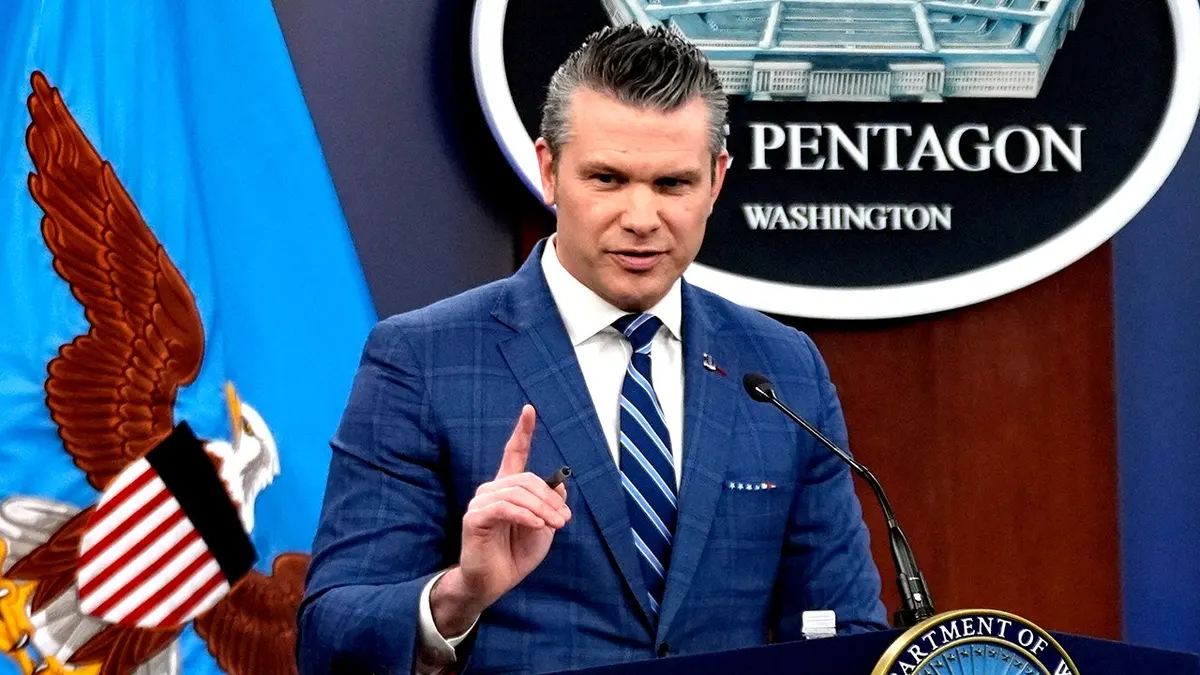
Pentagon commanders told to nominate troops meeting waist-to-height and grooming standards for the Sept 30 State of the Force address. What the memo says.
Executive Summary / Key Takeaways
- Internal emails reviewed by The Wall Street Journal show the Pentagon asked commanders to nominate service members meeting specific physical and grooming criteria to attend Hegseth’s “State of the Force” address on 30 September 2026.
- Nominees must pass the Army fitness test, meet its waist-to-height ratio requirement, and maintain “impeccable” grooming and uniform standards with no exceptions.
- Selection also weighs “demonstrated leadership quality and professional character,” with a clear record of integrity, discipline and selfless service.
- Selected attendees may have the opportunity to take part in a physical training session with the secretary.
- The event falls exactly one year after the Quantico address to senior officers, where physical standards were a central theme — making this a measurable one-year checkpoint on that policy agenda.
Attendance criteria for a cabinet secretary’s speech would normally be an administrative footnote. In this case the criteria are the policy statement.
The Pentagon has asked commanders to nominate troops to attend Defense Secretary Pete Hegseth’s “State of the Force” address, specifying that service members must meet waist-to-height requirements and exhibit “impeccable” grooming standards, according to emails reviewed by the Wall Street Journal and summarised by Newsweek and other outlets. Candidates will be selected based on demonstrated leadership quality and professional character, and will also have the opportunity to work out with the secretary.
The guidance was sent to Army commanders and specifies that nominees must pass the Army’s fitness test and meet its waist-to-height ratio requirement, with grooming standards applying without exception. Nominees are expected to be top performers within their units, with a clear record of integrity, discipline and selfless service, and to demonstrate strong presence, clear communication and sound judgment under pressure — serving as model representatives for peers and subordinates across the joint force. A Pentagon official declined to comment on the specific selection criteria.
2. Core Strategic Analysis
2.1 What the memo requires
| Requirement | Standard specified | Applies to | Source |
|---|---|---|---|
| Physical fitness | Must pass the Army fitness test | Nominated attendees | WSJ via Newsweek |
| Body composition | Must meet Army waist-to-height ratio | Nominated attendees | WSJ |
| Appearance | “Impeccable” grooming and uniform standards, no exceptions | Nominated attendees | WSJ |
| Character | Demonstrated leadership quality, professional character | Selection criterion | WSJ |
| Record | Clear record of integrity, discipline, selfless service | Selection criterion | WSJ |
| Event date | 30 September 2026 | “State of the Force” address | WSJ |
| Additional | Possible physical training session with the secretary | Selected attendees | WSJ |
2.2 The one-year policy arc
The address arrives exactly one year after Hegseth summoned senior generals and admirals to Marine Corps Base Quantico on 30 September 2025 for a speech centred on warrior ethos and combat readiness. Physical standards were a central theme of that address, which introduced new height and weight requirements across the armed forces. “It all starts with physical fitness and appearance,” Hegseth told the audience, framing his reforms as a matter of institutional standards and telling officers unwilling to enforce them to resign.
Subsequent implementation showed the Quantico directives being treated as binding orders across the services, with wing-level distribution of memoranda and service-specific implementation guidance following. Reporting also noted the introduction of testosterone screening for service members over 30 as part of the broader fitness agenda.
That history is what makes the current memo analytically significant rather than merely unusual. It is the second consecutive September in which physical standards have been the organising theme of the department’s flagship internal address — which suggests a sustained programme rather than a one-off emphasis.
3. Structural Drivers and Competitor Gaps
Most coverage of this story has focused on the novelty of the attendance criteria. The more consequential questions for defence contractors, analysts and policy trackers sit one level down.
Retention and medical exemption policy. The grooming component intersects with a long-standing medical exemption framework. Many Black service members have historically received medical shaving waivers because the structure of their hair causes ingrown bumps, irritation and infection when shaved — a condition recognised in military medicine. How “no exception” language interacts with existing medical waiver policy is the practical implementation question, and it has direct workforce consequences across a force of roughly 2.1 million personnel.
Departmental renaming. Several outlets now refer to Hegseth by the title Secretary of War rather than Secretary of Defense, reflecting the department’s rebranding under the current administration. For procurement documentation, contract citations and regulatory filings, the nomenclature change is not cosmetic — it affects how policy documents are indexed and cited.
Signal versus substance for contractors. A standards-and-readiness agenda has budget implications that differ sharply from a platform-and-procurement agenda. Physical readiness, medical screening, training infrastructure and personnel systems are a different contracting universe from shipbuilding or munitions. Defence-sector analysts tracking where discretionary attention is going should read the repeated emphasis on personnel standards as a directional indicator.
Selection mechanics as message control. Hand-selecting an audience by physical criteria produces an audience that visually embodies the policy being announced. Whether that is read as reinforcing standards or as staging depends substantially on the observer’s priors, and both readings have been advanced in coverage of the memo. The verifiable facts are the criteria themselves and the date.
4. Key Implications for Stakeholders
Defence contractors. The consistency of the personnel-standards theme across two consecutive years suggests durable budget attention in human-performance, medical screening and training services rather than a passing emphasis. Watch the FY2027 budget request for corroboration.
Political and policy analysts. The 30 September address is the clearest scheduled opportunity to assess what has actually changed in the year since Quantico. Substantive markers to watch: whether new force-wide requirements are announced, whether existing standards are revised, and whether the medical waiver framework is addressed directly.
Military intelligence and HR professionals. Implementation guidance, not the speech, is where the operational content will sit. Last year’s pattern saw memoranda distributed across wings with service-specific guidance following separately.
Journalists and researchers. Original documentation lives at Defense.gov. Given the volume of secondary aggregation around this story, primary releases are the appropriate citation source.
5. Frequently Asked Questions
Q1: What are the requirements to attend Pete Hegseth’s Pentagon speech?
Nominated service members must pass the Army fitness test, meet the Army’s waist-to-height ratio requirement, and maintain impeccable grooming and uniform standards with no exceptions. Commanders also weigh demonstrated leadership quality, professional character and a clear record of integrity and discipline.
Q2: When is the State of the Force address?
The address is scheduled for 30 September 2026 — exactly one year after Hegseth’s Quantico speech to senior generals and admirals, which also centred on physical standards and combat readiness.
Q3: Who selects the troops who attend?
Military commanders across the branches were instructed by internal email to nominate junior officers and enlisted personnel meeting the stated criteria. A Pentagon official declined to comment on the specific requirements.
Q4: Will attendees do anything besides listen to the speech?
The internal emails indicate selected troops will have the opportunity to take part in a physical training session with the secretary.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Jennifer Garner’s Latest Projects: Business Ventures Beyond Hollywood

Horror Box Office Economics: ROI, Market Share and the 2026

Inside Pete Hegseth’s Pentagon Speech Requirements: Structural Reforms and Defense Strategy

Remembering Eliana Moreno: The Legacy of NBC LA’s “Eli in the Heli”

Rep. Thomas Massie’s Impeachment Push Against Pete Hegseth, Explained

Bloodhound Q50: Remembering the Tragic Loss of Chicago’s Rising Drill Star

iOS 27 Release Date & Siri AI: The Ultimate Tech News Guide for iPhone 18 Users

Club América’s Financial Playbook: The Economics and Valuation of Latin American Football

Best iPhone 18 Pro Max Cases: Premium Protection for Apple’s 2026 Flagship

Johnny Ray and Nicole Mississippi: Attala County Case Explained

2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover
Best iPhone 18 Pro Max Cases: Premium Protection for Apple’s 2026 Flagship

Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown
Remembering Eliana Moreno: The Legacy of NBC LA’s “Eli in the Heli”

2026 Midterms: How Democrats Are Competing in Deep-Red Senate Seats
Bloodhound Q50: Remembering the Tragic Loss of Chicago’s Rising Drill Star

RFK Jr. Confirmation Investigation 2026: Health Policy Fallout Explained

North American Tariff Standoff 2026: Supply Chain Guide
-

 Featured5 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Democracy5 years ago
Missing You! SPSC
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills