Economy
Will 2024 Usher in Sunshine or Storm Clouds for the UK Economy?

As 2023 draws to a close, the UK economy finds itself perched precariously on a precipice. The year was marked by near-stagnation, ravaged by a potent cocktail of rising inflation, cost-of-living pressures, and the lingering reverberations of the war in Ukraine. Yet, amidst the storm clouds, faint glimmers of hope peek through, prompting cautious optimism for 2024.
The Shadow of 2023: A Year of Economic Turbulence
The headlines of 2023 painted a grim picture of the UK economy. Inflation skyrocketed, reaching a 40-year high of 11.1% in October, driven by a perfect storm of global factors like the war in Ukraine, surging energy prices, and supply chain disruptions. This translated into a crushing cost-of-living crisis, squeezing household budgets and dampening consumer confidence. Wage growth failed to keep pace with inflation, further eroding purchasing power and pushing more into economic hardship.

Growth remained anaemic, teetering at the edge of stagnation. The International Monetary Fund (IMF) downgraded its UK growth forecast for 2023 to 0.6%, down from a previous estimate of 1.7%. Businesses grappled with rising costs, supply chain bottlenecks, and faltering consumer demand, leading to investment hesitancy and subdued economic activity.
The Bank of England (BoE) took centre stage in this economic drama, embarking on an aggressive campaign of interest rate hikes in a bid to curb inflation. This, however, came at the cost of dampening economic activity further, raising concerns about the possibility of a recession.
Glimmers of Hope: Reasons for Cautious Optimism
Despite the bleak 2023 landscape, several factors offer cautious optimism for a potential economic turnaround in 2024.
Easing inflation: Recent data suggests that inflation has peaked and may be on a downward trajectory. The BoE expects inflation to fall below 4% by the end of 2024, providing much-needed relief to households and businesses.
Energy price stabilization: While still volatile, global energy prices have moderated from their earlier highs, offering some breathing room for consumers and businesses facing high energy bills.
Robust job market: The UK unemployment rate remains near a record low, and job vacancies continue to outnumber the unemployed. This strong labour market provides a counterpoint to the challenges posed by inflation and stagnant growth.
Policy adjustments: The BoE may begin to ease its hawkish monetary stance as inflation comes down, providing a potential boost to economic activity. Government support measures, such as the recently announced energy price cap extension, could further alleviate cost-of-living pressures.
Challenges Remain: Clouds on the Horizon
Despite the positive signals, significant challenges remain on the path to economic recovery.
Geopolitical uncertainty: The war in Ukraine continues to cast a long shadow, with the potential for further disruptions to global supply chains and energy markets.
Global economic slowdown: The IMF has warned of a synchronised global slowdown in 2024, posing risks to the UK’s export-oriented economy.
Brexit hangover: The long-term economic consequences of Brexit continue to unfold, with potential frictions in trade and investment impacting businesses and growth.
Navigating the Economic Crossroads: What Lies Ahead?
The success of the UK economy in 2024 will hinge on its ability to navigate these challenges and capitalize on emerging opportunities.
- Fiscal prudence: Balancing fiscal support for struggling households and businesses with responsible debt management will be crucial. Targeted interventions, rather than broad-based stimulus, may be more effective in promoting growth without exacerbating inflation.
- Boosting investment: Fostering investment in key sectors like infrastructure, green energy, and innovation can drive long-term productivity and growth. Streamlining regulations and creating a business-friendly environment will be essential.
- Investing in skills: Addressing skills shortages and investing in education and training can enhance workforce competitiveness and boost productivity.
- Strengthening trade ties: Diversifying trade partnerships and pursuing free trade agreements with key emerging markets can mitigate Brexit-related risks and open up new opportunities for businesses.
Conclusion: A Year of Crossroads for the UK Economy
2024 stands as a year of crossroads for the UK economy. The shadows of 2023’s challenges linger, but glimmers of hope shine through, suggesting the possibility of a brighter economic future. Yet, the path to recovery remains narrow and uncertain. Navigating this economic tightrope will require astute policy decisions, unwavering commitment to growth, and a collective effort to weather the remaining storms. Whether 2024 ushers in sunshine or storm clouds for the UK economy depends on how effectively it
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


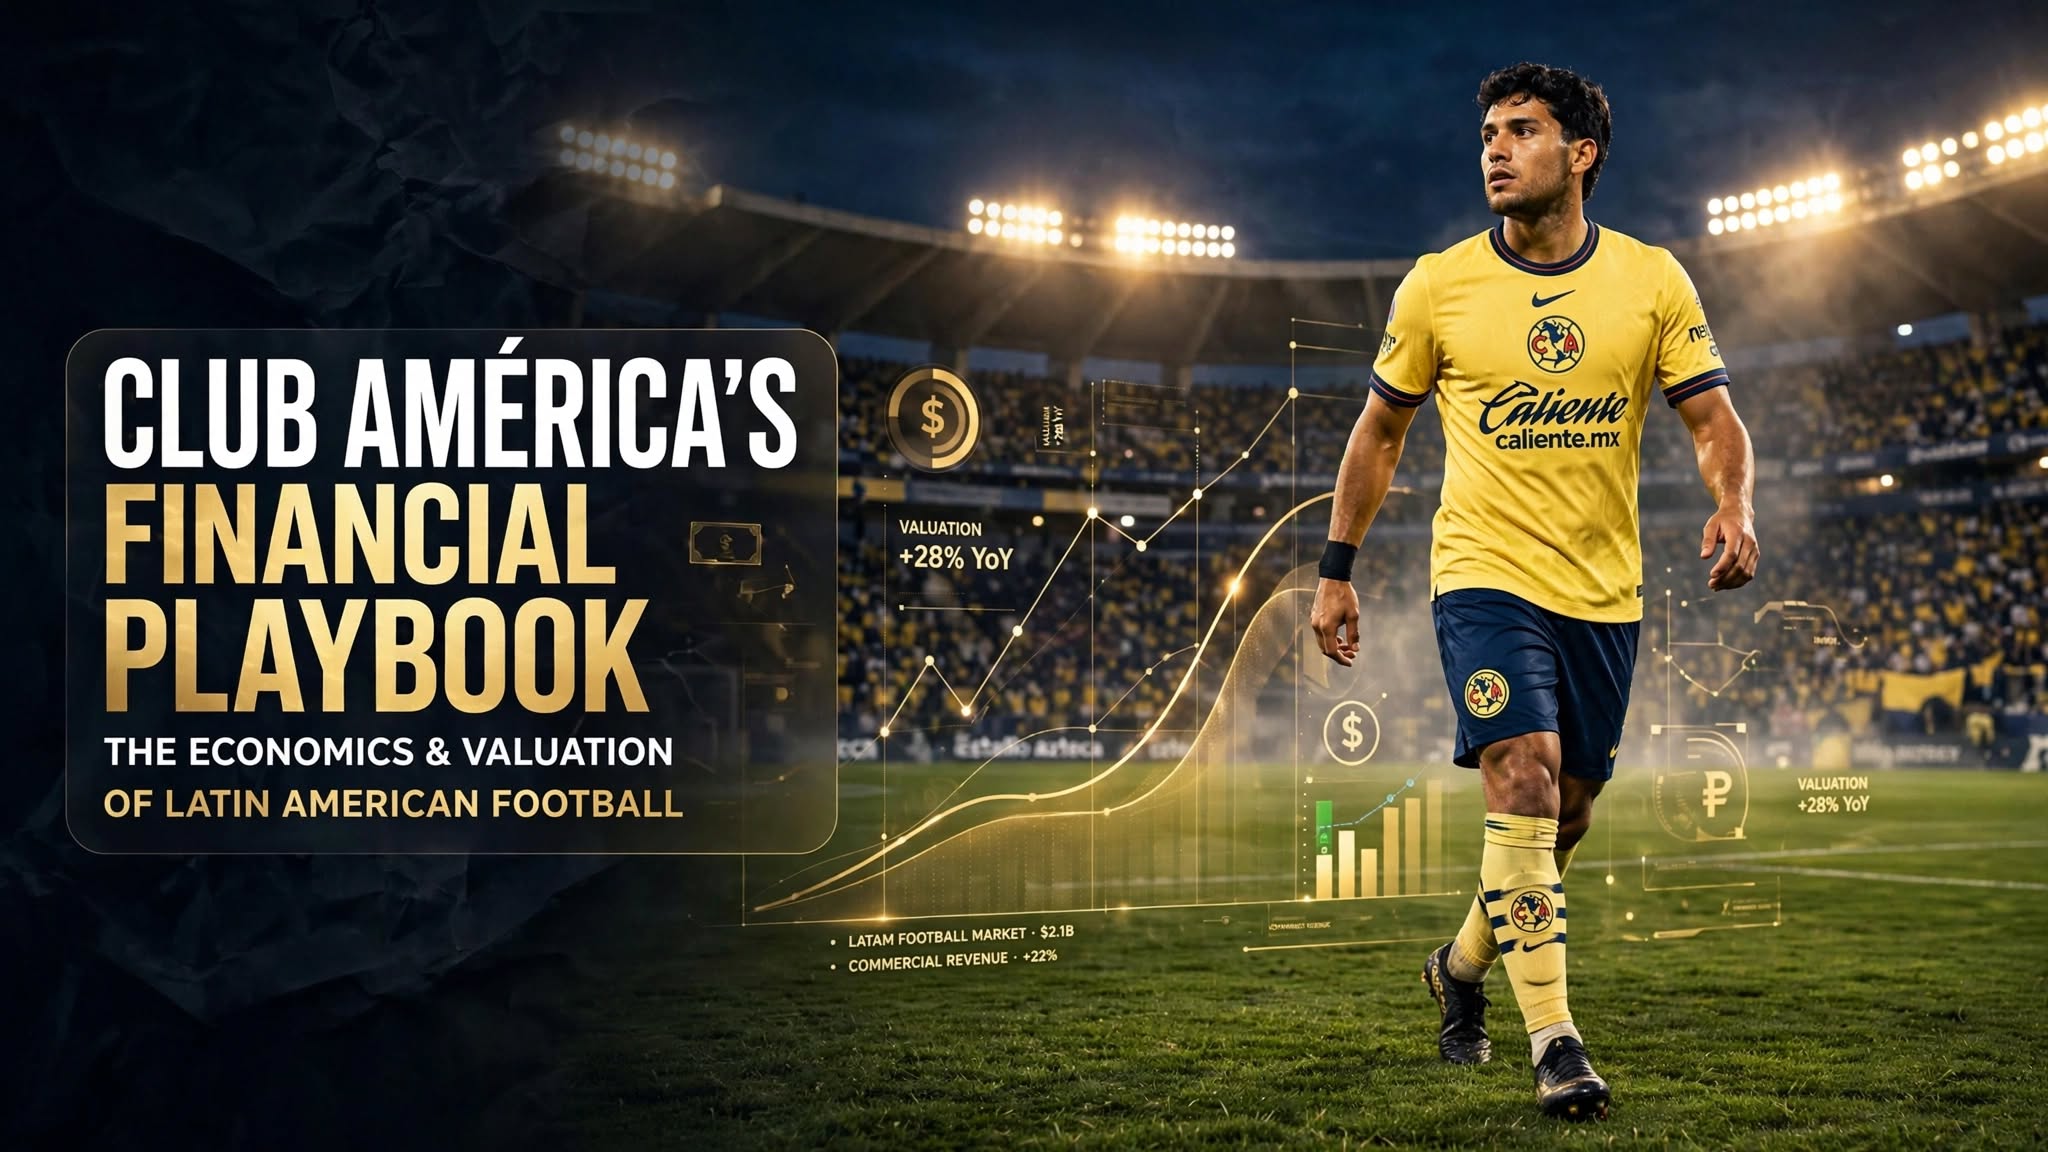
While most World Cup coverage focuses on stadiums and squads, the more consequential story in Mexican football has been playing out in enterprise-value deal structures. In late 2025, American investors closed a $490 million enterprise-value transaction for stakes in Club América and Mexico City’s iconic Azteca Stadium — a deal that, alongside a broader wave of U.S. capital entering Liga MX, reveals exactly how Latin American football is being financially re-architected just months before Mexico co-hosts the 2026 FIFA World Cup.
The Deal: Grupo Águilas and the $490 Million Structure
The transaction, announced in a joint statement to the Bolsa Mexicana de Valores (Mexico’s stock exchange), created a new holding entity called Grupo Águilas to own both Águilas del América and the 88,000-seat Estadio Azteca (rebranded Banorte Stadium), along with adjacent land, according to City A.M.’s reporting. The ownership structure splits 51% to Ollamani Group — controlled by former media tycoon Emilio Azcárraga Jean, who becomes Grupo Águilas’ executive president — and 49% to General Atlantic, the U.S. growth equity firm.
The deal’s most distinctive feature is its data and analytics component: Grupo Águilas engaged Kraft Analytics Group, a firm controlled by the owners of the NFL’s New England Patriots, specifically to support fan engagement and data analytics for the new entity, according to City A.M. — an explicit transfer of NFL-style commercial infrastructure into Mexican football operations.
Club América/Azteca deal structure:
| Element | Detail |
|---|---|
| Total enterprise value | $490 million |
| New holding entity | Grupo Águilas |
| Ollamani Group stake | 51% (Emilio Azcárraga Jean, executive president) |
| General Atlantic stake | 49% |
| Assets included | Águilas del América + Estadio Azteca (88,000 capacity) + adjacent land |
| Analytics partner | Kraft Analytics Group (New England Patriots ownership) |
| Club América standalone valuation | ~$770 million |
Why América Specifically: The Numbers Behind the Richest Club in Mexico
Club América’s standalone valuation of roughly $770 million, a figure that rivals mid-tier European clubs, makes it the most valuable soccer team in Mexico by a wide margin, according to reporting on the broader Liga MX investment wave. That scale advantage matters directly to the deal economics: América’s market value alone justifies a substantial share of the $490 million enterprise price even before accounting for the Azteca Stadium asset itself, one of the most recognizable sports venues in the world and a confirmed host site for the 2026 World Cup.
The Broader Pattern: American Capital’s Liga MX Land Grab
The Club América deal is the highest-profile example of a much wider trend. According to Front Office Sports, Querétaro became Liga MX’s first club with majority U.S. ownership when it was purchased by an American capital group for just over $120 million — a price point specifically attractive to investors because, as Querétaro investor Spiegel told FOS, “a lot of the leagues in Europe are more mature… you can’t expect that you will be able to increase revenue quickly by 30% to 50%,” whereas Mexican clubs remain underpriced relative to their audience scale.
Recent U.S.-linked Liga MX investment activity:
| Club | Investor Type | Deal Notes |
|---|---|---|
| Club América / Azteca Stadium | Growth equity + media (General Atlantic, Ollamani) | $490M enterprise value |
| Querétaro | American capital group | ~$120M; first majority US-owned Liga MX club |
| Necaxa | Celebrity investor group | Half-stake; modeled on Wrexham |
| Atlético San Luis | Buyout firm (via Atlético Madrid parent deal) | Acquired as part of broader Atlético Madrid transaction |
Why Liga MX, and Why Now
Three structural factors explain the timing of this capital influx. First, viewership: Liga MX is already one of the two most-watched soccer leagues in the United States alongside the English Premier League, with matches routinely drawing hundreds of thousands more viewers than MLS games and audiences that can swell into the millions for marquee fixtures, according to Front Office Sports. An Interticket study found the average Liga MX TV audience for a 2026 Clausura regular-season game reached 687,000 — comfortably ahead of NBC’s reported average Premier League audience of 510,000 in the same period, per ESPN’s reporting.
Second, the 2026 FIFA World Cup itself. Mexico is hosting 13 of the tournament’s 104 games across stadiums in Mexico City, Monterrey, and Guadalajara — the country’s first time on football’s biggest stage in 40 years — and figures within Mexican football believe the tournament will meaningfully raise the sport’s global commercial profile, according to Front Office Sports.
Third, structural governance reform. Liga MX is bound by a Court of Arbitration for Sport ruling requiring the return of promotion and relegation beginning with the 2026-27 season, according to ESPN. Sources told ESPN that outright relegation is unlikely to return in its traditional form; instead, the league is expected to expand the first division by promoting two teams from the second-tier Liga de Expansión and then permanently eliminate relegation going forward — a structure that would functionally mirror the closed, relegation-free model American investors are already familiar with from MLS, reducing downside risk for exactly the kind of capital now entering the league.
The Revenue Model Gap: Fragmented Rights, Unrealized Upside
Despite Liga MX’s viewership strength, its commercial infrastructure remains notably underdeveloped relative to its audience. TelevisaUnivision, which holds the bulk of U.S. broadcast rights, markets Liga MX as “the most-watched club soccer league in the country, regardless of language” — yet there is no single league-wide broadcast partner, with individual clubs instead negotiating separate rights deals, creating what ESPN describes as “a fragmented landscape for viewers.” Grupo Orlegi’s Alejandro Irarragorri told Front Office Sports that centralizing those rights would let Liga MX sell overseas coverage collectively rather than club-by-club — currently near-impossible outside the U.S. because no single club carries enough international fan base to interest overseas broadcasters on its own. The English Premier League’s 2022 milestone of earning more from overseas rights than domestic ones is the explicit long-term comparison being drawn.
Final Verdict
Club América’s $490 million enterprise-value transaction is best read as the clearest evidence yet that American investors view Mexican football the way private equity viewed European mid-tier clubs a decade ago: a market with Premier League-caliber viewership numbers, World Cup-driven momentum, and valuations that remain a fraction of comparable European assets. The addition of NFL-grade analytics infrastructure via Kraft Analytics Group, alongside the league’s looming governance shift toward a closed, relegation-light structure, signals that this is a bet on operational Americanization of Liga MX’s business model, not just a passive financial stake. The unresolved variable is media-rights centralization — until Liga MX clubs coordinate broadcast rights the way the Premier League does, the league’s valuation upside relative to its audience size will likely remain only partially realized, which is precisely the inefficiency the current wave of American capital appears to be betting it can help fix.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
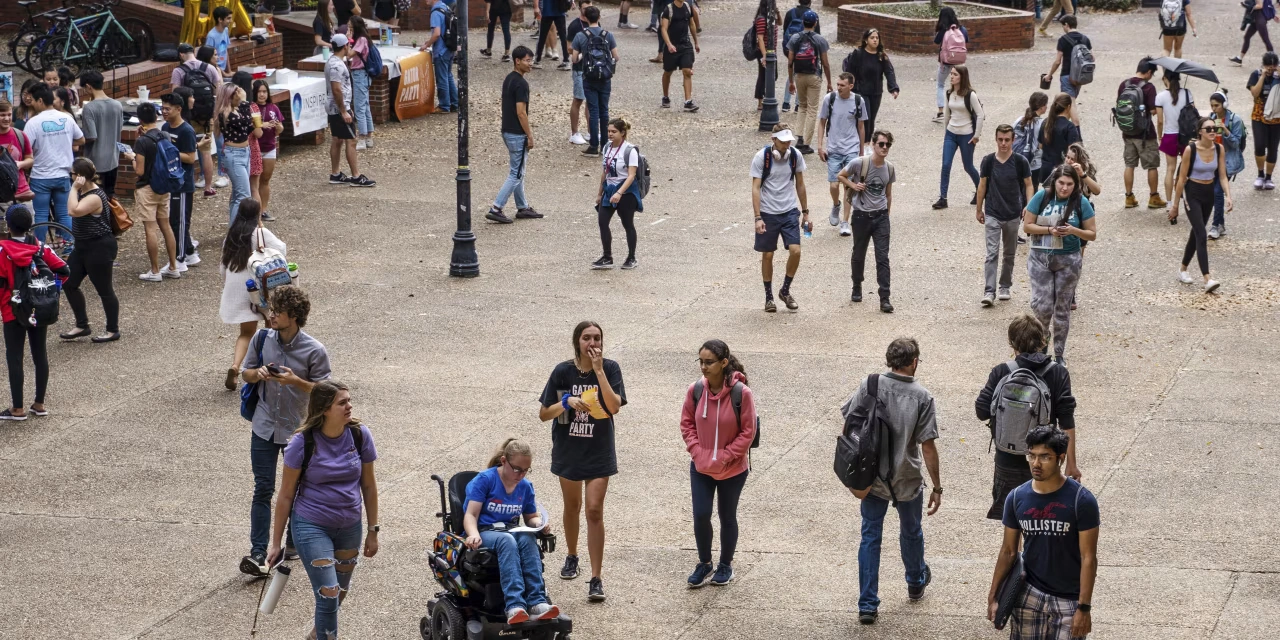
Federal student loan defaults are climbing sharply once more, with new data showing millions of borrowers slipping into default status as the last remnants of pandemic-era protections disappear. The numbers paint a troubling picture for household finances at a moment when many Americans are already grappling with elevated borrowing costs.
The Numbers Behind the Surge
According to the Federal Reserve Bank of New York, roughly 2.6 million additional federal student loan borrowers had their loans transferred to the Department of Education’s Default Resolution Group during the first quarter of 2026 alone. That follows roughly 1 million defaults recorded in late 2025, suggesting the pace of new defaults is accelerating rather than leveling off.
A Liberty Street Economics analysis tied to the data found that the average newly defaulted borrower is nearly 39 years old — notably not a young, recent graduate, but someone further along in their career. Many of these borrowers were current on their loans before the pandemic-era payment pause began back in 2020, underscoring how disruptive the return to normal repayment has been even for previously reliable borrowers.
The Credit Score Hit
The financial damage extends well beyond the loans themselves. Borrowers who default see their credit scores drop by an average of 91 points — a steep decline that can affect everything from their ability to rent an apartment to the interest rates they’re offered on car loans, credit cards, and mortgages going forward.
Collections Are Paused — For Now
There is a temporary reprieve: collections on defaulted federal student loans are currently paused. But that pause is not guaranteed to last. Once collections resume, affected borrowers could face wage garnishment, seizure of tax refunds, and offsets against federal benefits — consequences that could compound an already difficult financial position for millions of households.
A Broader Affordability Squeeze
The default wave is unfolding alongside other affordability pressures. Mortgage rates have moved sharply higher in recent weeks, with the 30-year fixed rate climbing to 6.92% for the week ending May 22, up from 6.71% just two weeks earlier. That increase has pushed a growing share of buyers toward adjustable-rate mortgages, which carry lower introductory rates but reset based on future market conditions — a trade-off that could create fresh financial strain if rates remain elevated.
What It Means for Borrowers
For the millions of borrowers now in default, the message from financial experts is consistent: defaulting on a federal student loan carries serious, long-lasting consequences, and the current pause on collections should be treated as a window to seek resolution options rather than a reason for complacency.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
Analysis
Indonesia’s Danantara Shifts to Investment Phase, Targets 7% Returns — Sovereign Wealth Fund Enters Deployment Era Under Prabowo’s Ambitious Vision
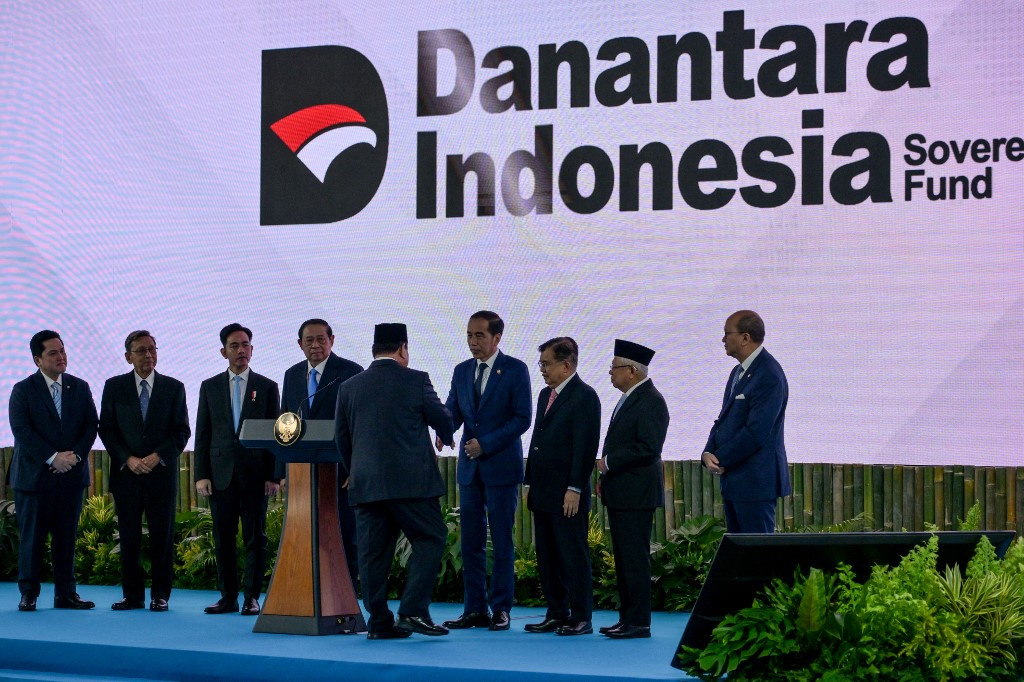
The morning light over Jakarta’s financial district has a way of making ambition look achievable. In the gleaming corridors of the Danantara Indonesia headquarters — a building that barely existed eighteen months ago — a quiet but consequential shift is underway. The sovereign wealth fund that President Prabowo Subianto unveiled with enormous fanfare in February 2025 has spent its inaugural year doing something unglamorous but essential: building the institutional scaffolding that separates a serious fund from a political showpiece. Now, as Indonesia’s Danantara sovereign wealth fund enters its investment phase in 2026, the real examination begins.
At the World Economic Forum in Davos in January, Chief Investment Officer Pandu Patria Sjahrir declared that Danantara’s target for investment fund placements in 2026 is set at $14 billion — nearly double the $8 billion allocated across all of 2025. Kompas The capital acceleration is not simply a number; it is a declaration of intent. The governance year is over. The deployment year has arrived.
Year One: The Governance Foundation Nobody Talks About
Before you can deploy capital at scale, you need systems that can be trusted with it. That is the unglamorous lesson Danantara absorbed in 2025. Chief executive Rosan Roeslani acknowledged that a primary achievement of the first year was breaking down the siloed operations that had long plagued Indonesia’s state-owned enterprises, promoting greater transparency and internal value creation. Jakarta Globe
BCA Chief Economist David Sumual confirmed the picture candidly: Danantara’s main focus in 2025 was internal consolidation — restructuring efforts, organizational improvements, and recruitment of human resources — with no major projects having fully materialized by year’s end despite SOE dividends being reallocated to the fund. Indonesia Business Post
That candour from a senior domestic economist is actually a constructive signal. Unlike the opaque early years of Abu Dhabi’s IPIC or the dangerously undisclosed operations of Malaysia’s 1MDB before its collapse, Danantara’s leaders are at least publicly acknowledging the gap between aspiration and execution. The first year served as a necessary stress-test of internal architecture. The critical question, now that the architecture is nominally in place, is whether the deployment year delivers the returns its political patron is demanding.
The 7% Return Mandate: Prabowo’s Public Challenge
Few sovereign wealth fund leaders have their performance targets set quite so publicly — or quite so politically — as Pandu Sjahrir now does. President Prabowo Subianto has publicly set a target of 7% return on assets for the fund, a mandate that Sjahrir acknowledged directly, saying Danantara would gladly accept the challenge as it “searches for projects that can give higher returns with the same impact while improving standards.” Jakarta Globe
The 7% ROA hurdle deserves context. Indonesia’s current state-owned enterprise portfolio has historically generated returns on assets hovering near 1.88% — a figure that reflects decades of sub-optimal capital allocation, political interference in pricing decisions, and chronic underinvestment in productivity. Reaching 7% is not an incremental improvement. It represents nearly a fourfold leap in capital efficiency across a portfolio of more than 1,000 SOEs.
To understand whether the target is reachable, consider how the world’s benchmark sovereign funds perform. Singapore’s Temasek Holdings has delivered annualised total shareholder return of approximately 7% in Singapore dollar terms over its 50-year history — but this was achieved with an entirely different governance architecture, strict commercial independence from government policy directives, and a portfolio heavily weighted toward liquid, globally diversified assets. GIC, Singapore’s other sovereign vehicle, targets real returns above 4% over 20-year rolling periods while managing over $770 billion. Abu Dhabi’s Mubadala, a closer model given its hybrid development-investment mandate, has generated returns in the 8–12% range in its best years, but only after a decade of portfolio maturation and institutional discipline-building.
What Danantara needs — quickly — is a portfolio mix that can bridge the gap between its politically derived SOE inheritance and the commercially rational returns its mandate demands.
Shifting to Deployment: Bonds, Equities, and the Capital Market Play
In a presentation at the Indonesia Stock Exchange, Pandu Sjahrir confirmed that Danantara would begin investing SOE dividend capital in both bonds and equities through the capital market starting in 2026, with the explicit additional goal of deepening Indonesia’s relatively shallow domestic capital markets. Kompas
This two-pronged strategy is tactically sound. Fixed-income instruments — particularly Indonesian government bonds (SBN) and SOE-issued corporate bonds — offer predictable yields in the 6–7% range at current rupiah interest rate levels, immediately competitive with the ROA target. The equities component introduces both upside potential and volatility, but also provides the market liquidity and price-discovery function that Indonesia’s IDX has lacked for years.
Economic observer Yanuar Rizky assessed that Danantara’s entry as a major institutional investor could have a positive stabilising effect on Indonesia’s capital markets, provided the fund maintains a clear distinction between commercial portfolio investment and politically motivated market support operations. Kompas That caveat is pointed. If Danantara begins purchasing equities to prop up falling SOE stock prices rather than to generate returns, it will quickly become both a market distortion mechanism and a fiscal liability.
Danantara is also considering taking a shareholder position in the Indonesia Stock Exchange itself through its demutualization process — a move that would simultaneously give the fund a structural role in market governance while diversifying its asset base into financial infrastructure. Kompas
The $14 Billion Deployment Pipeline: Sectors and Scale
The capital earmarked for 2026 will flow primarily from SOE dividends and will target sectors including renewable energy, energy transition, digital infrastructure, healthcare, and food security. Danantara is also evaluating opportunities beyond Indonesia’s borders — specifically in China, India, Japan, South Korea, and Europe — though domestic allocation remains the dominant priority. Asia Asset Management
Six major projects were scheduled for groundbreaking in February 2026 alone, including an aluminum smelter and smelter-grade alumina facility in Mempawah, West Kalimantan; a bioavtur production facility at the Cilacap Refinery in Central Java; a bioethanol plant in Banyuwangi, East Java; and salt factories in Gresik and Sampang designed to supply Indonesia’s chlor-alkali industrial base. Kompas Together, these projects form the visible edge of what Danantara describes as a $7 billion downstream industrialization push — Indonesia’s long-deferred attempt to stop exporting raw nickel, bauxite, and palm oil and start exporting processed value.
The downstream story matters enormously for return-on-assets arithmetic. A nickel laterite operation generates modest margins; a battery cathode facility or EV component manufacturer attached to that same ore base can generate returns in the 12–18% range at commercial scale. That is the logic threading through Danantara’s investment thesis — and it is the same logic that has made Indonesia’s nickel-to-battery downstream push a subject of intense interest among Japanese, South Korean, and European manufacturers watching their supply chains with growing anxiety.
CEO Rosan Roeslani has emphasized that 2026’s strategy is built on risk-managed deployment and long-horizon value creation, with investment screens tightened to ensure capital flows only to projects with clear commercial merit and measurable economic impact. GovMedia
Danantara vs. The World’s Great Sovereign Funds: A Benchmark Comparison
| Fund | AUM (approx.) | 10-Year Return | Independence Model | Primary Focus |
|---|---|---|---|---|
| Norway GPFG | $1.7 trillion | ~8.5% p.a. | Statutory independence | Global equities/bonds |
| Temasek (Singapore) | ~$300 billion | ~7% TSR | Operational independence | Asia equities |
| GIC (Singapore) | ~$770 billion | 4%+ real | Full professional management | Global diversified |
| Mubadala (Abu Dhabi) | ~$300 billion | 8–12% (peak) | Semi-commercial | Strategic/development |
| Khazanah (Malaysia) | ~$35 billion | Mixed | Political proximity | Domestic SOEs |
| Danantara (Indonesia) | ~$900 billion AUM | Target: 7% ROA | Political appointment-led | SOEs + strategic projects |
The table tells a revealing story. Danantara is already one of the largest sovereign vehicles on earth by nominal AUM — but AUM and investable capital are very different things when the underlying portfolio consists largely of SOE assets that are neither liquid nor independently valued. Norway’s Government Pension Fund Global can credibly report 8.5% annualised returns because its portfolio is marked to liquid global market prices daily. Danantara’s SOE assets are carried at book values that may significantly diverge from what arms-length buyers would actually pay.
This is not a fatal flaw — it is a governance design choice with profound implications for how the 7% target gets measured. If Danantara measures ROA against re-valued, market-based asset prices, the benchmark is genuinely demanding. If it measures against legacy book values, the headline number may look better while concealing underlying performance deterioration.
The Broader Economic Stakes: Indonesia’s Path Past the Middle-Income Trap
Danantara does not exist in isolation. It is the financial architecture beneath President Prabowo’s “Golden Indonesia 2045” vision — the aspiration to reach developed-nation status within a generation. The fund was explicitly designed to help accelerate the president’s target of 8% annual GDP growth by his term’s end in 2029, consolidating and streamlining SOE operations to unlock productivity gains that fragmented management had suppressed for decades. Fortune
Indonesia’s GDP per capita, currently around $5,000, needs to triple to reach developed-world thresholds. That requires sustained, compounding productivity improvements across agriculture, manufacturing, energy, and services simultaneously. Danantara — if it functions as designed — could accelerate this by directing capital toward infrastructure gaps, energy transition assets, and downstream industries that private markets have been too cautious or too short-sighted to finance at the required scale.
Prabowo’s pitch to American business leaders in Washington in February 2026 was explicit: all state-owned assets have been consolidated under Danantara to accelerate investment, and the fund will serve as a primary engine of Indonesia’s economic transformation. Jakarta Globe The geopolitical subtext was equally clear — Indonesia is positioning itself as a destination for capital diversifying away from Chinese concentration and seeking access to Southeast Asia’s 280 million-strong consumer middle class.
Pandu Sjahrir, speaking at the South China Morning Post’s China Conference: Southeast Asia 2026 in Jakarta in February, framed the geopolitical dimension directly: “In the new geopolitical world, every country and every leader uses sovereign wealth funds as a geopolitical tool,” while insisting that Danantara must operate for profit rather than politics. South China Morning Post The tension between those two imperatives — geopolitical instrument and commercially disciplined investor — defines Danantara’s central challenge, and is one that even mature funds like Mubadala have never fully resolved.
Risks, Scrutiny, and the 1MDB Shadow
No serious analysis of Danantara can avoid the governance concerns that have trailed the fund from its inception. Following Danantara’s inauguration, the Jakarta Composite Index fell 7.1%, driven by continuous foreign capital outflows of approximately $622.7 million — a market verdict on investor discomfort with the fund’s legal structure and oversight architecture. East Asia Forum
The concerns are structural, not merely perceptual. Indonesia’s national audit bodies — the Financial Audit Board (BPK), the Agency for Financial and Development Supervision (BPKP), and the Corruption Eradication Commission (KPK) — have limited ability to monitor Danantara’s managed assets. Audits can only be conducted upon request from the House of Representatives, creating an oversight model that is reactive rather than systematic. Wikipedia
Critics have pointed out that Danantara’s senior leadership emerged from political negotiation as much as merit selection — CEO Rosan Roeslani served as Prabowo’s campaign chief, while Pandu Sjahrir served as the campaign’s deputy treasurer. East Asia Forum These connections do not automatically disqualify either man — Temasek’s own senior officials maintain government proximity — but they demand an unusually clear demonstration of commercial independence before institutional investors will commit capital with confidence.
Economists have also flagged crowding-out risks: as Danantara absorbs SOE dividends and raises capital through bond instruments, private sector investment appetite may be compressed, particularly if Patriot Bond subscriptions divert capital that listed companies would otherwise have deployed for their own growth. Indonesia Business Post
The Patriot Bond programme itself has attracted commentary that is difficult to ignore. Financial analysts widely viewed the initiative — which raised over Rp50 trillion from Indonesia’s business elite — as carrying the implicit return of political goodwill rather than purely financial reward, describing it as a “loyalty test” for the nation’s conglomerates. Wikipedia These are not conditions under which a world-class sovereign fund typically operates.
Investor Outlook: What Global Capital Should Watch
For international investors, Danantara’s deployment year presents a calibrated opportunity set rather than a binary bet. The fund’s entry into Indonesia’s bond and equity markets will provide liquidity and potentially improve price discovery on SOE-linked assets that have historically been thinly traded. Indonesia’s sovereign bond yields — currently in the 6.8–7.2% range for 10-year instruments — already offer competitive real returns given the country’s current inflation trajectory, and Danantara’s institutional demand will provide additional market support.
The downstream projects represent a longer-dated opportunity. Investors with three-to-five-year horizons who gain exposure to Indonesia’s nickel-to-battery value chain — whether through listed SOEs, joint venture structures, or Danantara-linked project bonds — are positioning for a structural shift in global clean-energy supply chains. The risk is not the economics of the projects themselves; it is the execution timeline and the political discipline to resist using Danantara as a budget-substitute during fiscal pressures.
Danantara’s 2026 Corporate Work Plan, presented to the House of Representatives, emphasised that every investment must be “bankable and truly value-accretive” — a standard borrowed from the private equity lexicon that, if genuinely applied, would represent a meaningful departure from the historically political character of Indonesian SOE capital allocation. Danantara Indonesia
Whether that departure is real or rhetorical will become clear within the next eighteen months. The projects are breaking ground. The bonds are being issued. The capital is beginning to flow. And in a country of 280 million people sitting atop some of the world’s most valuable commodity and consumer market assets, the upside — if governance holds — is not 7%. It is considerably higher.
Prabowo’s fund has set the floor. The ceiling is a function of institutional integrity.
Conclusion: The Deployment Era Begins — And the Scrutiny Deepens
Indonesia’s Danantara sovereign wealth fund enters 2026 at an inflection point that will define its legacy for a generation. The governance infrastructure is nominally in place. The capital pipeline — $14 billion targeted for deployment this year — is the largest in the fund’s short history. The 7% return-on-assets mandate, set publicly by the president himself, is ambitious relative to current SOE performance baselines but achievable if capital is deployed into commercial-grade projects with rigorous discipline.
The fund’s peer group — Temasek, GIC, Mubadala, Norway’s GPFG — took years, sometimes decades, to earn the institutional credibility that translates into sustained performance. Danantara does not have that luxury of time. Indonesia’s growth aspirations are set on a compressed timeline, and the political expectations attached to this fund are enormous.
What sophisticated investors should watch: the actual returns posted in Danantara’s first audited annual report; the independence and credibility of whichever oversight mechanism emerges; the performance of the six downstream projects currently breaking ground; and whether the fund’s capital market activities in bonds and equities reflect commercial logic or political stabilization.
The fund carrying the weight of Indonesia’s Golden 2045 vision is now, at last, actively deploying. The test of whether Danantara becomes Southeast Asia’s defining sovereign fund — or its most cautionary tale — begins today.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Jennifer Garner’s Latest Projects: Business Ventures Beyond Hollywood

Horror Box Office Economics: ROI, Market Share and the 2026

Inside Pete Hegseth’s Pentagon Speech Requirements: Structural Reforms and Defense Strategy

Remembering Eliana Moreno: The Legacy of NBC LA’s “Eli in the Heli”

Rep. Thomas Massie’s Impeachment Push Against Pete Hegseth, Explained

Bloodhound Q50: Remembering the Tragic Loss of Chicago’s Rising Drill Star

iOS 27 Release Date & Siri AI: The Ultimate Tech News Guide for iPhone 18 Users

Club América’s Financial Playbook: The Economics and Valuation of Latin American Football

Best iPhone 18 Pro Max Cases: Premium Protection for Apple’s 2026 Flagship

Johnny Ray and Nicole Mississippi: Attala County Case Explained

2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover
Best iPhone 18 Pro Max Cases: Premium Protection for Apple’s 2026 Flagship

Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown
Remembering Eliana Moreno: The Legacy of NBC LA’s “Eli in the Heli”

2026 Midterms: How Democrats Are Competing in Deep-Red Senate Seats
Bloodhound Q50: Remembering the Tragic Loss of Chicago’s Rising Drill Star

RFK Jr. Confirmation Investigation 2026: Health Policy Fallout Explained

North American Tariff Standoff 2026: Supply Chain Guide
-

 Featured5 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Democracy5 years ago
Missing You! SPSC
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills