Analysis
Four Republicans Join Democrats in House Vote to Rein In Trump’s Iran War Powers

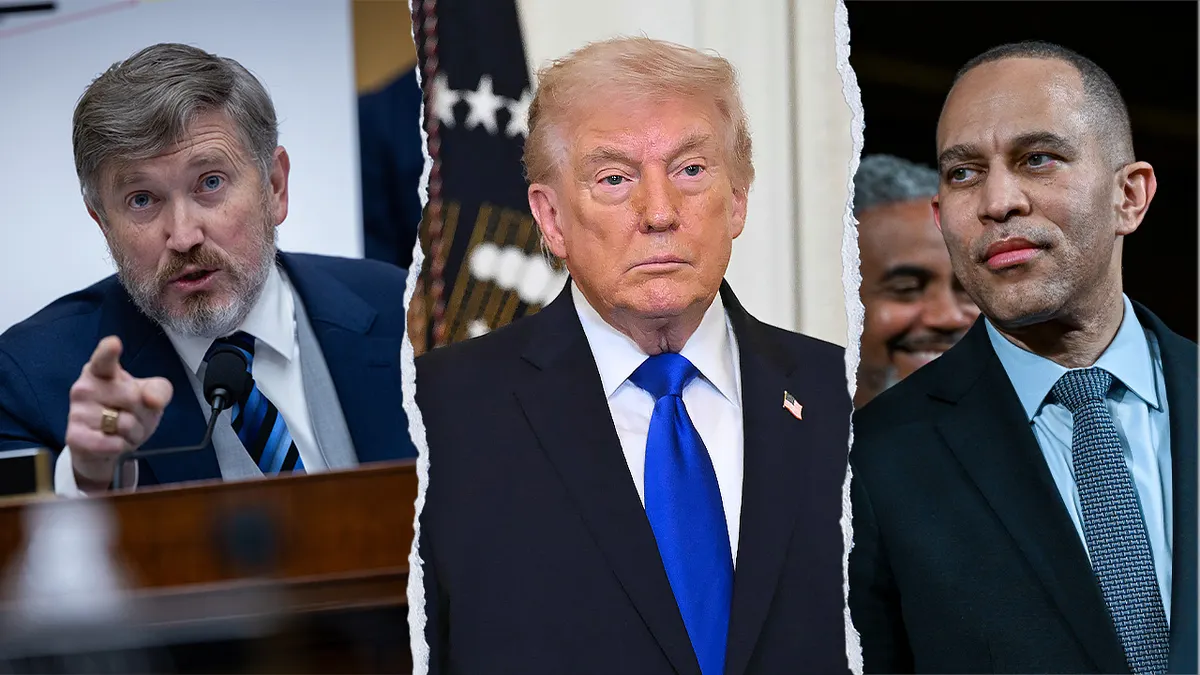
The U.S. House of Representatives delivered a rare bipartisan rebuke to President Donald Trump on Wednesday, passing a war powers resolution directing him to end U.S. military involvement in Iran unless Congress authorizes continued action. The vote was 215-208, with four Republicans crossing party lines to join all Democrats present.
This marked the first time the Republican-led chamber approved such a measure in four attempts since the conflict began on February 28 with U.S. and Israeli strikes. The resolution invokes the 1973 War Powers Resolution, which limits presidential military engagements without congressional approval beyond 60 days (plus a 30-day extension). That window has long passed.
The four Republicans—Thomas Massie of Kentucky, Brian Fitzpatrick of Pennsylvania, Tom Barrett of Michigan, and Warren Davidson of Ohio—bucked intense party pressure. Speaker Mike Johnson had previously delayed the vote when passage seemed likely. Cheers erupted on the Democratic side as the tally was announced. The measure now heads to the Senate, where its fate remains uncertain amid expected White House opposition.
Table of Contents
The Broader Landscape
The conflict, now in its fourth month, has reshaped U.S. politics and global energy markets. It began with strikes aimed at curbing Iran’s nuclear ambitions and regional influence but has stretched into a costly stalemate. Pentagon officials pegged direct military costs at around $25 billion by late April, with independent estimates suggesting the figure has climbed higher amid ongoing operations, munitions replenishment, and support costs.
Oil markets felt the shock immediately. Disruptions around the Strait of Hormuz sent Brent crude surging over 50% in the early weeks, contributing to higher U.S. gasoline prices and inflationary pressures. Economists have linked the war to measurable drags on consumer spending and business confidence, even as some supply routes adapted.
This vote arrives as public fatigue with open-ended conflicts grows. Previous attempts failed by razor-thin margins or procedural maneuvers. The shift reflects eroding GOP unity on Trump’s foreign policy approach, even within a slim majority.
The Core Development: What Happened and Why
House passes measure to rein in Trump’s Iran war powers as bipartisan frustration boils over.
The resolution directs the president to remove U.S. armed forces from hostilities with Iran absent explicit congressional authorization. It carries no immediate legal force to compel withdrawal—Trump would almost certainly veto any binding version—but it signals deepening institutional resistance.
Rep. Tom Barrett, a former Army helicopter pilot, justified his vote by emphasizing Congress’s constitutional role: “Congress alone declares war.” Fitzpatrick, Massie, and Davidson echoed concerns over unchecked executive power and the war’s open-ended costs. Massie has opposed the conflict consistently across attempts.
Democrats framed the effort as restoring constitutional balance. The administration maintains the actions fall within the president’s commander-in-chief authority and that initial notifications satisfied War Powers requirements. Yet repeated attempts to force a vote, and the eventual success, reveal cracks in that defense.
The 215-208 tally included near-unanimous Democratic support, including a shift from Rep. Jared Golden of Maine, who had opposed earlier versions. On the Republican side, most held firm, but the four defectors proved decisive. This wasn’t a sudden realignment. Earlier procedural votes and Senate advances had telegraphed growing unease.
Analytical Layer: Congressional Pushback and Constitutional Tensions
Bipartisan rebuke highlights war powers debate amid Iran’s conflict.
Why does this matter beyond symbolism? The 1973 War Powers Resolution emerged from Vietnam-era frustrations over presidential overreach. Presidents of both parties have often treated it as advisory rather than binding, arguing it infringes on Article II powers. Yet Congress retains the power of the purse and public pressure tools.
This vote captures a structural tension: a president acting decisively against perceived threats versus lawmakers wary of another prolonged engagement without broad buy-in. The defecting Republicans represent different wings—libertarian (Massie), moderate (Fitzpatrick), and others focused on fiscal restraint and oversight.
How does this vote affect Trump’s authority in the Iran conflict? In the short term, minimally. The resolution is concurrent and non-binding in a way that forces immediate action. Trump has dismissed similar efforts as unconstitutional. However, it complicates diplomacy, signals to allies and adversaries that U.S. domestic support is fraying, and adds political friction as midterm considerations loom. A sustained Senate push could force more negotiations or adjustments in tempo.
The picture is more complicated than simple partisanship. Some Republicans worry the war has depleted munitions stocks needed for other priorities, strained alliances, and diverted attention from domestic issues. Economic ripple effects—elevated energy costs hitting households—have amplified voter discontent.
Implications & Second-Order Effects
The vote amplifies pressure on the administration to wind down operations or secure clearer congressional backing. Markets may interpret it as a step toward de-escalation, potentially easing some risk premiums in oil futures, though volatility remains high. Businesses with exposure to energy or defense supply chains face uncertainty.
For U.S. service members and their families, prolonged uncertainty carries human costs. The conflict has already claimed American lives and required significant deployments. Second-order effects include strained readiness for other theaters and questions about long-term veteran care burdens.
Internationally, the rebuke could embolden Iranian hardliners or complicate negotiations. Allies watching U.S. political divisions may hedge their own commitments. Domestically, it feeds narratives of executive overreach on one side and congressional weakness on the other. With costs mounting—estimates of broader economic impacts in the hundreds of billions when factoring indirect effects—the fiscal drag could influence budget fights and voter sentiment heading into future elections.
Yet the resolution’s limits are clear. Without veto-proof majorities or spending restrictions, Trump retains significant latitude. What follows, however, is a test of whether this symbolic stand evolves into tangible constraints.
Competing Perspectives
Republican leadership and Trump allies argue the measure weakens America’s negotiating position and emboldens adversaries. Speaker Johnson warned it would tie the president’s hands at a critical moment. The administration points to Iran’s nuclear program, proxy activities, and direct threats as justification for swift action without prolonged debate.
Critics of the resolution, including many GOP members, contend that tying the commander-in-chief’s hands mid-conflict risks operational failures and sends mixed signals. They view the four defectors as outliers whose votes prioritize abstract constitutionalism over practical security needs. Massie’s primary loss to a Trump-backed challenger earlier highlights the political risks for dissenters.
Supporters counter that endless presidential wars erode democratic accountability. The Constitution assigns war declaration to Congress for good reason, they say. Fitzpatrick and Barrett, both with military backgrounds, framed their votes as upholding institutional balance rather than opposing the initial aims. This steel-manning acknowledges legitimate security threats while insisting on shared responsibility for their prosecution.
The divide reflects deeper fault lines: unilateral executive action versus deliberative legislative involvement. Both sides claim patriotism; both cite history. The reality is that sustained military campaigns without broad consensus carry legitimacy risks regardless of legal interpretations.
The House’s vote crystallizes a central tension in American governance: how a republic wages war in an era of rapid threats and polarized institutions. Four Republicans standing with Democrats won’t end the conflict tomorrow, but it registers accumulating costs—financial, constitutional, and political—that the administration can no longer ignore entirely. In Washington, such signals sometimes precede harder reckonings.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


For six years, the USMCA functioned as a predictable backstop for North American supply chains — a rare constant through a volatile trade era. That predictability ended on July 1, 2026. The United States Trade Representative confirmed it would not agree to renew the USMCA in its current form following the agreement’s mandatory six-year joint review, and by September, the standoff had escalated sharply: new Section 338 tariffs on Canadian goods, a doubling of steel and aluminum duties, and stalled Canada-US talks, even as Mexico continued active, if difficult, bilateral negotiations. For supply chain executives, the question is no longer whether North American trade rules will change — it is how fast, and which sourcing models survive the transition.
Key Takeaways
- The USTR announced on July 1, 2026 that it would not renew the USMCA in its current form, following the agreement’s mandatory six-year joint review — though the agreement remains legally in force while negotiations continue, and full withdrawal by any party would take six months to take effect.
- New Section 338 tariffs on Canada-origin goods took effect August 19, 2026 at a 50% ad valorem duty, applying even where USMCA duty-free status would otherwise apply, following the collapse of a September round of Canada-US talks.
- An estimated 85% of Mexican exports to the US remain USMCA-compliant and exempt from newer tariff actions, including a Section 301 forced-labor enforcement action covering 60 economies — while Canada has not opened formal, text-based bilateral negotiations tied to the review at all.
- The central unresolved dispute with Mexico is automotive content requirements: Washington is seeking a 50% US-specific content threshold for vehicles to qualify for preferential USMCA access, which Mexico is resisting and has linked to relief from existing Section 232 tariffs on autos (25%) and steel/aluminum (50%).
- Despite the tariff escalation, nearly 60% of goods imported from Canada and Mexico continue to enter the US duty-free, underscoring that North American trade disruption in 2026 remains targeted and negotiated rather than a wholesale breakdown of integration.
How the Standoff Reached This Point
The current confrontation traces back through a specific legal and political sequence. After the US Supreme Court struck down IEEPA-based tariffs in February 2026, the administration pivoted to alternative legal authorities: a 10% tariff on Canada and Mexico under Section 122 of the Trade Act of 1974 (with an exemption maintained for USMCA-compliant goods), alongside a separate, unaffected 25% tariff on Canadian and Mexican steel, aluminum, and certain auto products under Section 232 of the Trade Expansion Act of 1962 — subsequently raised to 50% for steel and aluminum.
The USMCA’s mandatory six-year joint review, triggered by a provision written into the original 2020 agreement, then became the vehicle for a more fundamental renegotiation push. On July 1, 2026, the USTR confirmed it would not renew the agreement in its current form, citing purported shortcomings and ongoing trade deficits with both neighbors. Crucially, this announcement did not terminate the agreement or preferential trade — the USMCA remains in force while the three governments work through the issues raised, and any formal withdrawal by a party would not take effect for six months, a design feature intended to preserve negotiation leverage without triggering an immediate supply chain shock.
The situation escalated further by September: the US deployed the rarely used Section 338 tariff authority against Canada specifically, roughly doubling existing steel and aluminum rates and reintroducing tariffs from a zero baseline across a much wider set of Canadian goods, after a round of talks collapsed. Canada, notably, has not yet opened a substantive, text-based bilateral negotiating round tied to the joint review itself, unlike Mexico — engagement has remained largely at the ministerial-call level between Canada’s Trade Minister and the US Trade Representative.
The Two-Track Negotiation: Mexico vs. Canada
A critical, underappreciated fact for 2026 supply chain planning is that the US is running genuinely different negotiating tracks with its two USMCA partners:
Mexico has completed two full bilateral negotiating rounds covering automotive rules of origin, steel and aluminum, economic security, industrial goods, agriculture, labor, environmental standards, and regulatory compatibility. The core sticking point remains automotive content: Washington’s push for a 50% US-specific content requirement (versus the current North American-content framework) is being actively resisted by Mexico, which has explicitly linked any concessions to relief from existing Section 232 auto and metals tariffs. Mexican officials have noted that a separate Section 301 forced-labor enforcement action covering 60 economies produces no practical change for Mexican exporters specifically, since USMCA-compliant goods — an estimated 85% of Mexico’s US-bound exports — remain exempt as long as rules-of-origin requirements are satisfied.
Canada, by contrast, has not begun formal bilateral negotiations tied to the review at all, and its position has deteriorated sharply since July 1: the September Section 338 action roughly doubled steel and aluminum rates and reintroduced tariffs across a substantially broader set of goods from a zero baseline, representing the most significant escalation in the relationship since the review began.
What This Means for Supply Chain Restructuring
Rules of Origin Are Now a Live Compliance Risk, Not a Static Baseline
With automotive content requirements under active renegotiation and other sectors facing scrutiny, businesses that have treated USMCA rules-of-origin qualification as a fixed, one-time certification exercise face material risk. A targeted change to a single rule of origin, tariff classification, or certification requirement can affect thousands of suppliers and shipments across an integrated production network simultaneously — meaning sourcing and logistics models that currently qualify for preferential treatment may not continue to qualify under a revised framework, even without any change to the physical supply chain itself.
Mexico Remains the More Stable Near-Term Sourcing Base
Given Mexico’s active, structured bilateral negotiation track and the 85% USMCA-compliance exemption rate for its exports, Mexico currently presents a comparatively more predictable near-term sourcing environment than Canada, where the absence of formal negotiations combined with the September escalation has introduced acute uncertainty. This is a reversal of the historical assumption that Canada — as the more institutionally aligned partner — represents lower trade-policy risk.
Automotive and Metals-Intensive Supply Chains Face the Sharpest Exposure
The unresolved automotive content dispute with Mexico and the doubled steel/aluminum tariffs on Canada concentrate risk specifically in vehicle manufacturing, auto parts, and any metals-intensive industrial supply chain — sectors where BCG’s analysis has noted that tariff costs, layered onto supply disruption, could threaten the survival of some auto and auto parts companies, with downstream effects on retail prices, annual vehicle sales, and industry employment.
The Duty-Free Baseline Still Holds — For Now
The single most important stabilizing fact for supply chain planning is that nearly 60% of goods imported from Canada and Mexico continue to enter the US duty-free despite the standoff, and full treaty withdrawal by any party remains widely viewed as unlikely given the depth of North American supply chain integration and the six-month withdrawal notice period built into the agreement’s design. This suggests businesses should plan for continued negotiation-driven volatility in specific sectors (autos, steel, aluminum) rather than a wholesale collapse of North American trade preference.
Supply Chain Restructuring Strategies for 2026–2027
- Segment supplier risk by rules-of-origin sensitivity, not just by country. A supplier whose qualification depends on automotive content thresholds under active renegotiation carries fundamentally different risk than one in a sector untouched by the current disputes.
- Build contractual flexibility into sourcing agreements for tariff-classification changes. Given that thousands of suppliers can be affected by a single rule change, procurement contracts should include tariff-exposure adjustment mechanisms rather than assuming static classification.
- Treat Canada-sourced steel, aluminum, and metals-intensive inputs as higher near-term risk than comparable Mexican inputs, given the divergent negotiation tracks and the September escalation specifically targeting Canadian goods.
- Monitor the Section 232 auto tariff–content requirement linkage closely. Mexico’s explicit linking of content-rule concessions to Section 232 relief means any resolution is likely to arrive as a package, not sector by sector — businesses should model scenarios for both continued impasse and a bundled resolution.
- Avoid over-reacting to headline tariff announcements without checking USMCA-compliance exemption status. With roughly 85% of Mexican exports and 60% of combined Canada-Mexico imports still qualifying for duty-free treatment, the practical tariff exposure for a specific supply chain often differs substantially from the headline rate.
Frequently Asked Questions
Is the USMCA ending in 2026?
No. The USTR declined to renew the USMCA in its current form as of July 1, 2026, but the agreement remains legally in force while negotiations continue; a formal withdrawal by any party would take six months to take effect and is considered unlikely given deep supply chain integration.
How are US tariffs on Canada different from tariffs on Mexico in 2026?
Canada faces a more severe and less negotiated situation: new Section 338 tariffs took effect in August 2026 at 50% on certain goods, talks collapsed in September, and Canada has not opened formal bilateral negotiations. Mexico has completed two full bilateral negotiating rounds, and roughly 85% of its US-bound exports remain USMCA-compliant and tariff-exempt.
What is the main unresolved issue in the USMCA renegotiation with Mexico?
Automotive content requirements — the US is seeking a 50% US-specific content threshold for vehicles to qualify for preferential access, which Mexico is resisting and has linked to relief from existing steel, aluminum, and auto tariffs.
Conclusion
The 2026 North American tariff standoff is best understood not as a collapse of continental trade integration but as a genuine, high-stakes renegotiation running on two very different tracks — a structured, if difficult, Mexico process and a stalled, escalating Canada process. With nearly 60% of Canada-Mexico imports still entering the US duty-free and full treaty withdrawal remaining a low-probability outcome, the practical task for supply chain leaders is precision: distinguishing which specific inputs, sectors, and supplier relationships carry genuine renegotiation risk from the broader base of trade that remains, for now, stable.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
With the November 3, 2026 midterm elections roughly two months away, multiple independent forecasting models are converging on a similar conclusion: Democrats are currently favored to retake control of the U.S. House of Representatives, though the size of any majority — and control of the Senate — remains genuinely uncertain.
This piece breaks down what the leading models actually say, why historical patterns favor the out-of-power party in midterms, and which structural factors could still complicate a Democratic pickup.
The Current Numbers
Heading into the cycle, Republicans hold a narrow 218-seat majority, with Democrats at 212 seats and several vacancies. Because of that narrow margin, Democrats need to flip only a small net number of seats — commonly cited as roughly three to six, depending on how upcoming special elections in safely Democratic vacant seats resolve — to reclaim the majority.
Several independent models have published 2026 House projections:
- A Cornell University-based academic forecasting team, presenting at the American Political Science Association’s annual meeting, projects Democrats winning approximately 226 seats to Republicans’ 209, with simulations showing a plausible range as wide as 206 to 258 Democratic seats.
- A separate independent forecasting outlet (FiftyPlusOne) gives Democrats an 85% probability of winning the House majority, with a median projected outcome of 230 seats, and a national House popular-vote margin estimated at roughly +7 points for Democrats.
- Aggregator and prediction-market platforms tracking the race show a broadly consistent picture: Democrats favored, with meaningful — not negligible — uncertainty remaining.
Researchers behind the Cornell model were notably direct about what it would take for the forecast to be wrong: given the model’s historical accuracy, a Republican House majority holding would likely mean “either everything has gone their way or something unprecedented has happened.”
Why History Favors Democrats Structurally
Election forecasters lean heavily on one of the most consistent patterns in American politics: the president’s party almost always loses House seats in midterm elections.
- Looking back across 36 midterm elections since 1882, the White House party avoided losing a net of at least three seats in only four of them — 1934, 1962, 1998, and 2002 — each occurring under unusual circumstances (the Great Depression recovery, the Cuban Missile Crisis aftermath, post-9/11 unity, and the Clinton impeachment backlash, respectively).
- Democrats need a uniform national swing of roughly 1.1% from the 2024 House results to flip control — a relatively low bar by historical standards.
- Special elections held throughout 2025 provide an early, concrete signal: across roughly 31 state legislative and House special elections, Democratic candidates outperformed the 2024 presidential ticket’s vote share by an average of 15.4 points (median 13 points) — more than ten times the swing needed to flip the House.
The Redistricting Wildcard
No 2026 forecast is complete without accounting for the unusual mid-decade redistricting activity that has reshaped the House map since the 2024 election. Aggressive redistricting in several Republican-controlled states has given the GOP additional structural insulation heading into this cycle — a countervailing force against the historical midterm pattern and the favorable special-election trendline described above. This is the central tension every current model is trying to price in: strong Democratic generic political environment signals, against a map that has been deliberately reshaped to blunt exactly that kind of environment.
The GOP Counter-Strategy
Republican strategists are not treating the historical pattern as inevitable. Key elements of the party’s defensive posture include:
- Leaning on redistricting gains in states where new maps have already been implemented, effectively “banking” seats that would otherwise be more competitive under prior district lines.
- Fundraising and turnout operations targeted specifically at the small number of genuinely competitive districts where the national environment is expected to matter most.
- Nationalizing the midterm around specific policy contrasts rather than running on incumbency alone, given that broad “stay the course” messaging tends to perform poorly for an incumbent president’s party in a midterm.
What Swing Districts Are Actually Deciding This
Rather than the national popular vote, the real decision point sits in a relatively small number of competitive districts — often those that saw redistricting changes, those with retiring incumbents, or historically split-ticket suburban seats. Readers tracking this race closely should watch:
- Districts with open seats created by incumbent retirements, which historically see larger swings than seats with incumbents running for reelection.
- Suburban districts that have trended away from the GOP in recent cycles, where the current generic-ballot environment would need to hold through November to matter.
- Newly redrawn districts in states where redistricting fights are still working through courts — some maps used in 2026 could still face late legal challenges.
What Competitors Are Missing
Much of the horserace coverage of this cycle reports the topline “Democrats favored” number without explaining why two structurally different forces — a strongly Democratic-leaning political environment on one hand, and an aggressively re-drawn map on the other — are pulling against each other simultaneously. That tension, not the headline probability number, is the actual story of the 2026 House cycle, and it’s why even a “85% favored” forecast still carries real uncertainty worth taking seriously rather than treating as a foregone conclusion.
Key Dates to Watch
- Ongoing — ballot access deadlines and any late redistricting litigation in contested states
- September–October 2026 — final pre-election generic ballot and fundraising disclosures
- November 3, 2026 — Election Day
- Early November 2026 — initial results; close districts may take days to certify
Q: Are Democrats favored to win the House in the 2026 midterms?
As of early September 2026, multiple independent forecasting models favor Democrats to win a U.S. House majority. One academic model projects roughly 226 Democratic seats to 209 Republican seats; another independent forecaster puts Democrats’ probability of winning the House at 85%, with a median projection of 230 seats. Republicans currently hold an 218-seat majority, and Democrats need only a small net seat gain to flip control.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
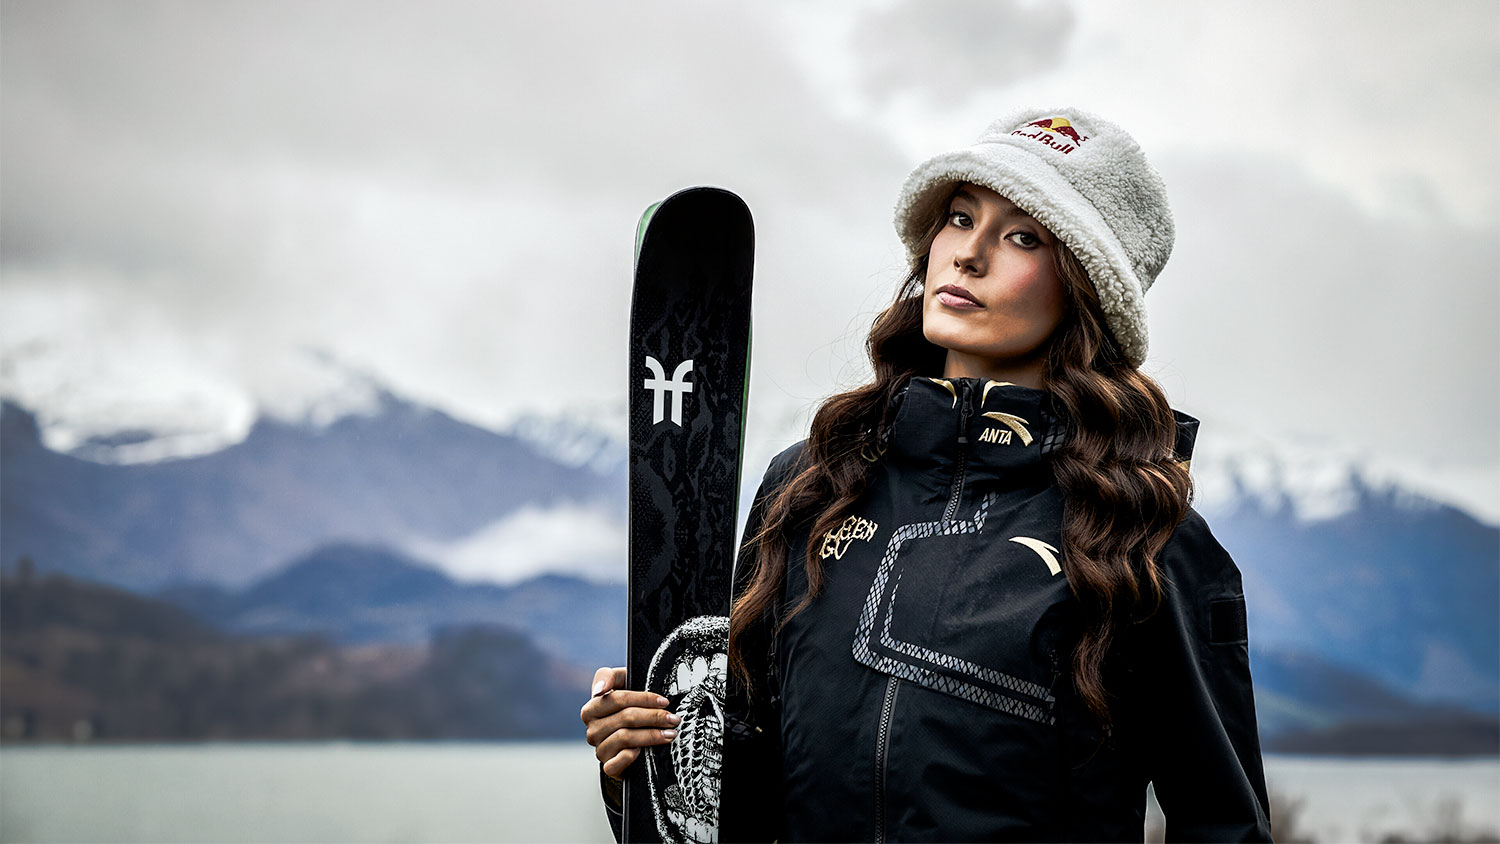
Six-time Olympic medalist Eileen Gu appeared on Jay Shetty’s “On Purpose” podcast (released August 31, 2026) to unpack the psychological framework behind her career, built around the mantra “train like I’ve never won and compete like I’ve never lost.” Off the slopes, Gu has parlayed her athletic profile into an estimated $50 million net worth, driven substantially by roughly $23.1 million in single-year endorsement earnings from brands including Louis Vuitton, Victoria’s Secret, Tiffany & Co., and Red Bull.
Eileen Gu: Career, Mindset & Brand at a Glance
| Metric | Figure |
|---|---|
| Total Olympic medals | 6 (across Beijing 2022 and Milano Cortina 2026) |
| Beijing 2022 medals | 2 gold, 1 silver |
| Milano Cortina 2026 medals | 1 gold, 2 silver |
| Estimated net worth (2026) | ~$50 million (Celebrity Net Worth, via Yahoo Sports) |
| Reported single-year endorsement earnings | ~$23.1 million (New York Times, cited 2025 figure) |
| Annual skiing prize-money earnings | Typically under $200,000 |
| Estimated annual endorsement income | $20 million+ |
| Age (as of 2026) | 22 |
| Education | Graduated Stanford University, June 2026 |
| Recent career move | Named Senior Associate at venture capital firm Benchmark |
| Major endorsement partners | Louis Vuitton, Victoria’s Secret (VS Collective founding member), Tiffany & Co., Red Bull, Porsche, IWC Schaffhausen, Fendi, Gucci |
| Modeling representation | Signed with IMG Models |
Sources: Jay Shetty’s “On Purpose” podcast (Aug. 31, 2026), Olympics.com, Yahoo Sports, Hello Magazine, and en.Tempo.co — all Feb.–Sept. 2026.
Deep Dive: The Psychology Behind the Podium, and the Business Behind the Brand
The Mantra, Unpacked: Why Two Contradictory Mindsets Coexist
Gu’s central framework — “train like I’ve never won and compete like I’ve never lost” — is deliberately built around psychological contradiction, and she’s been explicit in interviews about why that tension is the point rather than a flaw. In training, the “never won” half of the mantra keeps her in a self-critical, improvement-focused mindset regardless of past results, treating every practice session as though prior success carries no weight. In competition, the “never lost” half flips that entirely: total confidence, free of self-doubt, at the exact moment performance matters most. Gu has described competing with what she calls an “insatiable, almost obsessive, all-in mentality” — but she’s also cautioned that this intensity cannot be sustained indefinitely, which is precisely why she confines it to competition windows rather than treating it as a constant state.
“It’s Difficult to Win, But Way Harder to Stay There”
Gu has directly addressed the specific challenge of sustained excellence rather than a single peak performance, telling Shetty that so much changes for an athlete between ages 18 and 22 — the exact window spanning her Beijing 2022 and Milano Cortina 2026 Olympic appearances. Her framing treats her mantra not as a one-time psychological trick for a single competition, but as a sustainability mechanism: the “train like I’ve never won” half specifically functions to keep her hungry and prevent complacency across multiple competitive cycles, which she credits as the actual differentiator between athletes who win once and those who remain at the top over years.
“Evidence Over Affirmation”: A Distinct Confidence-Building Method
Beyond the headline mantra, Gu has described a related but distinct approach she calls “evidence over affirmation” — building competitive confidence from accumulated proof of capability (training data, prior performance, physical preparation) rather than from self-affirming statements alone. This is a meaningfully different psychological technique than generic positive self-talk: rather than telling herself she can succeed, her stated approach is to construct a body of concrete evidence through training that makes confidence a logical conclusion rather than a hopeful assertion. The distinction matters for anyone attempting to apply her framework outside elite sport — it suggests the actionable takeaway isn’t the affirmation itself, but the training rigor that generates evidence to draw confidence from.
The Business Reality: Endorsements Dwarf Competition Earnings by a Wide Margin
It’s worth being precise about where Gu’s wealth actually comes from, since the numbers are stark: her typical annual skiing prize money runs under $200,000, while her endorsement income has been reported at over $20 million annually and her single-year total endorsement earnings at approximately $23.1 million according to New York Times reporting. That roughly 100-to-1 ratio between competition earnings and endorsement income is not unusual among elite global athletes with strong commercial appeal, but it does mean that framing Gu primarily as a “skier who also does endorsements” inverts the actual economics of her career — the more accurate framing, financially speaking, is a global brand ambassador who also happens to compete at an elite level in freestyle skiing.
A Genuinely Diversified Brand Portfolio, Not a Single-Category Play
Gu’s endorsement portfolio spans several distinct commercial categories rather than concentrating in one lane: luxury fashion (Louis Vuitton, Fendi, Gucci, Tiffany & Co.), lingerie and lifestyle (as a founding member of Victoria’s Secret’s VS Collective, alongside athletes like Megan Rapinoe), automotive and performance brands (Porsche, Red Bull), luxury watches (IWC Schaffhausen), and a separate roster of China-market-specific partners including Bank of China, China Mobile, and Luckin Coffee. This category diversification is itself a deliberate brand-building strategy — it reduces Gu’s commercial dependence on any single industry’s marketing cycles or economic conditions, and positions her simultaneously in Western luxury markets and Chinese consumer markets, an unusually broad dual-market commercial footprint for an athlete her age.
The Pivot Into Venture Capital Signals a Post-Competition Business Strategy Already in Motion
Perhaps the most forward-looking data point in Gu’s business trajectory is her recent appointment as a Senior Associate at Benchmark, the venture capital firm led by Bill Gurley. This is a meaningfully different move than another endorsement deal or fashion campaign — it represents Gu building operating experience inside the institutional investing world while still an active competitive athlete, a sequencing choice that suggests a longer-term strategy of transitioning from “athlete with a personal brand” toward “operator with direct involvement in company-building and capital allocation” well before her competitive career concludes.
The Cross-Cultural Positioning That Underpins the Commercial Success
Gu’s commercial appeal is substantially built on a genuinely distinctive positioning: born and raised in San Francisco, she has competed for China since 2019 — a choice that drew public criticism from some in the US at the time but has since translated into standout commercial value in the Chinese market specifically, where she has been described by industry observers as a “golden star” with mainstream crossover appeal comparable to how Tony Hawk is positioned in US action sports culture. That dual-market credibility — genuine commercial traction in both major Western luxury markets and the Chinese domestic market simultaneously — is a structurally rare position for any athlete to occupy, and is arguably as important to her endorsement value as her competitive results themselves.
Actionable Takeaways for Readers Applying Gu’s Framework
- Separate your training mindset from your performance mindset deliberately, rather than trying to hold one constant state. Gu’s framework suggests self-criticism has a specific place (skill-building) and total confidence has a different, separate place (execution) — conflating the two may undermine both.
- Build confidence from accumulated evidence, not from repeated self-affirmation alone. If you’re preparing for a high-stakes moment — a presentation, an interview, a competition — Gu’s “evidence over affirmation” method suggests documenting concrete preparation and past performance data as your actual confidence foundation.
- Recognize that peak intensity is not sustainable as a constant state. Gu has been explicit that an all-in competitive mentality cannot be maintained indefinitely — treat high-intensity focus as something to deploy at specific moments rather than as your baseline operating mode.
- If building a personal brand, consider deliberate category diversification rather than single-lane concentration. Gu’s endorsement spread across fashion, lifestyle, automotive, and finance reduces dependency on any one industry’s cycles — a principle transferable well beyond professional sports.
- Treat major life transitions (like Gu’s Stanford graduation and Benchmark role) as planned sequencing rather than reactive pivots. Her move into venture capital appears to be a deliberate long-horizon career step taken while her athletic career is still active, rather than a post-retirement scramble — a sequencing lesson relevant to anyone building a career with a defined athletic or performance-based shelf life.
Frequently Asked Questions
What is Eileen Gu’s training mantra?
Gu’s stated mantra is “train like I’ve never won and compete like I’ve never lost” — a deliberately contradictory framework that keeps her self-critical and improvement-focused during training while adopting total, evidence-based confidence during actual competition.
How much is Eileen Gu worth in 2026?
Eileen Gu’s net worth is estimated at approximately $50 million as of 2026, according to Celebrity Net Worth as reported by Yahoo Sports, with the substantial majority of that wealth coming from endorsements and brand partnerships rather than skiing prize money.
What brands does Eileen Gu endorse?
Gu’s endorsement portfolio includes Louis Vuitton, Victoria’s Secret (as a founding member of the VS Collective), Tiffany & Co., Red Bull, Porsche, IWC Schaffhausen, Fendi, and Gucci, alongside China-market partners including Bank of China, China Mobile, and Luckin Coffee.
Does Eileen Gu have a career outside of skiing?
Yes — beyond her endorsement and modeling work (she is signed with IMG Models), Gu graduated from Stanford University in June 2026 and was subsequently named a Senior Associate at the venture capital firm Benchmark, signaling a deliberate move into institutional investing alongside her continued competitive skiing career.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Trump’s North America Flag Map Explained: Viral Image, USMCA Tensions

2026 Midterms: How Democrats Are Competing in Deep-Red Senate Seats

North American Tariff Standoff 2026: Supply Chain Guide

2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover

Analyzing Anthropic’s $15 Billion Credit Facility: What It Means for Stock Health

Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown

Johnny Ray and Nicole Mississippi: Attala County Case Explained

Clarence Thomas Unfiltered: The Ted Cruz Interview on Ethics and Identity

Fond du Lac Stalking Case: Serial-Killer Memorabilia, Skulls & the Criminal Complaint
Johnny Ray and Nicole Mississippi: Attala County Case Explained

Best Fitness Apps and Wearables That Connect to Health Insurance in 2026
2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover

RFK Jr. Confirmation Investigation 2026: Health Policy Fallout Explained
Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown
Fond du Lac Stalking Case: Serial-Killer Memorabilia, Skulls & the Criminal Complaint

CRM Stock, Workday, Cisco: What Earnings Signal Now
Clarence Thomas Unfiltered: The Ted Cruz Interview on Ethics and Identity

Shanghai Ravioli Chicken Recall 2026: Full Product List & Refund Guide
-

 Featured5 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Democracy5 years ago
Missing You! SPSC
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills