Analysis
Indonesia’s Danantara Shifts to Investment Phase, Targets 7% Returns — Sovereign Wealth Fund Enters Deployment Era Under Prabowo’s Ambitious Vision

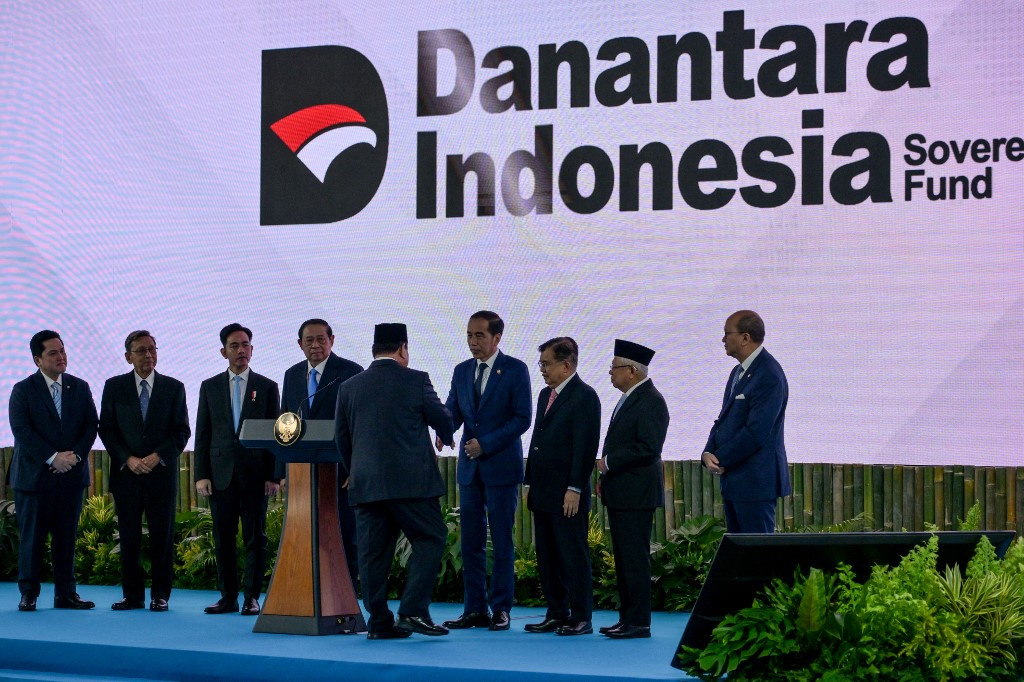
The morning light over Jakarta’s financial district has a way of making ambition look achievable. In the gleaming corridors of the Danantara Indonesia headquarters — a building that barely existed eighteen months ago — a quiet but consequential shift is underway. The sovereign wealth fund that President Prabowo Subianto unveiled with enormous fanfare in February 2025 has spent its inaugural year doing something unglamorous but essential: building the institutional scaffolding that separates a serious fund from a political showpiece. Now, as Indonesia’s Danantara sovereign wealth fund enters its investment phase in 2026, the real examination begins.
At the World Economic Forum in Davos in January, Chief Investment Officer Pandu Patria Sjahrir declared that Danantara’s target for investment fund placements in 2026 is set at $14 billion — nearly double the $8 billion allocated across all of 2025. Kompas The capital acceleration is not simply a number; it is a declaration of intent. The governance year is over. The deployment year has arrived.
Table of Contents
Year One: The Governance Foundation Nobody Talks About
Before you can deploy capital at scale, you need systems that can be trusted with it. That is the unglamorous lesson Danantara absorbed in 2025. Chief executive Rosan Roeslani acknowledged that a primary achievement of the first year was breaking down the siloed operations that had long plagued Indonesia’s state-owned enterprises, promoting greater transparency and internal value creation. Jakarta Globe
BCA Chief Economist David Sumual confirmed the picture candidly: Danantara’s main focus in 2025 was internal consolidation — restructuring efforts, organizational improvements, and recruitment of human resources — with no major projects having fully materialized by year’s end despite SOE dividends being reallocated to the fund. Indonesia Business Post
That candour from a senior domestic economist is actually a constructive signal. Unlike the opaque early years of Abu Dhabi’s IPIC or the dangerously undisclosed operations of Malaysia’s 1MDB before its collapse, Danantara’s leaders are at least publicly acknowledging the gap between aspiration and execution. The first year served as a necessary stress-test of internal architecture. The critical question, now that the architecture is nominally in place, is whether the deployment year delivers the returns its political patron is demanding.
The 7% Return Mandate: Prabowo’s Public Challenge
Few sovereign wealth fund leaders have their performance targets set quite so publicly — or quite so politically — as Pandu Sjahrir now does. President Prabowo Subianto has publicly set a target of 7% return on assets for the fund, a mandate that Sjahrir acknowledged directly, saying Danantara would gladly accept the challenge as it “searches for projects that can give higher returns with the same impact while improving standards.” Jakarta Globe
The 7% ROA hurdle deserves context. Indonesia’s current state-owned enterprise portfolio has historically generated returns on assets hovering near 1.88% — a figure that reflects decades of sub-optimal capital allocation, political interference in pricing decisions, and chronic underinvestment in productivity. Reaching 7% is not an incremental improvement. It represents nearly a fourfold leap in capital efficiency across a portfolio of more than 1,000 SOEs.
To understand whether the target is reachable, consider how the world’s benchmark sovereign funds perform. Singapore’s Temasek Holdings has delivered annualised total shareholder return of approximately 7% in Singapore dollar terms over its 50-year history — but this was achieved with an entirely different governance architecture, strict commercial independence from government policy directives, and a portfolio heavily weighted toward liquid, globally diversified assets. GIC, Singapore’s other sovereign vehicle, targets real returns above 4% over 20-year rolling periods while managing over $770 billion. Abu Dhabi’s Mubadala, a closer model given its hybrid development-investment mandate, has generated returns in the 8–12% range in its best years, but only after a decade of portfolio maturation and institutional discipline-building.
What Danantara needs — quickly — is a portfolio mix that can bridge the gap between its politically derived SOE inheritance and the commercially rational returns its mandate demands.
Shifting to Deployment: Bonds, Equities, and the Capital Market Play
In a presentation at the Indonesia Stock Exchange, Pandu Sjahrir confirmed that Danantara would begin investing SOE dividend capital in both bonds and equities through the capital market starting in 2026, with the explicit additional goal of deepening Indonesia’s relatively shallow domestic capital markets. Kompas
This two-pronged strategy is tactically sound. Fixed-income instruments — particularly Indonesian government bonds (SBN) and SOE-issued corporate bonds — offer predictable yields in the 6–7% range at current rupiah interest rate levels, immediately competitive with the ROA target. The equities component introduces both upside potential and volatility, but also provides the market liquidity and price-discovery function that Indonesia’s IDX has lacked for years.
Economic observer Yanuar Rizky assessed that Danantara’s entry as a major institutional investor could have a positive stabilising effect on Indonesia’s capital markets, provided the fund maintains a clear distinction between commercial portfolio investment and politically motivated market support operations. Kompas That caveat is pointed. If Danantara begins purchasing equities to prop up falling SOE stock prices rather than to generate returns, it will quickly become both a market distortion mechanism and a fiscal liability.
Danantara is also considering taking a shareholder position in the Indonesia Stock Exchange itself through its demutualization process — a move that would simultaneously give the fund a structural role in market governance while diversifying its asset base into financial infrastructure. Kompas
The $14 Billion Deployment Pipeline: Sectors and Scale
The capital earmarked for 2026 will flow primarily from SOE dividends and will target sectors including renewable energy, energy transition, digital infrastructure, healthcare, and food security. Danantara is also evaluating opportunities beyond Indonesia’s borders — specifically in China, India, Japan, South Korea, and Europe — though domestic allocation remains the dominant priority. Asia Asset Management
Six major projects were scheduled for groundbreaking in February 2026 alone, including an aluminum smelter and smelter-grade alumina facility in Mempawah, West Kalimantan; a bioavtur production facility at the Cilacap Refinery in Central Java; a bioethanol plant in Banyuwangi, East Java; and salt factories in Gresik and Sampang designed to supply Indonesia’s chlor-alkali industrial base. Kompas Together, these projects form the visible edge of what Danantara describes as a $7 billion downstream industrialization push — Indonesia’s long-deferred attempt to stop exporting raw nickel, bauxite, and palm oil and start exporting processed value.
The downstream story matters enormously for return-on-assets arithmetic. A nickel laterite operation generates modest margins; a battery cathode facility or EV component manufacturer attached to that same ore base can generate returns in the 12–18% range at commercial scale. That is the logic threading through Danantara’s investment thesis — and it is the same logic that has made Indonesia’s nickel-to-battery downstream push a subject of intense interest among Japanese, South Korean, and European manufacturers watching their supply chains with growing anxiety.
CEO Rosan Roeslani has emphasized that 2026’s strategy is built on risk-managed deployment and long-horizon value creation, with investment screens tightened to ensure capital flows only to projects with clear commercial merit and measurable economic impact. GovMedia
Danantara vs. The World’s Great Sovereign Funds: A Benchmark Comparison
| Fund | AUM (approx.) | 10-Year Return | Independence Model | Primary Focus |
|---|---|---|---|---|
| Norway GPFG | $1.7 trillion | ~8.5% p.a. | Statutory independence | Global equities/bonds |
| Temasek (Singapore) | ~$300 billion | ~7% TSR | Operational independence | Asia equities |
| GIC (Singapore) | ~$770 billion | 4%+ real | Full professional management | Global diversified |
| Mubadala (Abu Dhabi) | ~$300 billion | 8–12% (peak) | Semi-commercial | Strategic/development |
| Khazanah (Malaysia) | ~$35 billion | Mixed | Political proximity | Domestic SOEs |
| Danantara (Indonesia) | ~$900 billion AUM | Target: 7% ROA | Political appointment-led | SOEs + strategic projects |
The table tells a revealing story. Danantara is already one of the largest sovereign vehicles on earth by nominal AUM — but AUM and investable capital are very different things when the underlying portfolio consists largely of SOE assets that are neither liquid nor independently valued. Norway’s Government Pension Fund Global can credibly report 8.5% annualised returns because its portfolio is marked to liquid global market prices daily. Danantara’s SOE assets are carried at book values that may significantly diverge from what arms-length buyers would actually pay.
This is not a fatal flaw — it is a governance design choice with profound implications for how the 7% target gets measured. If Danantara measures ROA against re-valued, market-based asset prices, the benchmark is genuinely demanding. If it measures against legacy book values, the headline number may look better while concealing underlying performance deterioration.
The Broader Economic Stakes: Indonesia’s Path Past the Middle-Income Trap
Danantara does not exist in isolation. It is the financial architecture beneath President Prabowo’s “Golden Indonesia 2045” vision — the aspiration to reach developed-nation status within a generation. The fund was explicitly designed to help accelerate the president’s target of 8% annual GDP growth by his term’s end in 2029, consolidating and streamlining SOE operations to unlock productivity gains that fragmented management had suppressed for decades. Fortune
Indonesia’s GDP per capita, currently around $5,000, needs to triple to reach developed-world thresholds. That requires sustained, compounding productivity improvements across agriculture, manufacturing, energy, and services simultaneously. Danantara — if it functions as designed — could accelerate this by directing capital toward infrastructure gaps, energy transition assets, and downstream industries that private markets have been too cautious or too short-sighted to finance at the required scale.
Prabowo’s pitch to American business leaders in Washington in February 2026 was explicit: all state-owned assets have been consolidated under Danantara to accelerate investment, and the fund will serve as a primary engine of Indonesia’s economic transformation. Jakarta Globe The geopolitical subtext was equally clear — Indonesia is positioning itself as a destination for capital diversifying away from Chinese concentration and seeking access to Southeast Asia’s 280 million-strong consumer middle class.
Pandu Sjahrir, speaking at the South China Morning Post’s China Conference: Southeast Asia 2026 in Jakarta in February, framed the geopolitical dimension directly: “In the new geopolitical world, every country and every leader uses sovereign wealth funds as a geopolitical tool,” while insisting that Danantara must operate for profit rather than politics. South China Morning Post The tension between those two imperatives — geopolitical instrument and commercially disciplined investor — defines Danantara’s central challenge, and is one that even mature funds like Mubadala have never fully resolved.
Risks, Scrutiny, and the 1MDB Shadow
No serious analysis of Danantara can avoid the governance concerns that have trailed the fund from its inception. Following Danantara’s inauguration, the Jakarta Composite Index fell 7.1%, driven by continuous foreign capital outflows of approximately $622.7 million — a market verdict on investor discomfort with the fund’s legal structure and oversight architecture. East Asia Forum
The concerns are structural, not merely perceptual. Indonesia’s national audit bodies — the Financial Audit Board (BPK), the Agency for Financial and Development Supervision (BPKP), and the Corruption Eradication Commission (KPK) — have limited ability to monitor Danantara’s managed assets. Audits can only be conducted upon request from the House of Representatives, creating an oversight model that is reactive rather than systematic. Wikipedia
Critics have pointed out that Danantara’s senior leadership emerged from political negotiation as much as merit selection — CEO Rosan Roeslani served as Prabowo’s campaign chief, while Pandu Sjahrir served as the campaign’s deputy treasurer. East Asia Forum These connections do not automatically disqualify either man — Temasek’s own senior officials maintain government proximity — but they demand an unusually clear demonstration of commercial independence before institutional investors will commit capital with confidence.
Economists have also flagged crowding-out risks: as Danantara absorbs SOE dividends and raises capital through bond instruments, private sector investment appetite may be compressed, particularly if Patriot Bond subscriptions divert capital that listed companies would otherwise have deployed for their own growth. Indonesia Business Post
The Patriot Bond programme itself has attracted commentary that is difficult to ignore. Financial analysts widely viewed the initiative — which raised over Rp50 trillion from Indonesia’s business elite — as carrying the implicit return of political goodwill rather than purely financial reward, describing it as a “loyalty test” for the nation’s conglomerates. Wikipedia These are not conditions under which a world-class sovereign fund typically operates.
Investor Outlook: What Global Capital Should Watch
For international investors, Danantara’s deployment year presents a calibrated opportunity set rather than a binary bet. The fund’s entry into Indonesia’s bond and equity markets will provide liquidity and potentially improve price discovery on SOE-linked assets that have historically been thinly traded. Indonesia’s sovereign bond yields — currently in the 6.8–7.2% range for 10-year instruments — already offer competitive real returns given the country’s current inflation trajectory, and Danantara’s institutional demand will provide additional market support.
The downstream projects represent a longer-dated opportunity. Investors with three-to-five-year horizons who gain exposure to Indonesia’s nickel-to-battery value chain — whether through listed SOEs, joint venture structures, or Danantara-linked project bonds — are positioning for a structural shift in global clean-energy supply chains. The risk is not the economics of the projects themselves; it is the execution timeline and the political discipline to resist using Danantara as a budget-substitute during fiscal pressures.
Danantara’s 2026 Corporate Work Plan, presented to the House of Representatives, emphasised that every investment must be “bankable and truly value-accretive” — a standard borrowed from the private equity lexicon that, if genuinely applied, would represent a meaningful departure from the historically political character of Indonesian SOE capital allocation. Danantara Indonesia
Whether that departure is real or rhetorical will become clear within the next eighteen months. The projects are breaking ground. The bonds are being issued. The capital is beginning to flow. And in a country of 280 million people sitting atop some of the world’s most valuable commodity and consumer market assets, the upside — if governance holds — is not 7%. It is considerably higher.
Prabowo’s fund has set the floor. The ceiling is a function of institutional integrity.
Conclusion: The Deployment Era Begins — And the Scrutiny Deepens
Indonesia’s Danantara sovereign wealth fund enters 2026 at an inflection point that will define its legacy for a generation. The governance infrastructure is nominally in place. The capital pipeline — $14 billion targeted for deployment this year — is the largest in the fund’s short history. The 7% return-on-assets mandate, set publicly by the president himself, is ambitious relative to current SOE performance baselines but achievable if capital is deployed into commercial-grade projects with rigorous discipline.
The fund’s peer group — Temasek, GIC, Mubadala, Norway’s GPFG — took years, sometimes decades, to earn the institutional credibility that translates into sustained performance. Danantara does not have that luxury of time. Indonesia’s growth aspirations are set on a compressed timeline, and the political expectations attached to this fund are enormous.
What sophisticated investors should watch: the actual returns posted in Danantara’s first audited annual report; the independence and credibility of whichever oversight mechanism emerges; the performance of the six downstream projects currently breaking ground; and whether the fund’s capital market activities in bonds and equities reflect commercial logic or political stabilization.
The fund carrying the weight of Indonesia’s Golden 2045 vision is now, at last, actively deploying. The test of whether Danantara becomes Southeast Asia’s defining sovereign fund — or its most cautionary tale — begins today.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


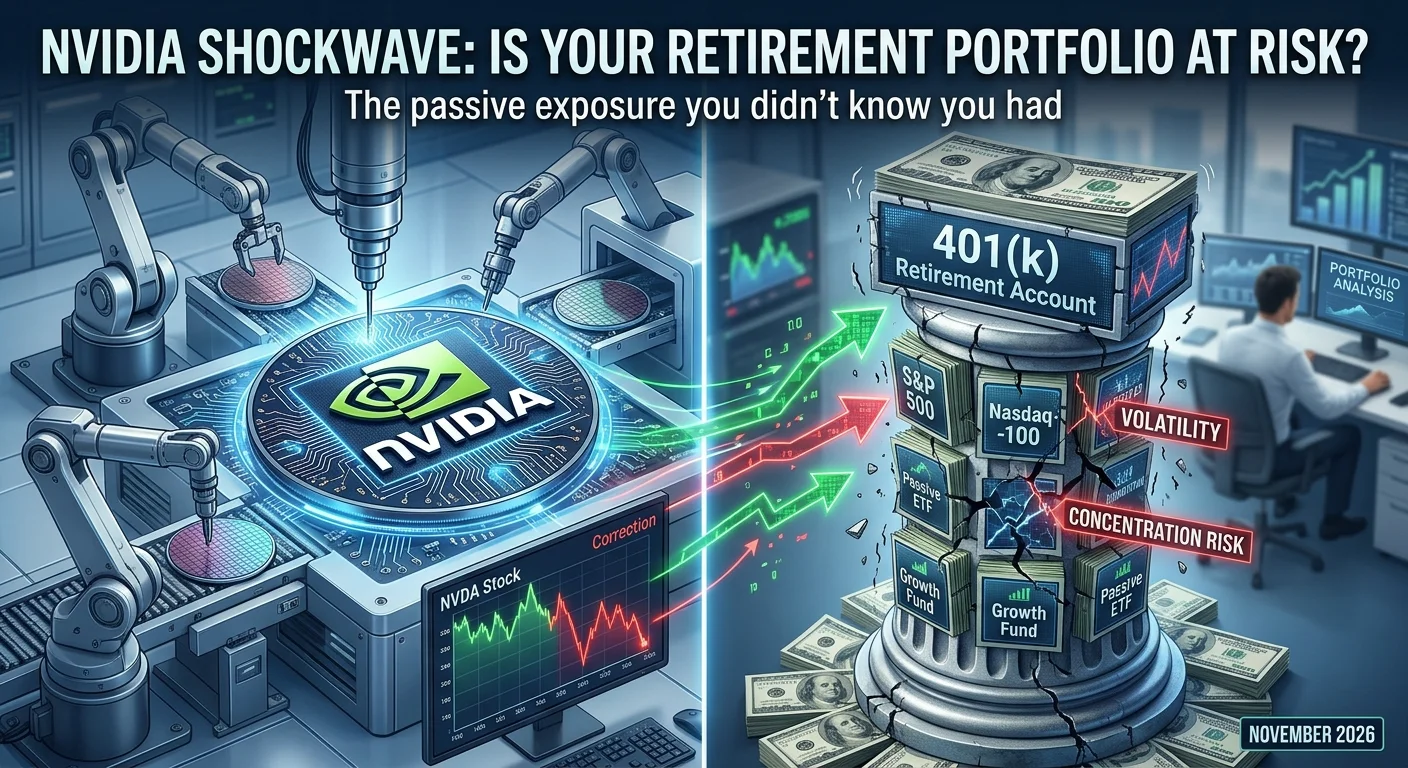
Recent market turbulence centered around artificial intelligence bellwether Nvidia (NASDAQ: NVDA) has sent shockwaves across Wall Street, triggered by a steep correction following the sudden resignation of longtime CEO Jensen Huang.
For everyday savers who believe they are safe because they do not own a single individual share of tech stocks, the reality is starkly different. Due to Nvidia’s massive weight in major equity indices, millions of Americans watching their retirement accounts fluctuate are experiencing a hard lesson in concentration risk.
1. The S&P 500 and Nasdaq Concentration Problem
Over the past several years, the explosive growth of generative AI transformed Nvidia into a titan of the global economy, commanding a market capitalization that pushed its weighting in major capitalization-weighted indexes to historic highs:
- S&P 500 Exposure: Nvidia commands roughly 6% to 8% of standard S&P 500 index funds (such as SPY or VOO).
- Tech-Heavy & Growth Funds: In specialized tech-heavy or growth-oriented ETFs (like the Invesco QQQ tracking the Nasdaq-100), Nvidia’s exposure routinely scales past 6.5% to 25% depending on the specific mandate.
The Math Behind the 401(k) Hit
When a mega-cap stock experiences a sharp ~30% correction over a single month—compounded by sudden leadership turmoil and board investigations—the math hits passive retirement portfolios hard:
- For every $100,000 allocated to a standard S&P 500 index fund, a 30% drop in Nvidia accounts for an approximate $2,400 reduction in underlying value (assuming other index components remain flat).
- For a typical Baby Boomer with an average 401(k) balance near $260,000 heavily weighted toward growth or index-tracking tech portfolios, the structural reduction can easily translate to a $15,000 to $20,000 paper loss.
2. The Illusion of Diversification: Overlap Risk
Many retirement investors assume that holding multiple funds guarantees safety. However, modern 401(k) lineups often suffer from hidden overlap risk.
An investor holding a mix of a broad S&P 500 fund, a Nasdaq-100 growth fund (QQQ), a technology sector ETF (XLK), and a semiconductor index (SMH) may believe they are diversifying across different vehicles. In reality, they are often doubling and tripling down on the exact same underlying asset. When a shock hits Nvidia, multiple pillars of their portfolio fracture simultaneously.
3. Strategic Action Plan for 401(k) Investors
Market corrections triggered by corporate governance shocks or executive departures serve as vital stress-tests for personal wealth plans. Financial professionals recommend taking the following proactive steps:
+---------------------------------------------------------------+
|             401(k) RISK MITIGATION CHECKLIST                  |
+---------------------------------------------------------------+
| [ ] 1. Audit Underlying Holdings: Look past fund names        |
|        to check top-10 equity weightings.                     |
| [ ] 2. Evaluate Overlap: Identify if multiple funds           |
|        duplicate mega-cap tech exposure.                      |
| [ ] 3. Consider Equal-Weight Alternatives: Explore equal-     |
|        weighted indexes (e.g., RSP) to reduce single-stock    |
|        dominance.                                             |
| [ ] 4. Rebalance with Discipline: Align asset allocation      |
|        with your actual risk tolerance, not recent hype.      |
+---------------------------------------------------------------+
- Conduct a Portfolio X-Ray: Use retirement platform tools to look past fund labels and analyze your true aggregate exposure to top-tier mega-cap stocks.
- Explore Equal-Weight Alternatives: For investors concerned about market cap concentration, shifting a portion of equity allocation to equal-weighted indexes (such as the Invesco S&P 500 Equal Weight ETF) ensures that a single corporate event cannot disproportionately sway total returns.
- Remember the Golden Rule of Volatility: Paper losses in a long-term retirement vehicle do not crystallize unless positions are sold during a panic. Time horizon and disciplined asset allocation remain the ultimate safeguards against single-stock volatility.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
Can the new Congress challenge Trump’s immigration crackdown—or will election-night history meet the hard limits of presidential power?

On election night in Michigan, Abdul El-Sayed did more than hold a Senate seat for the Democrats. A 42-year-old physician and former public-health official, the American-born son of Egyptian immigrants became, according to media projections, the first Muslim ever elected to the United States Senate. The Republican he defeated, former congressman Mike Rogers, had questioned his political associations through allegations of extremist sympathies that El-Sayed denied and that Reuters reported were unsupported by evidence.
The result carried unmistakable symbolic weight. After months in which arguments about national identity and immigration enforcement filled American politics, a Muslim candidate won statewide office in a battleground that had twice supported Donald Trump for president. With about 97% of votes counted, El-Sayed led by seven percentage points, the Associated Press reported. Those are preliminary returns, not a certified final margin.
Yet the hardest question begins where the celebration ends. Can a senator-elect, even one whose victory expands the boundaries of political representation, alter the federal machinery that determines whether migrants are detained, deported, given a hearing—or returned to families? Or will the Democratic takeover of Congress produce televised confrontations while immigration agents continue to operate under presidential direction?
The midterms answered one question decisively: control of Congress can change. Whether the treatment of immigrants changes with it is a much more demanding test.
A breakthrough—though not a wave of immigrant-born senators
The distinction matters from the outset. El-Sayed is not an immigrant; he was born in Michigan to Egyptian immigrant parents. His win is a milestone for Muslim representation and for the children of immigrants, not evidence that large numbers of foreign-born candidates captured Senate seats. Reuters’ account of the reaction in Egypt illuminates both the significance of his heritage and the awkwardness of treating an American election as a victory belonging to another nation.
El-Sayed’s biography resists a single-issue reading. He trained as a physician, led Detroit’s health department, lost a Democratic gubernatorial primary in 2018, and returned with a campaign centered on affordability, corporate influence and Medicare for All. His opposition to unconditional American military support for Israel drew intense scrutiny; his Republican opponent argued that his views were too radical. CBS News’ examination of the campaign and the Associated Press’ post-election interview show a candidate who won by emphasizing economic discontent while also confronting attacks on his religion.
A candidate’s identity does not establish his entire agenda. On immigration, however, El-Sayed has made specific commitments. In an October interview with Michigan Public, he supported border security but called for abolishing ICE and replacing its approach with an enforcement and administrative system closer to the former Immigration and Naturalization Service. He criticized operations involving masked officers and argued that Congress had relinquished too much of its constitutional authority. His position is more sweeping than a demand for better body cameras or disciplinary proceedings: it would require Congress to redesign a federal agency.
The wider Senate class reveals a different pattern: an enlargement of political backgrounds, not a homogeneous immigrant caucus.
| Senator-elect | State | Verified political significance | Connection to immigration debate |
|---|---|---|---|
| Abdul El-Sayed (D) | Michigan | First Muslim elected to the Senate; U.S.-born son of Egyptian immigrants | Has called for replacing ICE and reforming immigration law |
| Peggy Flanagan (D) | Minnesota | First Native American woman elected to the Senate; member of the White Earth Nation | Represents an Indigenous political milestone, not an immigrant background |
| Juliana Stratton (D) | Illinois | Becomes part of a historic expansion of Black women’s Senate representation | Campaigned on abolishing ICE; not presented as immigrant-born |
| James Talarico (D) | Texas | Former teacher and state lawmaker; defeated Ken Paxton | Victory included a shift among Hispanic voters; his identity should not be conflated with immigrant status |
| Adam Hamilton (D) | Kansas | Methodist pastor who defeated Republican Roger Marshall | Stressed affordability and cross-party cooperation, illustrating motives beyond immigration |
| Josh Turek (D) | Iowa | Former Paralympian and state legislator who flipped a Republican-held seat | Disability representation and economic campaigning, not an immigrant-origin claim |
These election calls are drawn from Minnesota Public Radio, Axios’ Illinois reporting, AP’s Texas account, Reuters on Kansas and AP on Iowa. These are projected results pending the normal certification process; comparable final vote margins were not available for every race at this research cutoff.
The House contributes another part of the story. Muslim candidates reported as winners include New Jersey’s Adam Hamawy and New York’s Darializa Avila Chevalier alongside returning members such as Ilhan Omar and Rashida Tlaib, according to Dawn’s November 5 overview. This is an expansion of Muslim congressional representation across chambers, not a list of new senators. Nor should Muslim identity be used as a synonym for immigration status.
What the voters rejected—and what they did not
Democrats seized control of both chambers, including unexpected Senate gains in Texas, Kansas, Iowa, South Carolina, Maine, North Carolina and Ohio. As of the morning after the election, Reuters reported at least 54 Senate seats for the Democratic side, including allies, with some races unresolved. The Washington Post’s Senate results coverage documents the breadth of the shift.
It would nevertheless be a mistake to describe this as a referendum exclusively on deportations or anti-Muslim politics. A final Reuters/Ipsos survey of 1,765 adults found that 48% of registered voters named living costs as their leading consideration, versus 26% who named democratic norms and 13% who named immigration. That was a pre-election poll, not an exit poll proving why particular people voted as they did.
The more revealing finding is that immigration enforcement generated discontent without becoming the only, or even the principal, electoral issue. AP’s national Voter Poll, covering more than 100,000 voters, found roughly six in ten Hispanic voters supporting Democratic House candidates, a significant change from the coalition that backed Trump in 2024. In Texas, about six in ten Hispanic Senate voters supported Talarico, against approximately three in ten for Paxton. These are survey estimates for specific electorates and contests, not a census of all Hispanic Americans.
Economic and political factors overlapped. The Washington Post’s analysis of its voter survey found that voters focused on immigration and crime still tended to prefer Republicans. A party can therefore lose an election without the country rejecting every element of its immigration platform. Discontent over the Iran war, gasoline prices, tariffs, health care and government accountability was also central to the result.
A further correction is essential: most immigrants cannot vote unless they have become U.S. citizens. Many Hispanic voters were born in the United States, while naturalized citizens come from every region of the world. A Congressional Research Service demographic briefing updated in September 2026 estimated 50.2 million foreign-born U.S. residents in 2024, including approximately 25.8 million naturalized citizens. Calling the midterms an “immigrant vote” without distinguishing citizenship, ancestry and ethnicity would obscure the very communities the description claims to represent.
The more defensible interpretation is that Americans assembled several forms of dissatisfaction into one electoral outcome. Identity mattered in Michigan. Enforcement tactics mattered in places touched by raids. Prices mattered almost everywhere. A national coalition won; its individual members did not necessarily vote for the same immigration reforms.
The enforcement record Congress inherits
The Trump administration’s argument is that vigorous enforcement protects public safety, restores the integrity of immigration law and deters unauthorized entry. Its supporters point to reduced unlawful border crossings and an expanded capacity to arrest and remove people subject to immigration proceedings. A pre-election AP examination of the crackdown reported both the border-security achievements claimed by the administration and the growing backlash against enforcement encounters inside American communities.
But border management and interior enforcement are distinct enterprises. The question is not simply whether a government may enforce immigration law—it may—but what procedures govern encounters, whether people can contest removal and what happens when officers make mistakes.
The restrictions extend beyond undocumented migrants. In January 2026, the administration expanded entry and visa restrictions affecting nationals of 39 countries and holders of Palestinian Authority travel documents, with category-specific exceptions. The State Department’s own guidance explains the restrictions as national-security screening. Many affected countries are Muslim-majority, but not all are; critics characterize the policy as discriminatory in design or effect. A serious legal assessment must identify the actual rule, its exceptions and the evidence for any allegation of religious discrimination rather than assume that nationality and religion are interchangeable.
Courts have not delivered a uniform verdict in immigration cases. In June, the Supreme Court rejected the administration’s broad effort to limit birthright citizenship under the Fourteenth Amendment, Reuters reported. Yet in September the same court permitted third-country deportations to resume while it considers the underlying litigation, according to Reuters. The administration argues that such transfers help remove people, including those with criminal convictions; challengers contend that migrants must be able to raise credible fears of persecution or torture before removal to an unfamiliar country. An interim court order allowing a practice to proceed is not a final determination that every application is lawful.
The consequences are immediate, not theoretical. On November 4, AP reported a federal judge’s temporary order restricting deportations of detained Afghans to Afghanistan or Pakistan after warnings about persecution risks. The case illustrates why due process has practical importance even when there is broad public support for border control: a removal decision may be irreversible long before the legal dispute is resolved.
Economic consequences also resist easy slogans. Pew Research Center estimates show that immigrants have become a substantial part of the U.S. workforce. Their participation varies across sectors and legal categories. Enforcement can reduce exploitation where unlawful employment is addressed, but indiscriminate disruptions may also impose costs on employers, workers and communities. Evaluating policy therefore requires both border and workplace data, not only arrest totals.
Three deaths, and a larger question about accountability
The killing of Lorenzo Salgado Araujo in Houston on July 7 exposes the risks of viewing every enforcement encounter solely through an immigration-status lens. The 52-year-old Mexican national was shot by an ICE officer during an attempted vehicle stop. DHS said he tried to ram an officer and that the shooting was in self-defense. His family disputed the official description. Crucially, DHS later acknowledged the officers had been seeking someone else and stopped Araujo because he resembled their target, according to AP reporting.
Agents involved were not wearing body cameras, Houston Public Media reported. Investigations were opened, and the family’s demand for an independent account remained separate from DHS’s assertion of justification. The medical examiner’s designation of a death as homicide, where applicable, is a classification of how a person died—not a criminal judgment that an officer committed murder.
Two killings in Minneapolis earlier in 2026 raised related but different questions. On January 7, ICE officer gunfire killed Renee Good, a U.S. citizen, during a vehicle encounter. Administration officials described the shooting as self-defense; AP’s examination documented video evidence, public disagreement and ongoing investigations. On January 24, federal Border Patrol agents killed Alex Pretti, also a U.S. citizen and an intensive-care nurse. The government’s initial account said he approached with a handgun; Reuters’ review of bystander video raised significant questions about the sequence of events. FactCheck.org’s analysis likewise identified claims unsupported or apparently contradicted by available footage, while warning that the investigation was incomplete.
Good and Pretti were not immigrants. Their deaths belong in this article because they arose from federal immigration operations and intensified debate about officer identification, use-of-force rules, incident reporting and independent review. Conflating their deaths with migrant fatalities would weaken the accuracy of that debate.
Deaths in detention constitute another category entirely. In June, a Reuters investigation found 50 deaths in immigration detention since January 2025 and estimated that the annualized death rate relative to the average detained population had more than doubled compared with its 2009–2024 benchmark. In September, Bloomberg Law reported 37 deaths in ICE detention during the fiscal year then ending. The figures refer to different time windows; they must not be added together.
The Department of Homeland Security has disputed claims of a rising death rate and says it maintains a high standard of medical care, as Reuters reported in June. Experts caution that illnesses, suicide, age and changing detainee populations complicate direct causal attribution. Yet complications are precisely why transparent mortality data, medical reviews and independent inspections matter. AP’s investigation into suicides in custody identified apparent shortcomings in mental-health screening and monitoring, while DHS defended its care standards.
Neither a tragic outcome nor a disputed video automatically establishes a criminal offence. Equally, invoking self-defense cannot substitute for an evidence-based investigation. The institutional question is whether investigators can obtain records, witness testimony and usable video without relying wholly on the agency whose personnel are under scrutiny.
The Senate can investigate; it cannot govern by investigation alone
The election substantially changes the machinery of oversight. Democratic chairpersons can schedule hearings, seek documents and, under committee procedures, pursue subpoenas. They can examine hiring and training standards, deaths in custody, the handling of medical emergencies, body-camera compliance, contracts with detention operators and the chain of command after fatal incidents. The Senate’s own description of investigative powers makes clear that inquiry is an established element of congressional responsibility, while its committee guidance distinguishes investigative, legislative and confirmation hearings.
Those powers are not personal prerogatives of a senator-elect. A single member can demand answers and organize public attention; enforceable congressional subpoenas ordinarily depend on authority delegated to a chamber or committee. The Justice Department’s published legal analysis makes that distinction explicit. Incoming members usually begin regular terms on January 3, 2027. They cannot simply command ICE officers in November.
The Senate can also refuse to confirm certain executive and judicial nominees, compel administration officials to defend their policies in public and consider statutory changes to detention conditions or the handling of administrative appeals. But replacing ICE, as El-Sayed advocates, would require legislation, institutional redesign, agreement over who conducts enforcement and sufficient votes. Oversight may expose violations; investigations do not themselves rewrite immigration law.
Control of both houses adds another lever: the power of the purse. There is an important catch. Congress already enacted substantial multiyear border and immigration-enforcement funding in 2026. A Congressional Research Service summary of FY2027 appropriations notes that ICE and Border Patrol continue to draw on resources from a reconciliation measure rather than relying entirely on annual appropriations. The Congressional Budget Office puts that 2026 reconciliation funding at $70 billion for those operations.
That financing limits any simple strategy of withholding next year’s regular ICE appropriation. Rescinding already enacted funds or changing the governing statutes generally requires another law, and therefore must confront the president’s signature or veto. Congress can still seek records, attach conditions to legislation that can pass, examine contracts, and make the political and administrative costs of opaque enforcement more visible.
Here the difference between protest and policy becomes evident. An investigation that identifies a broken procedure can produce a public record. A committee proposal can translate that record into a specific standard. A negotiated law can give that standard force. Each stage needs a different coalition and faces different resistance.
Trump’s veto is powerful, but it is not a universal shield
Trump has signaled that he intends to use the veto. He told CBS News in an election-day interview that it was his ultimate weapon against a Democratic Congress; after the results he publicly displayed a hat bearing the word “VETO,” as The Wall Street Journal reported.
Article I of the Constitution enables Congress to override a veto only with two-thirds of members voting in each chamber, provided a quorum is present. The Congressional Research Service’s January 2026 guide explains the mechanism. Democrats’ projected majorities are not by themselves veto-proof. Normal Senate rules, including the filibuster for most legislation, create further barriers well before a bill reaches the president’s desk.
But the veto is not authority to erase court rulings, cancel congressional investigations or prevent every request for documents. Nor does it let a president create funds that Congress has not lawfully provided. Executive discretion remains considerable, particularly over enforcement priorities and agency leadership, but it operates within statutory and constitutional limits. Court disputes may be prolonged; they are not resolved by a presidential slogan.
The next two years could therefore feature confrontation without automatic policy reversal. Hearings can focus attention on detention deaths and fatal force; judges can decide individual procedural claims; agencies can continue enforcing existing law; lawmakers can seek compromise on medical-care standards, reporting requirements and transparent identification. The administration’s security case deserves scrutiny against measurable outcomes, while critics’ allegations deserve testing against records rather than repetition as settled fact.
The three paths from 2027 to 2028
One path is sustained institutional conflict. Congressional committees summon DHS leaders, request operational files and dispute appropriations; the administration resists requests it considers intrusive or politically motivated. Such conflict could clarify facts, but prolonged litigation and legislative stalemate may limit immediate relief for affected families.
Another is selective negotiation. Legislators who disagree about deportation targets might nevertheless find common ground on body cameras, death reporting, credible-fear procedures, healthcare inspections or clear rules for encounters with the public. Even modest agreement would require the White House and both chambers to accept detailed, enforceable provisions. The electoral coalition itself gives no guarantee of that bargain.
A third is administrative continuity amid intensified scrutiny. Existing funding sustains operations, the president vetoes major restructuring and courts address discrete disputes as they arise. Under this path, a new Congress could alter public understanding and agency behavior without achieving the broader reforms some of its members seek.
These are institutional possibilities, not predictions. Their shape will depend on legislators’ priorities, committee assignments, executive responses, judicial decisions and public evidence yet to emerge. None should be assigned a numerical probability merely to make the analysis appear scientific.
A historic seat is not the same as a protected home
The symbolic meaning of El-Sayed’s election is substantial precisely because American citizenship, religious belonging and access to power have long been contested subjects. But symbolic representation and legal protection operate on different calendars. One changes with a ballot count; the other may depend on a detention decision made before dawn, a lawyer securing access to a client, or an officer recording a use of force.
The newly elected senators represent different constituencies and different political ideas. A Muslim senator may advocate ending ICE. A Native American senator may approach state power through the history of sovereignty and dispossession. A Black woman senator may draw on experience in law and government. A pastor from Kansas or a teacher from Texas may emphasize affordability, public accountability or negotiated enforcement. None should be presumed to speak for an entire community, and the people affected by immigration policy are neither uniformly Democratic nor uniformly opposed to deportation.
There is also a danger in imagining that the election has lifted all fears. The Washington Post reported that voting itself proceeded broadly smoothly, despite pre-election concern about federal interference. That civic success does not resolve the status of asylum seekers, undocumented workers, lawful residents confronting travel restrictions or families divided by detention.
America’s midterms produced a visible change in who holds congressional power. They did not transfer control of federal immigration agencies to the opposition party, invalidate existing statutes or repeal money already appropriated. They created oversight opportunities and raised the political cost of unchecked assertions, while leaving substantial executive discretion intact.
That is the central distinction between an electoral milestone and governing change. El-Sayed’s arrival will show that a Muslim American can win a statewide Senate contest despite attacks connected to his faith. What the next Congress does with subpoenas, nominations, appropriations and legislative negotiations will show whether a historic increase in representation produces more reliable rules for the millions of people who live under immigration law. The answer will not be found in a victory speech. It will be found in the public record of the next two years.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
President Donald Trump said Tuesday that the United States will end its roughly $4 billion in annual funding to Israel by the close of this year under an agreement he reached months ago with Israeli Prime Minister Benjamin Netanyahu.
Speaking by phone on Fox News’ Fox & Friends as Americans voted in the midterm elections, Trump stated that the two leaders had decided to halt the payments because Israel “doesn’t need it” and to remove what he described as a damaging political talking point used by critics.
“Now, as far as paying Israel, Bibi Netanyahu and I have made a deal that we give Israel $4 billion a year, and we made a deal months ago that we’re stopping,” Trump said. “We’ve already agreed that by the end of this year we won’t be paying Israel. Now, we’ll help Israel if they need it.”
Trump added that Netanyahu had raised the idea himself, saying the Israeli leader told him it would be “appropriate” not to receive the aid given domestic political controversy in the United States. He specifically referenced criticism from Democratic Michigan Senate candidate Abdul El-Sayed and others on the left, calling continued payments “a bad talking point”.
The announcement immediately raised questions about implementation. The current U.S.-Israel Memorandum of Understanding, which provides about $3.8 billion annually in military assistance, does not expire until 2028. U.S. military aid to Israel is appropriated by Congress, and experts noted that abrupt termination of ongoing programs—particularly in missile defense and counter-drone systems—would face legal and logistical hurdles. Trump has not detailed the precise mechanism or timeline for ending the funding.
There was no immediate confirmation from Netanyahu’s office or Israel’s foreign ministry. Israeli defense and financial officials were reportedly caught off guard by the public statement. The U.S. State Department did not respond to requests for comment.
The move comes amid declining American public support for unconditional aid to Israel since the war in Gaza that began in 2023. A recent Quinnipiac University poll found that nearly half of U.S. voters overall, and two-thirds of Democrats, believe the United States is too supportive of Israel. Aid to Israel has also become a point of contention within the Republican Party, drawing criticism from some isolationist and “America First” voices.
Trump framed the decision as consistent with a strong alliance, emphasising that the U.S. would continue to support Israel “if they need it” and that Israel remains a key partner. He noted that Israel could still purchase American weapons.
Analysts described the timing—on Election Day—as potentially aimed at neutralising attacks from both progressive Democrats and some within the MAGA coalition. Former Republican Rep. Marjorie Taylor Greene wrote on X that the announcement was unlikely to change midterm results, while others questioned whether the pledge would hold after the election.
The development marks a significant rhetorical shift in a relationship that has included steady U.S. military financing for decades. Whether the stated cutoff materialises by the end of 2026, and in what form, remains unclear pending further details from the White House and any formal agreement with Israel.
References
Al Jazeera. (2026, November 3). Trump says US will stop giving Israel aid after year-end. https://www.aljazeera.com/news/2026/11/3/trump-announces-that-us-will-stop-paying-israel-after-year-end
Debusmann, B., Jr. (2026, November 3). Trump says US ‘won’t be paying Israel’ by end of year. BBC News. https://www.bbc.co.uk/news/articles/cmx2dlx86n9yo
Reuters. (2026, November 3). Trump says US will stop $4 billion in funding to Israel at end of 2026. https://www.reuters.com/world/middle-east/trump-says-us-will-stop-paying-israel-after-year-end-2026-11-03/
Times of Israel. (2026, November 3). Trump says US to end $4 billion in annual military aid to Israel by end of 2026. https://www.timesofisrael.com/trump-says-us-to-end-4-billion-in-annual-military-aid-to-israel-by-end-of-2026/
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Kushner and Witkoff’s Secret Map for Europe

Inside Democrats’ Denver Victory Lap: Post-Midterm Euphoria Collides With a Brewing 2028 Divide

Nvidia Shockwave: Why Your 401(k) is More Exposed to the Chip Giant

DC Doctor Matt Wade Lambert Identified as Suspect in Logan Circle Gym Shooting

Congress can’t stop Trump’s wars. It can make them expensive.

The Millers and the New Washington Power Couple

The Municipal Left Turn: Can They Govern?

The First Muslim Senator and the Limits of America’s Midterm Revolt

Trump Announces U.S. Will Stop $4 Billion Annual Aid to Israel by End of 2026

What Is Trump Doing on Election Day 2026? Inside His White House Plans
Trump Announces U.S. Will Stop $4 Billion Annual Aid to Israel by End of 2026

Tesla, SpaceX and Starlink: The Real Business Story Behind Elon Musk’s October Buzz
The First Muslim Senator and the Limits of America’s Midterm Revolt
The Millers and the New Washington Power Couple
The Municipal Left Turn: Can They Govern?
Congress can’t stop Trump’s wars. It can make them expensive.
Kushner and Witkoff’s Secret Map for Europe
DC Doctor Matt Wade Lambert Identified as Suspect in Logan Circle Gym Shooting
-

 Featured6 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 Democracy5 years ago
Missing You! SPSC
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day