Analysis
Trump Extends Iran Talks Deadline amid Sell-Off on Wall Street

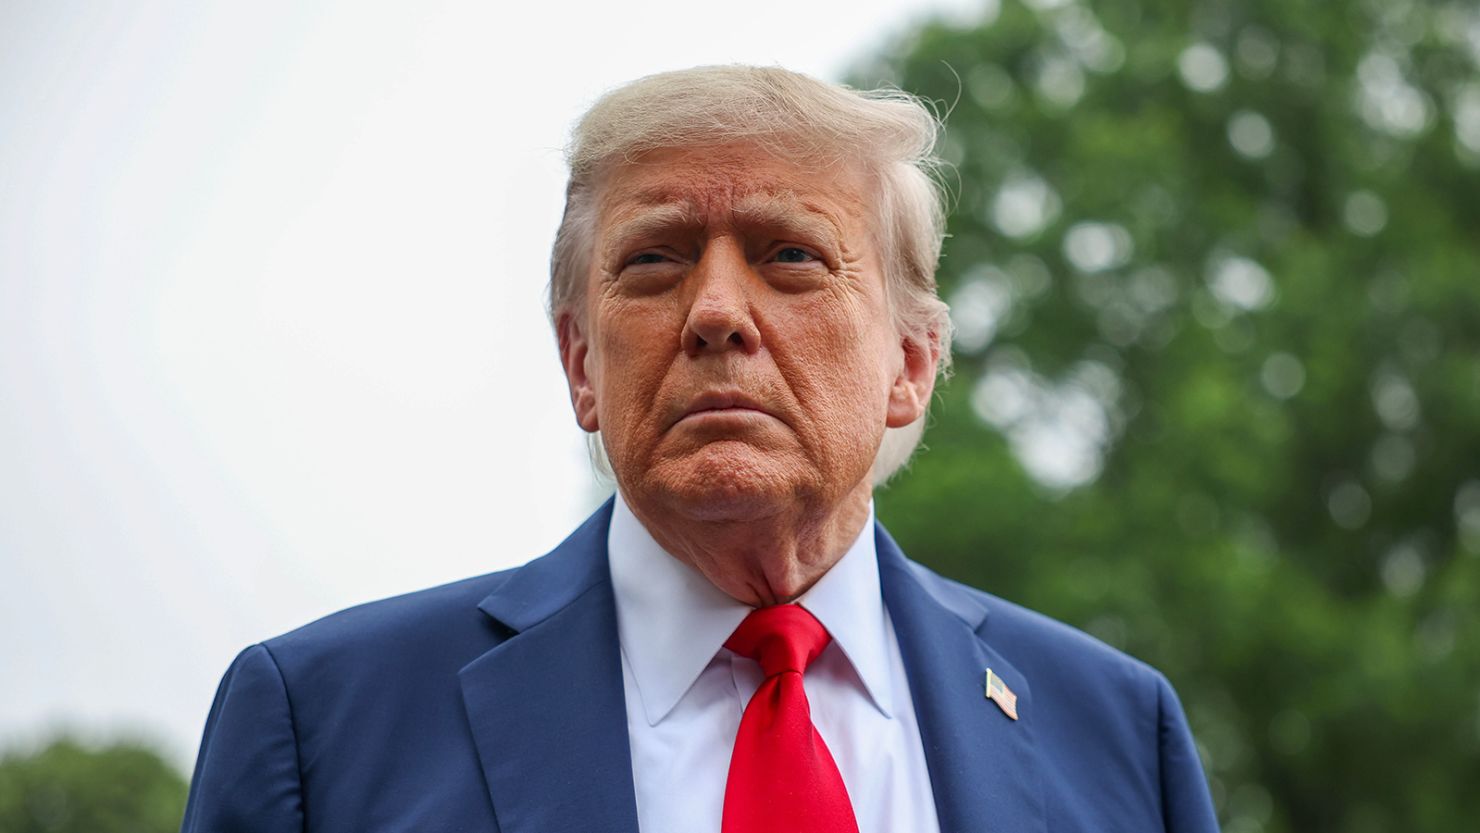
President Trump extended the Iran strike deadline to April 6 after Wall Street suffered its worst day since the conflict began. S&P 500 dropped 1.7%, Nasdaq entered correction, and 10-year Treasury yields spiked to 4.41% on fresh inflation fears. Full market analysis inside.
It was, by any measure, a signal moment—not in the Persian Gulf, where Iranian patrol boats continue to shadow tankers through the world’s most consequential maritime choke point, but on the floor of the New York Stock Exchange, where traders watched their screens with the kind of grim resignation usually reserved for hurricane landfalls.
At 4:00 p.m. Eastern time on Thursday, the numbers were final. The S&P 500 had fallen 1.7 percent, its worst single-day decline since January. The Nasdaq Composite had plunged 2.4 percent, pushing it more than 10 percent below its record high—a correction, in the clinical language of Wall Street, but in human terms something closer to a collective gut punch. The Dow Jones Industrial Average shed 469 points (Reuters).
Then, eleven minutes after the closing bell, President Donald Trump posted on Truth Social: Iran had asked for more time, and he was giving it. Ten more days. The new deadline for a deal to reopen the Strait of Hormuz—or face the destruction of Iran’s energy infrastructure—is now April 6 at 8:00 p.m. Eastern (Bloomberg).
“As per Iranian Government request,” Trump wrote, “please let this statement serve to represent that I am pausing the period of Energy Plant destruction by 10 Days” (Truth Social via Reuters). Talks, he insisted, were “going very well.”
The market, it seems, is not so sure.
What unfolded on Thursday was not merely a routine sell-off in response to geopolitical noise. It was something more revealing: a moment when investors, who had spent weeks parsing contradictory signals from Washington and Tehran, collectively concluded that the cost of uncertainty had become too high to carry. The extension that Trump framed as progress read to many on Wall Street as what it actually was—a punt, born of market panic, dressed up as diplomatic leverage.
Table of Contents
Why Wall Street Crashed: Inflation Fears Meet Iran Deadline Extension
To understand the carnage, one must go back to Saturday, when Trump first gave Iran 48 hours to reopen the Strait of Hormuz. The threat was existential for global energy markets: roughly 20 percent of the world’s oil passes through that narrow waterway, and Iran had effectively closed it since the U.S.-Israel bombing campaign began on February 28 (The Wall Street Journal).
By Monday, the president had already blinked once, extending the deadline to March 27 after Asian markets showed signs of distress. By Thursday, with U.S. stocks in freefall and the 10-year Treasury yield spiking to 4.41 percent—up eight basis points in a single session—he blinked again (Financial Times).
The numbers from Thursday’s session tell a story of broad-based capitulation. The Nasdaq’s 2.4 percent drop pushed it into correction territory, with technology giants taking the heaviest hits: Meta Platforms fell 7 percent, Nvidia slid 4 percent, and Alphabet dropped 3.4 percent (CNBC). The selling was indiscriminate, spanning sectors and market caps, a sign that the concern was systemic rather than sector-specific.
What spooked investors most was not the fighting itself—though that certainly didn’t help—but the collision of geopolitical escalation with stubborn inflation dynamics. Brent crude settled at $108.01 a barrel on Thursday, a 5.7 percent jump that brought its gain since the war began to nearly 50 percent (Bloomberg). West Texas Intermediate climbed 4.6 percent to $94.48.
For a market already skittish about the Federal Reserve’s next move, those oil prices are radioactive. The OECD warned Thursday that the Middle East crisis would push U.S. inflation to 4.2 percent this year, the highest among G7 nations (Reuters). That prospect effectively extinguishes any remaining hope for interest rate cuts in 2026—and raises the uncomfortable possibility that the Fed may have to resume hiking.
Treasury Yields Spike as Oil Volatility Returns
The bond market delivered its own verdict on Thursday, and it was brutal. The two-year Treasury yield, which is exquisitely sensitive to Fed policy expectations, jumped 10 basis points to 3.99 percent (Bloomberg). The 10-year yield touched 4.43 percent intraday before settling at 4.41 percent—a level not seen since the early weeks of the conflict.
What makes this yield spike particularly unsettling is what it signals about market psychology. Typically, geopolitical crises drive investors into the safety of U.S. government debt, pushing yields down. The fact that yields are rising instead suggests that inflation fears are overwhelming the traditional flight-to-quality impulse. Investors are not betting on Fed rescue; they are betting on Fed restraint, perhaps indefinitely.
“The market isn’t being erratic,” Steven Grey, chief investment officer at Grey Value Management, told the Financial Times. “This is what an efficient market looks like in the face of radical uncertainty” (Financial Times).
The radical uncertainty Grey refers to is not merely about whether the U.S. and Iran will reach a deal by April 6. It is about whether any deal is even possible, given the maximalist positions both sides have staked out.
Geopolitical Chess: What Trump’s 10-Day Pause Really Means for the Strait of Hormuz
For all the White House’s insistence that negotiations are proceeding smoothly, the reality on the ground is considerably messier. Iran’s Foreign Minister Abbas Araqchi made clear Wednesday that Tehran does not consider the message-swapping conducted through Pakistani intermediaries to constitute negotiation.
“Messages being conveyed through our friendly countries and us responding by stating our positions or issuing the necessary warnings is not called negotiation or dialogue,” Araqchi said (Reuters). “At present, our policy is to continue resistance and defend the country, and we have no intention of negotiating.”
The U.S. proposal delivered through Pakistan reportedly runs to 15 points and includes demands that Iran dismantle its nuclear program, curb its missile capabilities, and effectively cede control of the Strait of Hormuz (The Wall Street Journal). Iran’s counterproposal, according to regional sources, includes formal control of the strait, reparations from the U.S. and Israel, and guarantees against future military action (Al Jazeera).
These are not the positions of two sides approaching compromise. They are the positions of two sides preparing for a longer conflict, with diplomats working the back channels largely to manage escalation rather than to end it.
That assessment is reinforced by the military posture of the United States. Even as Trump extends diplomatic deadlines, the Pentagon is moving more troops into the region. Some 5,000 Marines are already being repositioned, and now an additional 1,000 soldiers from the 82nd Airborne Division are preparing to deploy, with reports suggesting the total could reach 10,000 (Associated Press).
The message to Tehran is contradictory: we want to talk, but we are also preparing to seize Kharg Island, Iran’s primary oil export terminal. Whether that contradiction reflects strategic coherence or improvisation is a question that markets are increasingly answering in the negative.
The “Toll Booth” and the Global Economy
Iran’s strategy in the strait has become clearer over the past week. Tehran is not merely blocking oil shipments; it is attempting to establish what one analyst described as a “toll booth” for tankers passing through Hormuz (Foreign Policy). Iranian patrol boats are stopping vessels, demanding fees, and allowing some to pass while detaining others.
Trump noted Thursday that Iran had allowed 10 Pakistan-flagged tankers through the strait, presenting this as evidence of progress (Reuters). But the selective passage is itself a form of control—a demonstration that Iran, not the United States, decides which ships move and which do not.
The economic impact of this arrangement is already visible. Global shipping insurance rates have spiked. Tanker operators are demanding premiums that reflect not just the risk of attack but the risk of arbitrary detention. And while Treasury Secretary Scott Bessent announced a U.S. insurance program to encourage shipping through the strait, it remains unclear whether private operators will accept coverage from a government that cannot guarantee safe passage (Bloomberg).
For the global economy, the stakes are enormous. Before the war, approximately 20 million barrels of oil passed through Hormuz daily—roughly 20 percent of world consumption. That flow has been reduced to a trickle, and the impact is being felt at gasoline pumps from Mumbai to Milan (International Energy Agency). In the United States, the national average price of gas is up more than a dollar from a month ago (AAA).
Economist’s View: Long-Term Market Risks Beyond April 6
For investors trying to position themselves for the weeks ahead, the key variable is not whether Trump extends the deadline again on April 6—though that remains a distinct possibility—but whether the underlying structural risks of the conflict are being priced correctly.
On that front, the market may still be underestimating the danger.
“Any sustainable market recovery will require meaningful progress toward a peace agreement and a reopening of the Strait of Hormuz,” Adam Turnquist at LPL Financial told Bloomberg (Bloomberg). That is the baseline condition. Without it, oil prices remain elevated, inflation expectations stay anchored higher, and the Fed remains locked in a hawkish stance.
Yet the conditions for a genuine peace agreement appear distant. Iran has hardened its position since the war began, demanding guarantees it would never have asked for before February 28. The United States, for its part, has committed to a posture of maximum pressure that leaves little room for the kind of face-saving compromises that typically end conflicts.
There is also the matter of trust—or the complete absence of it. The U.S. and Israel launched their initial strikes on February 28 in the middle of what were described as productive talks (The New York Times). Iran’s negotiators, to put it mildly, remember this.
“The current situation looks very similar, with markets positioning for a potential weekend escalation,” Kyle Rodda at Capital.com wrote in a note this week (Capital.com). That is the new normal: investors bracing for military action every Friday, only to recalibrate on Sunday night based on what actually happened.
Conclusion: A Market That Knows the Difference Between Postponement and Resolution
There is an old maxim on Wall Street that markets can climb walls of worry but cannot abide uncertainty. What the past week has demonstrated is that the Trump administration’s approach to the Iran crisis has created a wall of uncertainty so high and so opaque that even the most risk-tolerant investors are pulling back.
The 10-day extension to April 6 buys time, but it does not buy resolution. It allows the White House to avoid a market crisis in the immediate term while leaving every underlying problem—the closure of the strait, the inflationary pressure from high oil prices, the absence of a diplomatic framework—completely unresolved.
For the elite investors and policymakers who read this publication, the takeaway is not complicated. The Trump administration has shown that it will blink when markets demand it. That is a useful signal about the boundaries of policy, but it is not a solution. Until the Strait of Hormuz is genuinely reopened—not selectively, not conditionally, but fully—the risks to global markets remain asymmetrically tilted to the downside.
April 6 will come quickly. Whether it brings a breakthrough or merely another extension is anyone’s guess. But one thing is clear: the market is no longer waiting to find out. It is already pricing in the worst, and hoping, against evidence, to be proven wrong.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


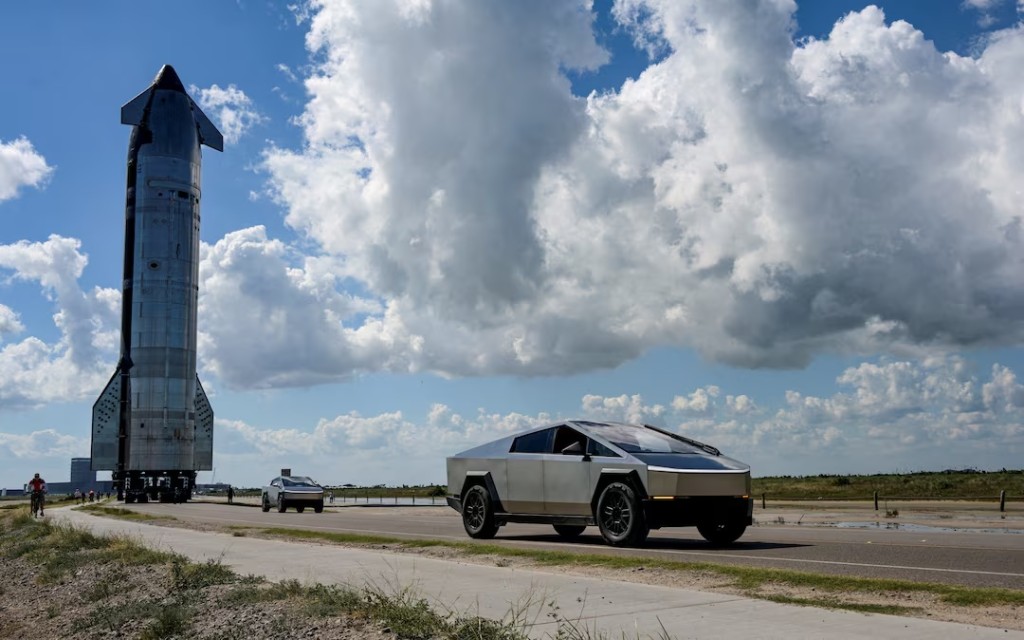
Three headlines about Elon Musk’s companies appeared to tell unrelated stories: a spectacular electric sports car, a possible corporate merger and growing dependence on satellite connectivity. Read together, they reveal a broader contest over capital, engineering and control of digital infrastructure.
The key is to separate announcements, proposals and operational results. A demonstrated vehicle capability is not a mass-production date. A corporate committee is not a completed merger. And satellite coverage is not the same as unrestricted service under every political or security condition.
Tesla Roadster: the spectacle and the schedule
Reuters reported in mid-October on a next-generation Tesla Roadster demonstration involving SpaceX-inspired thruster technology. The report also indicated that customer deliveries would not begin until 2028. The distinction between a prototype showcase and a product ready for buyers is the most important one for readers evaluating Tesla’s technology ambitions.
A dramatic unveiling can demonstrate engineering intent. What follows is less glamorous: homologation, manufacturing readiness, servicing plans, warranty commitments, cost control and repeatable performance in ordinary conditions. Prospective buyers should not treat estimated specifications or on-stage promises as final contract terms.
SpaceX–Tesla merger talks: possible is not agreed
Reuters reported on October 22 that a potential merger would require Musk’s approval, even as governance considerations complicated the discussion. Committees studying a deal have not, by themselves, established a price, transaction structure, regulatory clearance or shareholder outcome.
The strategic case is obvious to enthusiasts: electric vehicles, robotics, satellites, artificial intelligence and computing capacity might be marketed as a single integrated ecosystem. The drawbacks are equally serious. A conglomerate can obscure business-level performance, increase capital-allocation conflicts and make valuation harder. Directors and shareholders would need to scrutinise related-party interests and who benefits from any exchange ratio.
The less cinematic AI numbers
Reuters’ October earnings coverage described rapid revenue growth in SpaceX’s AI business alongside a sharp increase in capital spending. Investors should resist both extremes: dismissing all AI demand as hype or assuming revenue growth guarantees attractive free cash flow. Data-centre infrastructure needs chips, sites, power and expensive maintenance.
Fast revenue growth can coexist with high valuation risk. The test is whether new businesses eventually finance their own expansion while preserving adequate returns to capital providers.
Starlink’s national-security dilemma
Satellite networks promise resilience when terrestrial networks fail. They also create dependence on operators with technical control over service policies, access and availability. October reporting on Starlink and Ukraine highlighted how restrictions or changes in operational capability can acquire strategic significance. The Reuters account noted statements by Ukrainian officials about restored connectivity at high travel speeds; statements about the causes of earlier restrictions require careful attribution.
For governments and businesses, diversification may therefore matter almost as much as signal quality. Critical communications need backups, clear contracts and a plan for service interruption.
Five questions before believing the next Musk headline
| Claim | Verification test |
|---|---|
| A rocket or vehicle can perform a feat | Independent evidence of a completed demonstration |
| A car launches next year | Confirmed production, approvals and delivery schedule |
| Two companies are merging | Filed agreement, board and shareholder approvals |
| AI business is profitable | Cash flow, costs and credible segment disclosure |
| Satellite service is universally available | Licence, coverage, capacity and contractual terms |
Why the story matters outside the US
Pakistan and other emerging markets look to satellite broadband, low-cost electric technology and AI tools for development opportunities. They also face affordability, spectrum and regulatory questions. Importing a futuristic product is not a substitute for competition policy or infrastructure resilience.
Corporate governance will matter as much as engineering
A potential deal between companies closely associated with the same entrepreneur raises questions about valuation, conflicts and decision-making. Independent directors must consider whether each shareholder group receives fair treatment; enthusiasm for a shared brand is not a substitute for transaction terms. Investors should distinguish a serious formal proposal from a public comment about strategic possibilities.
There is also a different risk profile across the businesses involved. A vehicle manufacturer faces factory utilisation, safety recalls and consumer financing. A satellite operator depends on launch capabilities, spectrum arrangements, recurring subscriptions and government permissions. AI computing infrastructure adds yet another profile involving power costs, hardware replacement and contract concentration. Combining these enterprises does not make their underlying risks disappear.
For followers of the space programme, the next meaningful milestone is evidence of repeated operational success, not a promise that a future mission will use advanced recovery methods. For EV buyers, it is a firm delivery programme with defined specifications. For connectivity users, it is consistent service under known contractual conditions.
A restrained technology roundup can celebrate ambitious engineering while continuing to ask ordinary questions about reliability, costs and the institutions that oversee it.
Are Tesla and SpaceX already one company?
No. Reported discussions and committees do not establish a completed merger.
Does a Roadster prototype guarantee 2028 deliveries?
No. The announced timeline remains subject to production and regulatory realities.
Can Starlink replace every terrestrial telecom network?
No. It may be particularly valuable in hard-to-serve areas or emergencies, but capacity, cost and regulation still matter.
The overlooked theme: Musk’s ventures are increasingly connected by shared ambitions and capital demands. The more compelling editorial question is not what they can announce, but which promises can be delivered at scale and at a defensible cost.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
Global growth has proved harder to derail than many feared, but resilience is no longer evenly distributed. The IMF’s October 2026 World Economic Outlook projects 3.1% global real GDP growth this year and 3.4% in 2027. It also expects inflation to reach 4.7% in 2026 before easing to 4.1% next year. Those figures describe an expanding world economy, not a global recession. They also conceal a widening divide between technology-linked investment hubs and energy-importing developing countries.
The danger is not simply a weaker headline growth rate. It is that governments may respond to an uneven shock with blunt policy instruments: indiscriminate energy subsidies, abrupt fiscal austerity or interest-rate changes that neglect currency and inflation risks. The next phase of economic resilience will be determined by the quality of those choices.
Key takeaways
- Positive global growth masks divergent conditions across countries and industries.
- The AI investment cycle supports output but increases concentration and valuation risk.
- Energy prices transfer purchasing power from importers to producers and complicate monetary policy.
- High public debt makes apparently affordable short-term interventions expensive over time.
- For Pakistan and other import-dependent economies, targeted relief and durable export capacity are more valuable than headline stimulus.
The number that both reassures and misleads
The IMF’s 3.1% projection indicates that world output is still expanding in real terms. But an average cannot describe who bears the costs. A country hosting semiconductor investment may register a manufacturing upswing while an importing economy faces a higher fuel bill and constrained fiscal choices. Similarly, a profitable multinational can raise capital for data centres even when smaller firms struggle with borrowing costs.
The contrast also appears between different statistical frameworks. The UN Department of Economic and Social Affairs’ mid-2026 update forecast 2.5% global growth for 2026. That was a forecast published in May, using different assumptions and an earlier information set. It is not appropriate to present it as a contradiction that was settled by averaging the two figures. Readers should compare release dates, definitions and data cutoffs before drawing conclusions.
The October IMF forecast was prepared with statistical information available through October 1, according to the report. Even a recently published forecast cannot fully price in an unexpected military escalation or market shock afterward. Economic forecasts are conditional pictures of a changing landscape, not guarantees.
Three asymmetries shaping the world economy
Growth is concentrated in particular technologies
The WTO’s October trade update lifted its forecast of merchandise trade-volume growth to 3.9% for 2026, compared with 1.9% in March. Demand for AI-enabling goods helped offset disruptions in fuel and fertilizer trade. That is not a general statement that every exporter is thriving. It suggests that the composition of trade matters more than the direction of the global average.
The investment picture is similarly uneven. UNCTAD’s World Investment Report 2026 records a 6% rise in global foreign direct investment to $1.6 trillion in 2025, but says the recovery was concentrated. The 20 largest recipient economies attracted more than 80% of global inflows. A rebound in aggregate investment can coexist with a shortage of long-term capital where it is most needed.
Inflation hurts people and economies differently
Inflation is not one event experienced at the same intensity by everyone. A richer household may postpone a nonessential purchase; a lower-income household cannot postpone the need to eat or commute. An exporting fuel producer can benefit from a price spike while a developing economy paying for imported diesel loses foreign exchange and confronts an increase in domestic transport costs.
This distributional difference is precisely why the IMF’s 2026 World Economic Outlook places emphasis on temporary, targeted support during cost-of-living crises. The institution’s analysis finds that suppressing prices broadly can require several times the fiscal resources of targeted transfers. The political attraction of a universal subsidy is understandable; the budgetary opportunity cost can be punishing.
Financial resilience is not safety
The October Global Financial Stability Report warns about a possible correction in AI-related assets, rising sovereign yields and cyber incidents affecting financial infrastructure. Markets can remain calm for a long period while leverage, maturity mismatches or fiscal vulnerabilities accumulate underneath.
This distinction matters for sovereign borrowers. A government can refinance debt readily during a period of abundant risk appetite and then face sharply higher yields when investors reassess inflation or fiscal credibility. For an economy with substantial external obligations, volatility in international funding conditions can affect both public finances and private investment.
The economic transmission chain
| External shock | First transmission channel | Second-round consequence | Policy trade-off |
|---|---|---|---|
| Oil or diesel supply disruption | Import and freight costs rise | Inflation and weaker real incomes | Relief versus fiscal capacity |
| AI investment disappoints | Technology valuations weaken | Financing and equipment demand soften | Market support versus risk discipline |
| Sovereign yields rise | Debt refinancing costs increase | Less room for productive spending | Consolidation versus development |
| Tariff uncertainty rises | Supply chains and sourcing change | Investment delays and costlier inputs | Resilience versus efficiency |
| Tourism routes disrupted | Passenger flows and service earnings shift | Job and foreign-exchange losses | Security versus connectivity |
Original analytical framework; effects vary by country and timing.
A policymaker who sees only the first-round consequence may reach for the wrong remedy. A sudden oil price increase, for example, is not identical to excessive domestic demand. Higher interest rates can dampen inflation expectations and protect currency confidence, but they cannot create additional diesel. Conversely, a large untargeted subsidy may hide the visible rise in fuel prices while worsening public borrowing needs.
Why fiscal policy has become the decisive constraint
Governments entered this period with limited buffers. The IMF’s April 2026 Fiscal Monitor put global public debt at just under 94% of GDP in 2025 and projected it would reach 100% by 2029. An October IMF assessment of sovereign yields stressed that higher interest rates amplify fiscal pressure when debt is already elevated.
These are global debt measures, not a claim that every country shares the same balance-sheet risk. A reserve-currency government issuing long-term debt in its own money is in a different position from a frontier market with foreign-currency maturities. A sensible debt debate should therefore examine interest costs, maturity profiles, contingent liabilities and the credibility of future tax revenue—not debt-to-GDP in isolation.
A second question is the composition of fiscal adjustment. Cutting productive maintenance, basic education or disease prevention may improve a year’s reported deficit while damaging the economy’s long-run earning capacity. Credible consolidation should focus on inefficient spending and revenue leakage while preserving high-return public functions.
Asia and Pakistan: policy through the import bill
Energy-importing Asian economies face a dual challenge: fuel costs can rise as demand from major trading partners changes. Export manufacturing may benefit from stronger global goods trade, but the advantage is reduced when electricity and transport become more expensive. A successful strategy has to work on the export side and the import side together.
Pakistan illustrates the tension. An October 7 IMF statement estimated FY2025–26 real GDP growth at 3.6%, and reported gross reserves of around $21.5 billion at end-September. The Fund reached a staff-level agreement on program reviews, subject to Executive Board approval, not an unconditional disbursement. The statement also stressed energy-sector efficiency, taxation, reserves and targeted safety nets.
For Pakistan the policy logic is sequential. First, preserve macroeconomic credibility so price and exchange-rate signals remain useful. Second, protect vulnerable people with instruments designed around need rather than petrol consumption. Third, reduce energy-system losses and logistics frictions that prevent domestic producers from capitalizing on global trade opportunities. Fourth, raise skills and reliability in sectors capable of earning foreign exchange.
The same logic applies, with different institutional arrangements, to many countries across South Asia and Southeast Asia. A temporary commodity boom should not be mistaken for structural competitiveness; a temporary fuel shock should not become an excuse for permanent distortionary subsidies.
Four choices that cannot be postponed
Choose targeted protection over universal price freezes. Distributional relief should reach people most exposed to higher food, transport and electricity costs. That requires social registries, payment systems and transparent eligibility criteria. When assistance is untargeted, larger consumers often capture more of the financial benefit.
Choose investment quality over investment headlines. Data-centre announcements, industrial incentives and infrastructure projects are not equally valuable. Governments should ask how much domestic employment, export capacity, grid improvement and knowledge transfer each generates after subsidies and public guarantees are counted.
Choose diversified trade over tariff reflexes. Supply-chain resilience sometimes justifies redundant capacity, but permanent protection can also shelter unproductive firms. The relevant test is whether a measure lowers the expected total cost of disruption without becoming an open-ended subsidy to inefficiency.
Choose credible gradual reform over abrupt announcements. A clear medium-term fiscal and monetary path allows firms to plan capital expenditure, wages and hiring. Repeated reversals can raise the risk premium even when the immediate measure appears pro-business.
Risks, limitations and what would change the outlook
The outlook could improve if energy flows normalize, AI investment produces broad productivity gains and trade tensions ease. It could deteriorate if conflict escalates, financing costs rise or investors reassess the expected profitability of AI infrastructure. No single model can assign reliable probabilities to each geopolitical pathway. Differences between IMF and UN growth forecasts also caution against false precision.
The signals to follow are the composition of WTO trade growth; oil-product availability rather than only crude benchmarks; long-term sovereign yields; new FDI projects outside leading recipient countries; and whether real wages improve after inflation. Household welfare is the ultimate test of resilience, not the absence of recession headlines.
Frequently asked questions
Is the global economy in recession in 2026?
The IMF baseline still projects positive world output growth of 3.1% for 2026. Individual economies or sectors may nonetheless contract.
What does resilience under strain mean?
It means overall economic activity continues expanding, but the supporting conditions are increasingly unequal and vulnerable to financial, energy and geopolitical shocks.
Why can global trade grow faster than global GDP?
Trade volumes can be lifted by particular categories—such as AI-related equipment—even when domestic services and consumption in other economies are subdued.
Why are broad fuel subsidies risky?
They can be costly, may benefit larger consumers disproportionately and can reduce funds available for targeted social protection and infrastructure.
Does the IMF’s Pakistan staff-level agreement mean funds have already arrived?
No. Its October 7 announcement explicitly says implementation is conditional on Executive Board approval.
Which measure should households follow?
Real income—income adjusted for inflation—along with reliable employment, transport and food costs provides a more useful picture than global GDP alone.
Conclusion
Resilience is not the ability to ignore danger; it is the capacity to absorb shocks without sacrificing the foundations of future growth. In 2026 the world remains economically active, but benefits are concentrated and buffers are strained. Governments that preserve targeted social support, rebuild fiscal credibility and invest in productivity will emerge stronger than those that mistake a positive growth figure for proof of economic security.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
October is Major League Baseball’s postseason month, with the League Championship Series leading toward the World Series. MLB’s official October 9 update listed league championship broadcasting arrangements and said its complete postseason schedule was subject to change. That is the appropriate basis for a service article, rather than relying on viral bracket graphics. Sources: MLB and NBA.
The important context competitors can overlook
The playoff path moves through the Wild Card Series, Division Series, League Championship Series and World Series. Series lengths differ, affecting travel planning, pitching strategies and when a potential deciding game may occur. Weather, broadcast adjustments and series ending early can all change the actual date of a matchup. A guide should therefore distinguish tentative “if necessary” games from guaranteed events. For primary-source checks and current reporting, see MLB and NFL. The key distinction is practical broadcast and bracket explainer with no fictitious results.
October baseball moves through elimination series toward the World Series. Games marked ‘if necessary’ depend on earlier series results. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
Use MLB’s live bracket and broadcast information for tonight’s specific matchup, while this article provides the enduring format explanation. If publishing a result, record the completed date and source. Viewers should check the network, streaming eligibility and local restrictions before paying. Avoid declaring future participants or game outcomes without an official final score.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Where is the authoritative 2026 playoff schedule? MLB publishes and updates it at MLB.com/postseason.
Why are some dates marked if necessary? Best-of-series matchups end once a team wins the required number of games.
How the MLB postseason bracket works
Major League Baseball’s postseason includes division winners and wild-card teams, followed by a sequence of elimination series that eventually determines each league champion and the World Series participants. The rounds use different series lengths; that affects pitching strategy, bullpen workload and how quickly a team can be eliminated. A single-game result in a best-of-series contest is important but not always decisive. Readers should consult MLB’s official postseason hub for the bracket rather than rely on an old graphic that may not reflect completed games.
Home-field advantage, seeding and tiebreaking rules add context to the matchup schedule. Those details can vary by competition edition, so the official rules should be checked instead of recycled from a prior year. When a postseason series has not yet finished, the next opponent remains conditional. An article should say “winner of Series A will face…” rather than assign a future opponent before the result exists.
Why starting pitching changes a short series
Starting pitchers often shape the first half of a game, but playoff success requires bullpen management, defense, baserunning and timely hitting. A team may start its most experienced pitcher in the first game and then adjust the rotation based on rest, health and earlier results. Managers must also decide when to use their strongest relief pitchers. Those choices can matter more in a short series than in a long regular season where roles and workloads can be smoothed across many games.
Baseball statistics need sample-size discipline. A hitter’s performance over ten postseason plate appearances tells less about underlying ability than a much longer period of play. Analysts can compare strikeout rates, on-base production and matchup tendencies while avoiding exaggerated claims drawn from one home run or one defensive error. Recent injuries and announced starting lineups can change the outlook quickly.
Broadcast rights and local time differences
A game carried by a U.S. broadcaster may require a different provider for an international audience. Some streaming services include blackout restrictions and authenticated subscriptions. Before directing readers to a platform, check the league’s official listing for the game, region and date. A schedule can shift because of series outcomes or weather; do not assume every potential Game 6 or Game 7 will occur. Conditional games should be clearly labeled so viewers do not subscribe or travel based on a nonexistent fixture.
Fans outside North America should verify dates carefully. A game beginning late at night in U.S. Eastern Time can appear on the following morning in Pakistan or elsewhere. A credible global article uses time-zone labeling and, where practical, provides local conversions while directing readers to official confirmations.
Planning a trip to a postseason game
Buy tickets through the team’s verified ticket office or a recognized authorized resale route. Read what happens to a ticket for an “if necessary” game that is never played. Lodging and transportation may be nonrefundable even when the ticket itself is refunded under a particular policy. Stadium entry rules, bag restrictions and transport can vary by venue. Travel budgets should include potential schedule shifts, especially when the identity of the next opponent is not yet known.
Reseller offers that look dramatically cheaper than the going rate can be fraudulent. Confirm seat location, transfer method and the platform’s buyer-protection terms. Never assume an image of a barcode sent by a stranger proves a usable ticket. The simplest defense is to purchase through verified channels and retain the order record.
A bracket-tracking method that stays accurate
For each series, maintain the teams, seeds, current games-won tally, next confirmed game time, probable or announced starters, broadcaster and a direct MLB link. Update each row only after official results. Distinguish “clinched” from “leads series.” If a matchup concludes earlier than its maximum length, remove unused dates or mark them canceled; otherwise a static editorial calendar can appear inaccurate within hours.
The purpose of a postseason guide is not to predict every winner. It is to make a fast-moving bracket understandable and give fans reliable answers on what happens next, where to watch and which details remain uncertain.
Baseball postseason questions answered
Does every potential game on a postseason schedule occur?
No. A best-of-seven series ends when one team reaches four wins. Games listed as “if necessary” do not take place if the series has already been decided. Ticket buyers and travelers should understand refund or cancellation policies associated with those conditional dates before arranging flights and hotels.
Why do playoff teams use pitchers differently?
A shorter series changes the cost of saving an elite relief pitcher or spacing starting assignments. Managers may make aggressive substitutions to protect a narrow lead, while maintaining enough arms for a possible next game. Such choices can look different from regular-season strategy, when teams plan around a longer schedule and broader workload management.
Can a postseason match move after its first announcement?
Yes. Broadcast planning, prior series results and circumstances such as weather can affect schedules. MLB’s official game page and league notices should be checked shortly before travel or viewing. An editorial table that fails to update conditional games can easily mislead readers as the bracket advances.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Tesla, SpaceX and Starlink: The Real Business Story Behind Elon Musk’s October Buzz

Resilience Under Strain: The World’s Difficult 2026 Choices

Andy Harris in 2026: Freedom Caucus Influence, Spending and Congressional Power

MLB Playoffs 2026: Postseason Format, Broadcast Guide and How to Track the Bracket

Elon Musk Calls Mukesh Ambani the “Real Boss of India” Over Alleged Monopoly Concerns

Legal Pioneer and Defender of Justice: The Life, Works, and Legacy of Navi Pillay

Inside the Modern Republican Party Platform: Tax Policy, Immigration, and Governance

Anne Carson: Genius of Hybrid Forms and 2026 Nobel Laureate in Literature

Analyzing the Republican Voter Enthusiasm Gap: Turnout Metrics and Polling Data
Analyzing the Republican Voter Enthusiasm Gap: Turnout Metrics and Polling Data
Inside the Modern Republican Party Platform: Tax Policy, Immigration, and Governance
Anne Carson: Genius of Hybrid Forms and 2026 Nobel Laureate in Literature
Resilience Under Strain: The World’s Difficult 2026 Choices
Elon Musk Calls Mukesh Ambani the “Real Boss of India” Over Alleged Monopoly Concerns
Andy Harris in 2026: Freedom Caucus Influence, Spending and Congressional Power
MLB Playoffs 2026: Postseason Format, Broadcast Guide and How to Track the Bracket
Legal Pioneer and Defender of Justice: The Life, Works, and Legacy of Navi Pillay
Tesla, SpaceX and Starlink: The Real Business Story Behind Elon Musk’s October Buzz
-

 Featured6 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Democracy5 years ago
Missing You! SPSC
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day