Analysis
The Digital Trojan Horse: Why Trump Is Using Stablecoins to Save the Dollar (And Why It Might Backfire) 💰

The world is ditching the dollar. China, the BRICS nations, everyone’s looking for the exit. We hear the warnings constantly: de-dollarisation is the slow, grinding threat to American supremacy. But instead of hiking rates or cutting debt, Donald Trump’s team has unveiled a surprising, counter-intuitive weapon: stablecoins.
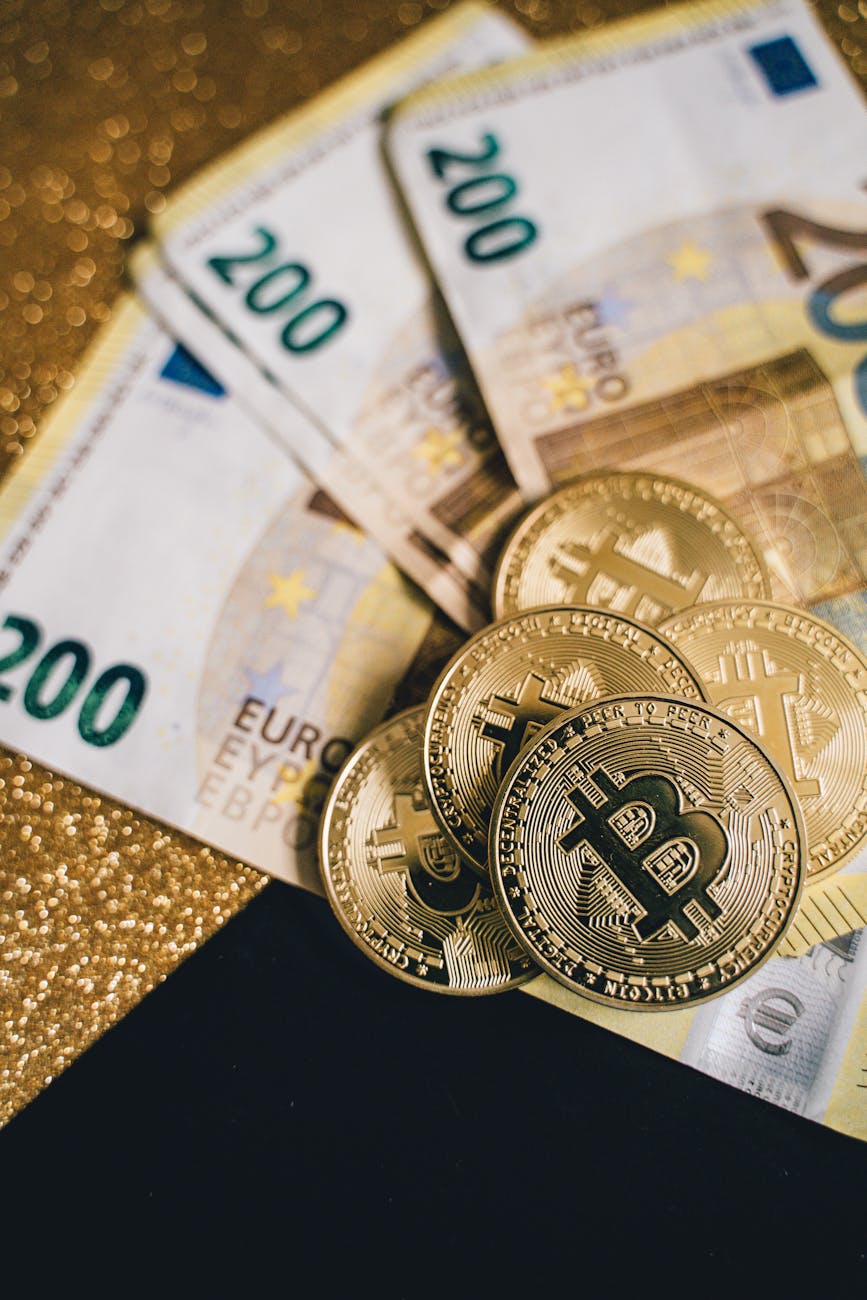
It’s a high-stakes, geopolitical bet on code and commerce. The administration is executing a calculated bet on private digital assets—specifically dollar-pegged stablecoins like USD Coin (USDC) and Tether (USDT)—to digitally extend dollar hegemony globally. It’s a strategy to beat China’s digital yuan and neutralize the dollar’s rivals, but the risks to our own financial stability and the global banking system are massive.
This isn’t some fringe idea; it’s official policy, codified in the GENIUS Act signed by the President in July 2025. Treasury Secretary Scott Bessent has been clear, stating the administration will “use stablecoins to do that” when referring to maintaining the dollar’s dominance globally. The plan is brilliant, aggressive, and perfectly tailored to the “America First” ethos. Yet, the very financial innovation it champions could ultimately act as a digital Trojan Horse, smuggling systemic dangers into the U.S. financial system.
Table of Contents
A Digital Extension of Dollar Hegemony: The Treasury Bond Loop
The genius of this strategy lies in its two-part mechanism, which uses the private sector’s demand for the dollar to serve the government’s geopolitical aims. The Trump team isn’t trying to force the dollar onto the world; they’re making it the most irresistible digital currency option.
1. Global Reach: Re-Dollarisation from the Bottom Up
For millions in emerging markets—from Argentina to Nigeria—the U.S. dollar is the only reliable store of value. However, getting those dollars is expensive, slow, and often requires circumvention of local capital controls.
Stablecoins solve this problem instantly. They are, in essence, digital dollar banknotes available 24/7, accessible with nothing more than a smartphone. The GENIUS Act provides a clear regulatory framework for these tokens, signaling global users that U.S.-regulated stablecoins are safe. This accelerates “re-dollarisation” by the people, making the dollar the default currency for cross-border remittances and local saving, independent of foreign governments. It’s a massive, spontaneous global adoption campaign for the global reserve currency.
2. The Perpetual Treasury Demand
This is where the monetary policy meets the geopolitical. The GENIUS Act mandates that permitted stablecoin issuers must maintain one-to-one reserves in “ultra-safe and highly liquid assets,” primarily short-term US Treasuries and cash equivalents.
Every new dollar of USDC or Tether (USDT) issued globally now translates directly into a new buyer of American government debt. With the stablecoin market expected to soar into the trillions, this creates a perpetual, massive, foreign-funded demand for US Treasuries. In an era of record-high U.S. debt and weakening foreign interest, this structural demand is a powerful tool to maintain the dollar’s strength and keep borrowing costs low. It’s dollar diplomacy financed by private tech.
The Team and The Political Narrative
This aggressive posture is driven by a small, influential circle of policymakers and political operators.
Treasury Secretary Scott Bessent and Federal Reserve Governor Christopher Waller have been the most prominent public cheerleaders. Waller, for his part, has argued that the expansion of dollar-pegged stablecoins in the DeFi space is likely to reinforce the dominant role of the dollar rather than challenge it.
Crucially, this stablecoin strategy is diametrically opposed to the route taken by China and the EU. The Trump team explicitly favors private digital assets and has signed a sweeping Central Bank Digital Currency (CBDC) ban. This isn’t just policy; it’s a statement: the government won’t innovate; it will regulate, enable, and co-opt the private sector’s financial innovation for national gain.
Perhaps the most potent symbol of this revolving door is the story of Bo Hines. The former executive director of the White House Crypto Council, instrumental in advancing the GENIUS Act, resigned his post only weeks before joining the stablecoin giant Tether as a strategic advisor. This move—the architect of the policy moving directly to the most significant beneficiary—frames the entire strategy as a seamless public-private partnership aimed at entrenching the interests of both “Big Dollar” and “Big Crypto.”
The Dark Side: Systemic Risks and the Banking Threat (The Opinion)
Here’s where the digital Trojan Horse analogy becomes terrifyingly real. The same mechanism that strengthens the dollar globally creates a fierce threat to the banking system domestically.
The primary conflict is over deposits. Banks rely on low-cost savings deposits to fund mortgages and business loans. If consumers and institutions decide to move hundreds of billions of dollars from traditional, insured bank savings accounts into the stablecoin ecosystem, it constitutes a massive deposit flight. Analysts project that an increase in stablecoins could reduce bank deposits by 10% or more, dramatically impacting banks’ cost of funds and their ability to lend. This potentially starves local banks of capital, reducing their lending capacity, and increasing the threat to the banking system.
The second danger is the systemic risk to the US Treasuries market itself.
The paradox is cruel: the stablecoin reserve requirement—the policy’s biggest strength—is also its biggest weakness. If the stablecoin market, now heavily reliant on US Treasuries, were to suffer a crisis of confidence, it could trigger a “digital run.” Issuers would be forced to liquidate hundreds of billions of dollars in their Treasury reserves instantly to meet redemptions. Such a sudden, massive fire sale could destabilize the entire short-term US Treasuries market, one of the cornerstones of global finance.
The Final Verdict: A Geopolitical Masterstroke with Domestic Costs
The Trump team’s embrace of Trump stablecoins is a brilliant, aggressive, and necessary move to counter the rising tides of de-dollarisation. It’s America playing offense in the digital currency wars, using its best financial asset—the stability and network effect of the dollar—and pairing it with the private sector’s financial innovation.
It’s a masterstroke of economic statecraft, but we must understand the cost. We are strengthening the dollar’s grip on the world at the risk of creating a new, volatile, private shadow banking system right here at home. We are trading long-term geopolitical security for immediate domestic financial volatility.
That is the digital Trojan Horse the next administration, regardless of party, will inherit. The stablecoins are already inside the gates. The question isn’t whether they’ll save the dollar, but who gets trampled in the charge.
The administration’s focus on private digital assets like stablecoins is a defining feature of their digital finance strategy, as discussed in this Stablecoins will strengthen US dollar as a reserve currency video explaining the impact of this policy goal.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


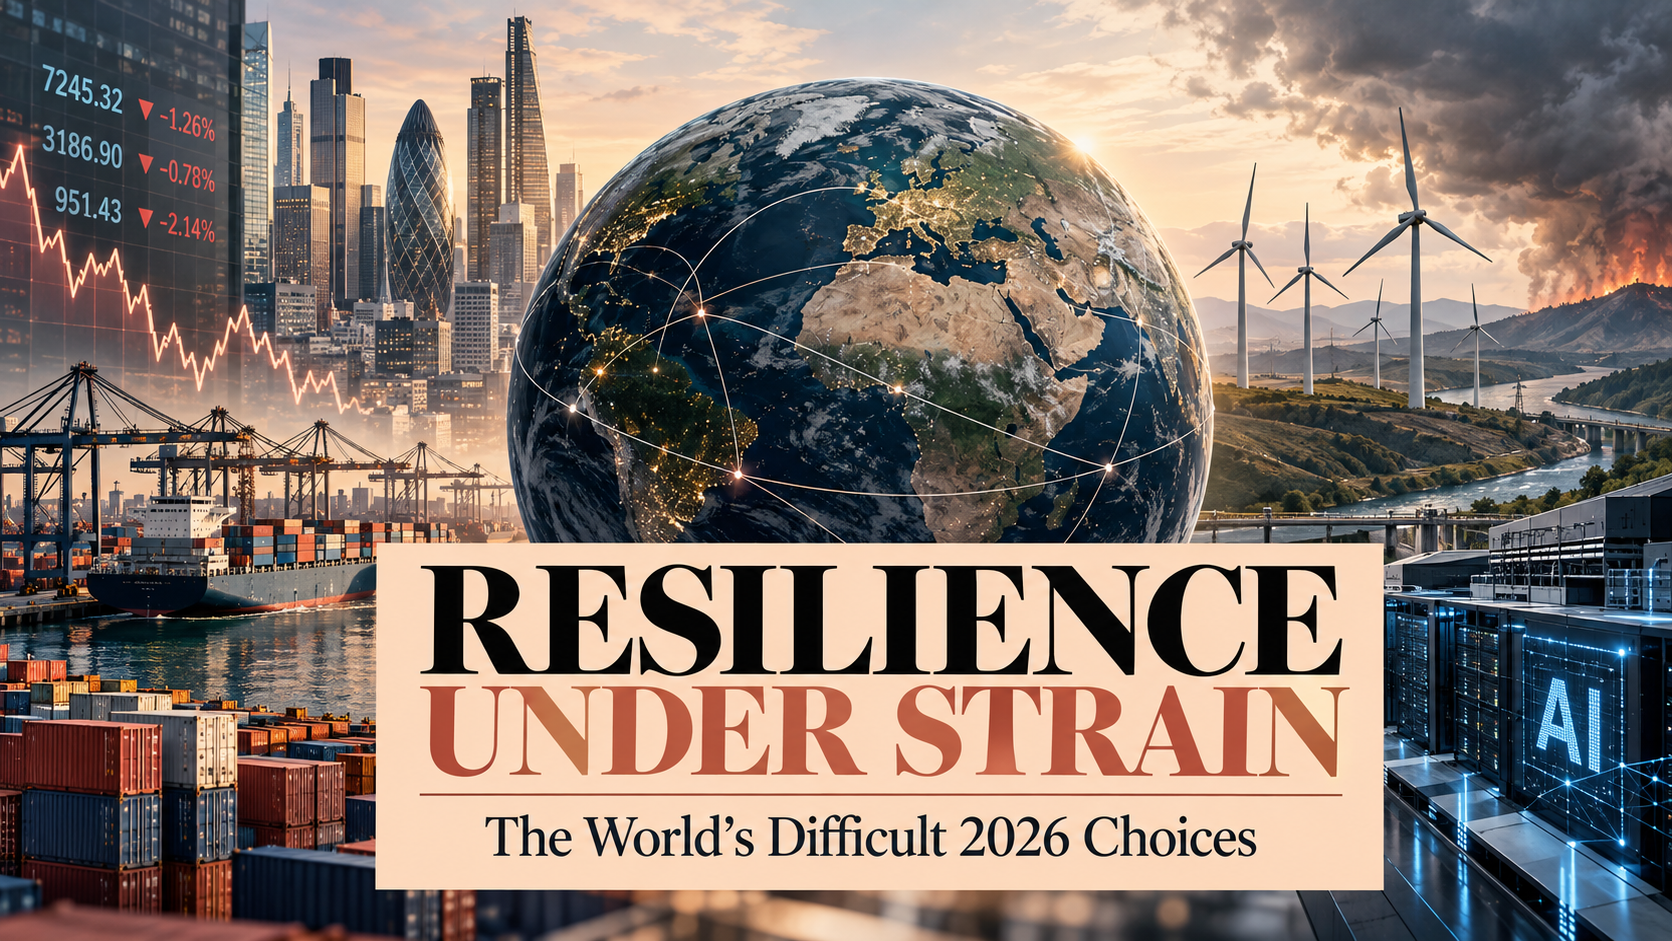
Global growth has proved harder to derail than many feared, but resilience is no longer evenly distributed. The IMF’s October 2026 World Economic Outlook projects 3.1% global real GDP growth this year and 3.4% in 2027. It also expects inflation to reach 4.7% in 2026 before easing to 4.1% next year. Those figures describe an expanding world economy, not a global recession. They also conceal a widening divide between technology-linked investment hubs and energy-importing developing countries.
The danger is not simply a weaker headline growth rate. It is that governments may respond to an uneven shock with blunt policy instruments: indiscriminate energy subsidies, abrupt fiscal austerity or interest-rate changes that neglect currency and inflation risks. The next phase of economic resilience will be determined by the quality of those choices.
Key takeaways
- Positive global growth masks divergent conditions across countries and industries.
- The AI investment cycle supports output but increases concentration and valuation risk.
- Energy prices transfer purchasing power from importers to producers and complicate monetary policy.
- High public debt makes apparently affordable short-term interventions expensive over time.
- For Pakistan and other import-dependent economies, targeted relief and durable export capacity are more valuable than headline stimulus.
The number that both reassures and misleads
The IMF’s 3.1% projection indicates that world output is still expanding in real terms. But an average cannot describe who bears the costs. A country hosting semiconductor investment may register a manufacturing upswing while an importing economy faces a higher fuel bill and constrained fiscal choices. Similarly, a profitable multinational can raise capital for data centres even when smaller firms struggle with borrowing costs.
The contrast also appears between different statistical frameworks. The UN Department of Economic and Social Affairs’ mid-2026 update forecast 2.5% global growth for 2026. That was a forecast published in May, using different assumptions and an earlier information set. It is not appropriate to present it as a contradiction that was settled by averaging the two figures. Readers should compare release dates, definitions and data cutoffs before drawing conclusions.
The October IMF forecast was prepared with statistical information available through October 1, according to the report. Even a recently published forecast cannot fully price in an unexpected military escalation or market shock afterward. Economic forecasts are conditional pictures of a changing landscape, not guarantees.
Three asymmetries shaping the world economy
Growth is concentrated in particular technologies
The WTO’s October trade update lifted its forecast of merchandise trade-volume growth to 3.9% for 2026, compared with 1.9% in March. Demand for AI-enabling goods helped offset disruptions in fuel and fertilizer trade. That is not a general statement that every exporter is thriving. It suggests that the composition of trade matters more than the direction of the global average.
The investment picture is similarly uneven. UNCTAD’s World Investment Report 2026 records a 6% rise in global foreign direct investment to $1.6 trillion in 2025, but says the recovery was concentrated. The 20 largest recipient economies attracted more than 80% of global inflows. A rebound in aggregate investment can coexist with a shortage of long-term capital where it is most needed.
Inflation hurts people and economies differently
Inflation is not one event experienced at the same intensity by everyone. A richer household may postpone a nonessential purchase; a lower-income household cannot postpone the need to eat or commute. An exporting fuel producer can benefit from a price spike while a developing economy paying for imported diesel loses foreign exchange and confronts an increase in domestic transport costs.
This distributional difference is precisely why the IMF’s 2026 World Economic Outlook places emphasis on temporary, targeted support during cost-of-living crises. The institution’s analysis finds that suppressing prices broadly can require several times the fiscal resources of targeted transfers. The political attraction of a universal subsidy is understandable; the budgetary opportunity cost can be punishing.
Financial resilience is not safety
The October Global Financial Stability Report warns about a possible correction in AI-related assets, rising sovereign yields and cyber incidents affecting financial infrastructure. Markets can remain calm for a long period while leverage, maturity mismatches or fiscal vulnerabilities accumulate underneath.
This distinction matters for sovereign borrowers. A government can refinance debt readily during a period of abundant risk appetite and then face sharply higher yields when investors reassess inflation or fiscal credibility. For an economy with substantial external obligations, volatility in international funding conditions can affect both public finances and private investment.
The economic transmission chain
| External shock | First transmission channel | Second-round consequence | Policy trade-off |
|---|---|---|---|
| Oil or diesel supply disruption | Import and freight costs rise | Inflation and weaker real incomes | Relief versus fiscal capacity |
| AI investment disappoints | Technology valuations weaken | Financing and equipment demand soften | Market support versus risk discipline |
| Sovereign yields rise | Debt refinancing costs increase | Less room for productive spending | Consolidation versus development |
| Tariff uncertainty rises | Supply chains and sourcing change | Investment delays and costlier inputs | Resilience versus efficiency |
| Tourism routes disrupted | Passenger flows and service earnings shift | Job and foreign-exchange losses | Security versus connectivity |
Original analytical framework; effects vary by country and timing.
A policymaker who sees only the first-round consequence may reach for the wrong remedy. A sudden oil price increase, for example, is not identical to excessive domestic demand. Higher interest rates can dampen inflation expectations and protect currency confidence, but they cannot create additional diesel. Conversely, a large untargeted subsidy may hide the visible rise in fuel prices while worsening public borrowing needs.
Why fiscal policy has become the decisive constraint
Governments entered this period with limited buffers. The IMF’s April 2026 Fiscal Monitor put global public debt at just under 94% of GDP in 2025 and projected it would reach 100% by 2029. An October IMF assessment of sovereign yields stressed that higher interest rates amplify fiscal pressure when debt is already elevated.
These are global debt measures, not a claim that every country shares the same balance-sheet risk. A reserve-currency government issuing long-term debt in its own money is in a different position from a frontier market with foreign-currency maturities. A sensible debt debate should therefore examine interest costs, maturity profiles, contingent liabilities and the credibility of future tax revenue—not debt-to-GDP in isolation.
A second question is the composition of fiscal adjustment. Cutting productive maintenance, basic education or disease prevention may improve a year’s reported deficit while damaging the economy’s long-run earning capacity. Credible consolidation should focus on inefficient spending and revenue leakage while preserving high-return public functions.
Asia and Pakistan: policy through the import bill
Energy-importing Asian economies face a dual challenge: fuel costs can rise as demand from major trading partners changes. Export manufacturing may benefit from stronger global goods trade, but the advantage is reduced when electricity and transport become more expensive. A successful strategy has to work on the export side and the import side together.
Pakistan illustrates the tension. An October 7 IMF statement estimated FY2025–26 real GDP growth at 3.6%, and reported gross reserves of around $21.5 billion at end-September. The Fund reached a staff-level agreement on program reviews, subject to Executive Board approval, not an unconditional disbursement. The statement also stressed energy-sector efficiency, taxation, reserves and targeted safety nets.
For Pakistan the policy logic is sequential. First, preserve macroeconomic credibility so price and exchange-rate signals remain useful. Second, protect vulnerable people with instruments designed around need rather than petrol consumption. Third, reduce energy-system losses and logistics frictions that prevent domestic producers from capitalizing on global trade opportunities. Fourth, raise skills and reliability in sectors capable of earning foreign exchange.
The same logic applies, with different institutional arrangements, to many countries across South Asia and Southeast Asia. A temporary commodity boom should not be mistaken for structural competitiveness; a temporary fuel shock should not become an excuse for permanent distortionary subsidies.
Four choices that cannot be postponed
Choose targeted protection over universal price freezes. Distributional relief should reach people most exposed to higher food, transport and electricity costs. That requires social registries, payment systems and transparent eligibility criteria. When assistance is untargeted, larger consumers often capture more of the financial benefit.
Choose investment quality over investment headlines. Data-centre announcements, industrial incentives and infrastructure projects are not equally valuable. Governments should ask how much domestic employment, export capacity, grid improvement and knowledge transfer each generates after subsidies and public guarantees are counted.
Choose diversified trade over tariff reflexes. Supply-chain resilience sometimes justifies redundant capacity, but permanent protection can also shelter unproductive firms. The relevant test is whether a measure lowers the expected total cost of disruption without becoming an open-ended subsidy to inefficiency.
Choose credible gradual reform over abrupt announcements. A clear medium-term fiscal and monetary path allows firms to plan capital expenditure, wages and hiring. Repeated reversals can raise the risk premium even when the immediate measure appears pro-business.
Risks, limitations and what would change the outlook
The outlook could improve if energy flows normalize, AI investment produces broad productivity gains and trade tensions ease. It could deteriorate if conflict escalates, financing costs rise or investors reassess the expected profitability of AI infrastructure. No single model can assign reliable probabilities to each geopolitical pathway. Differences between IMF and UN growth forecasts also caution against false precision.
The signals to follow are the composition of WTO trade growth; oil-product availability rather than only crude benchmarks; long-term sovereign yields; new FDI projects outside leading recipient countries; and whether real wages improve after inflation. Household welfare is the ultimate test of resilience, not the absence of recession headlines.
Frequently asked questions
Is the global economy in recession in 2026?
The IMF baseline still projects positive world output growth of 3.1% for 2026. Individual economies or sectors may nonetheless contract.
What does resilience under strain mean?
It means overall economic activity continues expanding, but the supporting conditions are increasingly unequal and vulnerable to financial, energy and geopolitical shocks.
Why can global trade grow faster than global GDP?
Trade volumes can be lifted by particular categories—such as AI-related equipment—even when domestic services and consumption in other economies are subdued.
Why are broad fuel subsidies risky?
They can be costly, may benefit larger consumers disproportionately and can reduce funds available for targeted social protection and infrastructure.
Does the IMF’s Pakistan staff-level agreement mean funds have already arrived?
No. Its October 7 announcement explicitly says implementation is conditional on Executive Board approval.
Which measure should households follow?
Real income—income adjusted for inflation—along with reliable employment, transport and food costs provides a more useful picture than global GDP alone.
Conclusion
Resilience is not the ability to ignore danger; it is the capacity to absorb shocks without sacrificing the foundations of future growth. In 2026 the world remains economically active, but benefits are concentrated and buffers are strained. Governments that preserve targeted social support, rebuild fiscal credibility and invest in productivity will emerge stronger than those that mistake a positive growth figure for proof of economic security.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
October is Major League Baseball’s postseason month, with the League Championship Series leading toward the World Series. MLB’s official October 9 update listed league championship broadcasting arrangements and said its complete postseason schedule was subject to change. That is the appropriate basis for a service article, rather than relying on viral bracket graphics. Sources: MLB and NBA.
The important context competitors can overlook
The playoff path moves through the Wild Card Series, Division Series, League Championship Series and World Series. Series lengths differ, affecting travel planning, pitching strategies and when a potential deciding game may occur. Weather, broadcast adjustments and series ending early can all change the actual date of a matchup. A guide should therefore distinguish tentative “if necessary” games from guaranteed events. For primary-source checks and current reporting, see MLB and NFL. The key distinction is practical broadcast and bracket explainer with no fictitious results.
October baseball moves through elimination series toward the World Series. Games marked ‘if necessary’ depend on earlier series results. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
Use MLB’s live bracket and broadcast information for tonight’s specific matchup, while this article provides the enduring format explanation. If publishing a result, record the completed date and source. Viewers should check the network, streaming eligibility and local restrictions before paying. Avoid declaring future participants or game outcomes without an official final score.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Where is the authoritative 2026 playoff schedule? MLB publishes and updates it at MLB.com/postseason.
Why are some dates marked if necessary? Best-of-series matchups end once a team wins the required number of games.
How the MLB postseason bracket works
Major League Baseball’s postseason includes division winners and wild-card teams, followed by a sequence of elimination series that eventually determines each league champion and the World Series participants. The rounds use different series lengths; that affects pitching strategy, bullpen workload and how quickly a team can be eliminated. A single-game result in a best-of-series contest is important but not always decisive. Readers should consult MLB’s official postseason hub for the bracket rather than rely on an old graphic that may not reflect completed games.
Home-field advantage, seeding and tiebreaking rules add context to the matchup schedule. Those details can vary by competition edition, so the official rules should be checked instead of recycled from a prior year. When a postseason series has not yet finished, the next opponent remains conditional. An article should say “winner of Series A will face…” rather than assign a future opponent before the result exists.
Why starting pitching changes a short series
Starting pitchers often shape the first half of a game, but playoff success requires bullpen management, defense, baserunning and timely hitting. A team may start its most experienced pitcher in the first game and then adjust the rotation based on rest, health and earlier results. Managers must also decide when to use their strongest relief pitchers. Those choices can matter more in a short series than in a long regular season where roles and workloads can be smoothed across many games.
Baseball statistics need sample-size discipline. A hitter’s performance over ten postseason plate appearances tells less about underlying ability than a much longer period of play. Analysts can compare strikeout rates, on-base production and matchup tendencies while avoiding exaggerated claims drawn from one home run or one defensive error. Recent injuries and announced starting lineups can change the outlook quickly.
Broadcast rights and local time differences
A game carried by a U.S. broadcaster may require a different provider for an international audience. Some streaming services include blackout restrictions and authenticated subscriptions. Before directing readers to a platform, check the league’s official listing for the game, region and date. A schedule can shift because of series outcomes or weather; do not assume every potential Game 6 or Game 7 will occur. Conditional games should be clearly labeled so viewers do not subscribe or travel based on a nonexistent fixture.
Fans outside North America should verify dates carefully. A game beginning late at night in U.S. Eastern Time can appear on the following morning in Pakistan or elsewhere. A credible global article uses time-zone labeling and, where practical, provides local conversions while directing readers to official confirmations.
Planning a trip to a postseason game
Buy tickets through the team’s verified ticket office or a recognized authorized resale route. Read what happens to a ticket for an “if necessary” game that is never played. Lodging and transportation may be nonrefundable even when the ticket itself is refunded under a particular policy. Stadium entry rules, bag restrictions and transport can vary by venue. Travel budgets should include potential schedule shifts, especially when the identity of the next opponent is not yet known.
Reseller offers that look dramatically cheaper than the going rate can be fraudulent. Confirm seat location, transfer method and the platform’s buyer-protection terms. Never assume an image of a barcode sent by a stranger proves a usable ticket. The simplest defense is to purchase through verified channels and retain the order record.
A bracket-tracking method that stays accurate
For each series, maintain the teams, seeds, current games-won tally, next confirmed game time, probable or announced starters, broadcaster and a direct MLB link. Update each row only after official results. Distinguish “clinched” from “leads series.” If a matchup concludes earlier than its maximum length, remove unused dates or mark them canceled; otherwise a static editorial calendar can appear inaccurate within hours.
The purpose of a postseason guide is not to predict every winner. It is to make a fast-moving bracket understandable and give fans reliable answers on what happens next, where to watch and which details remain uncertain.
Baseball postseason questions answered
Does every potential game on a postseason schedule occur?
No. A best-of-seven series ends when one team reaches four wins. Games listed as “if necessary” do not take place if the series has already been decided. Ticket buyers and travelers should understand refund or cancellation policies associated with those conditional dates before arranging flights and hotels.
Why do playoff teams use pitchers differently?
A shorter series changes the cost of saving an elite relief pitcher or spacing starting assignments. Managers may make aggressive substitutions to protect a narrow lead, while maintaining enough arms for a possible next game. Such choices can look different from regular-season strategy, when teams plan around a longer schedule and broader workload management.
Can a postseason match move after its first announcement?
Yes. Broadcast planning, prior series results and circumstances such as weather can affect schedules. MLB’s official game page and league notices should be checked shortly before travel or viewing. An editorial table that fails to update conditional games can easily mislead readers as the bracket advances.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
SpaceX CEO Elon Musk has escalated a public dispute over Starlink’s delayed commercial launch in India, sarcastically addressing Reliance Industries Chairman Mukesh Ambani as “Prime Minister Ambani” and questioning whether he holds outsized influence over the country’s telecom landscape. The remarks, posted on X in early October 2026, center on claims that entrenched interests—particularly around Reliance Jio—are slowing satellite broadband approvals to protect market dominance. Indian authorities have rejected the accusations as baseless, emphasizing a uniform regulatory process for all licensed satellite operators. Bloomberg
Musk’s Escalating Posts and Arguments for Starlink
Musk first accused unnamed “oligarchs” of blocking Starlink to maintain a “monopolistic chokehold on the Indian people,” describing the situation as “a crime against the people of India.” He followed by asking, “Is Ambani the real boss of India?” after noting that Starlink is licensed in over 165 countries and has spent five years complying with Indian requirements. In a subsequent post addressed as “Dear Prime Minister Ambani,” he offered a “humble apology” for not recognizing Ambani’s role and urged him to allow competition, arguing that satellite internet could connect underserved areas. Times of India
Musk highlighted potential benefits: improved access for children to education, opportunities for small businesses to reach global markets, and life-saving connectivity during natural disasters when terrestrial networks fail. He later pushed back against critics, stating that competition would benefit Indian consumers with more choices, that Ambani “is not going out of business,” and that Starlink would need affordable pricing to gain traction. Times of India
Government Position: No Monopoly, Uniform Rules for All Licensees
Union Communications Minister Jyotiraditya Scindia has directly addressed the claims, stating that “India does not allow a monopoly in any sector.” He confirmed that three companies hold Global Mobile Personal Communication by Satellite (GMPCS) licences: Starlink, Reliance’s Jio Satellite Communications, and Bharti-backed Eutelsat OneWeb. All three are at a similar regulatory stage and can begin commercial services only after each individually completes security clearances (assessed primarily by the Ministry of Home Affairs) and the government finalizes the revenue-based spectrum charging framework. CNBC TV18
The Department of Telecommunications has described suggestions of discriminatory treatment as “baseless and misconceived.” Security requirements include data localization, lawful interception capabilities, Indian gateways, and related technical demonstrations—conditions that apply equally across licensees. Spectrum assignment is set to be administrative rather than auction-based, with a usage charge of around 5% of adjusted gross revenue (lower for rural/remote areas) nearing finalization with the Telecom Regulatory Authority of India. Business Standard
Starlink’s Approval Timeline and Remaining Hurdles
Starlink received its GMPCS licence from the Department of Telecommunications in June 2025 and IN-SPACe authorization for its Gen-1 constellation in July 2025, following years of engagement that began with an application around November 2022. Provisional spectrum for testing has been available in some cases, but commercial operations require the outstanding security clearances and spectrum assignment. OneWeb and Jio Satellite secured earlier licences but face the same final milestones. Amazon’s Project Kuiper has also expressed interest and is under review. Business Standard
India’s Telecom Landscape and Connectivity Gaps
Reliance Jio remains India’s largest wireless operator, with roughly 500–530 million connections and about 39% market share as of mid-to-late 2026 data, closely trailed by Bharti Airtel at around 38%. Together the two private players dominate the market, with Vodafone Idea and BSNL holding smaller shares. Jio has driven significant growth in 5G adoption and fixed broadband. TelecomLead
Despite high overall coverage, a digital divide persists. TRAI and related data show India with over 1.09 billion internet subscriptions as of early 2026, but rural penetration stands at about 48 subscriptions per 100 people versus roughly 127 in urban areas. Large numbers of people live within mobile broadband footprints yet do not use the internet, with rural-urban gaps remaining notable. Satellite services are positioned by regulators as particularly suited for remote, border, hilly, and island areas that are harder to serve with terrestrial infrastructure. Government programs such as BharatNet continue expanding fiber and mobile coverage in villages. The Policy Edge
Broader Implications
The exchange underscores tensions between global satellite broadband ambitions and national regulatory, security, and competitive frameworks in one of the world’s largest telecom markets. Proponents of faster Starlink entry argue it could accelerate connectivity in hard-to-reach areas and introduce pricing and service competition. Authorities maintain that the process prioritizes security, data protection, and a level playing field among multiple licensed players rather than favoring any single incumbent. As of mid-October 2026, commercial satellite broadband services from any of the three licensees have not yet launched, pending the completion of remaining individual clearances and spectrum finalization.
Musk’s posts have drawn responses from opposition figures, including Rahul Gandhi, but the core dispute remains centered on the pace and nature of regulatory approvals for satellite internet in India. Further clarity is expected once security assessments conclude and the spectrum pricing regime is formally implemented.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Resilience Under Strain: The World’s Difficult 2026 Choices

Andy Harris in 2026: Freedom Caucus Influence, Spending and Congressional Power

MLB Playoffs 2026: Postseason Format, Broadcast Guide and How to Track the Bracket

Elon Musk Calls Mukesh Ambani the “Real Boss of India” Over Alleged Monopoly Concerns

Legal Pioneer and Defender of Justice: The Life, Works, and Legacy of Navi Pillay

Inside the Modern Republican Party Platform: Tax Policy, Immigration, and Governance

Anne Carson: Genius of Hybrid Forms and 2026 Nobel Laureate in Literature

Analyzing the Republican Voter Enthusiasm Gap: Turnout Metrics and Polling Data

The West Wing Legacy: Why the Political Drama Is More Relevant Than Ever

Pakistan Warns UN Security Council of AI Risks to Global Peace and Equality

Min Ah: The Global Impact and Rising Popularity of the K-Drama Star
Inside the Modern Republican Party Platform: Tax Policy, Immigration, and Governance

Fortress Diplomacy: How China’s Secretive Hongqi N701 Matches America’s Legendary “Beast”
Analyzing the Republican Voter Enthusiasm Gap: Turnout Metrics and Polling Data
Anne Carson: Genius of Hybrid Forms and 2026 Nobel Laureate in Literature

Remembering Kianna Underwood: The Nickelodeon Actress Behind “All That” and “Little Bill”
Elon Musk Calls Mukesh Ambani the “Real Boss of India” Over Alleged Monopoly Concerns
The West Wing Legacy: Why the Political Drama Is More Relevant Than Ever
-

 Featured6 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Democracy5 years ago
Missing You! SPSC
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills