Analysis
Saudi Arabia’s Long Game for Managing OPEC in a Fractured Era

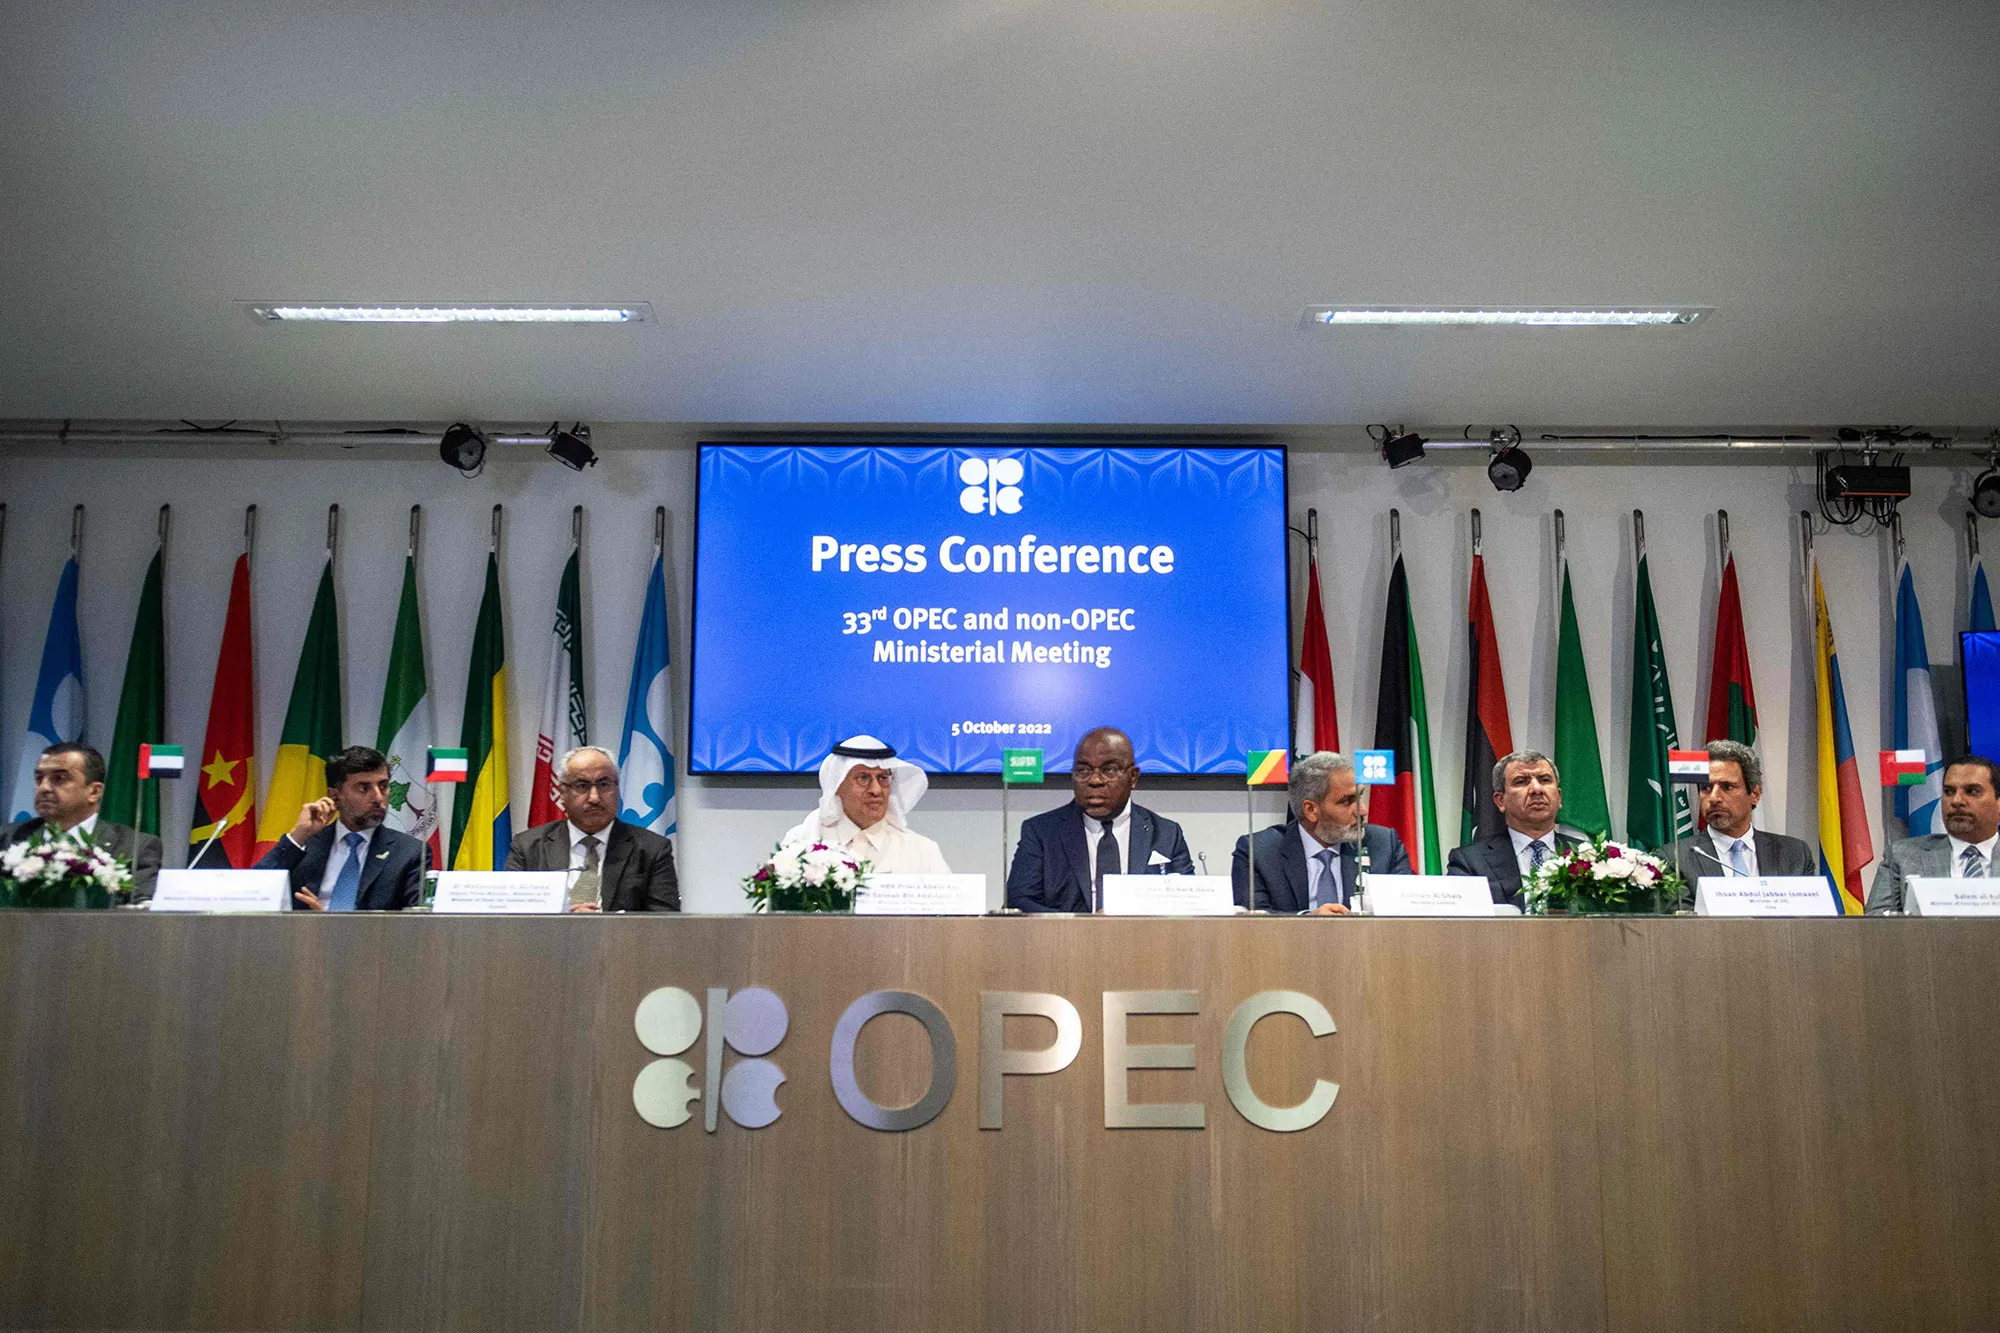
When Abu Dhabi dropped its geopolitical bombshell in late April 2026, formally exiting OPEC after nearly six decades, the immediate assumption across global trading desks was that Riyadh would retaliate. The UAE exit OPEC impact on Saudi Arabia seemed, at first glance, like a fatal blow to the cartel’s cohesion. After all, when managing OPEC through previous mutinies, Saudi Arabia’s reflex was often swift and punishing. Yet, the reaction from the Kingdom has been a deafening, strategic silence.
Rather than launching a reactive price war or engaging in public recriminations, Crown Prince Mohammed bin Salman and his half-brother, Energy Minister Prince Abdulaziz bin Salman, are deploying the “silent treatment.” This isn’t paralysis; it is a meticulously calculated Saudi Arabia long game for OPEC. Amidst the chaos of a burning Middle East, the ongoing blockade in the Strait of Hormuz, and fracturing global alliances, Riyadh is fundamentally recalibrating its Saudi oil production strategy to navigate a post-cartel reality. They are proving that in the modern era of energy realpolitik, true power is measured not by how loudly you threaten the market, but by how much spare capacity you quietly hold in reserve.
Table of Contents
Why Silence Speaks Louder Than Confrontation
I remember the panicked whispers in the corridors of the OPEC secretariat in Vienna back in March 2020. When relations with Moscow temporarily frayed, Riyadh’s response was visceral—they opened the spigots, flooding the market to force compliance. They employed a similar scorched-earth tactic between 2014 and 2016 in a brutal, ultimately pyrrhic bid to drown the emerging US shale industry.
Today, the mood in Riyadh is entirely different. It is icy, corporate, and intensely focused. The Kingdom’s current Saudi Arabia managing OPEC playbook recognizes that the era of the crude market share war is over.
Why the restraint? First, one must look at the math. According to recent assessments by the International Energy Agency (IEA), Saudi Arabia has been deliberately pumping around 9 to 9.5 million barrels per day (bpd), keeping roughly 3 million bpd of capacity completely offline. This voluntary restraint has propped up prices, which have swung violently between the high $80s and well over $100 a barrel following the outbreak of the US-Israeli conflict with Iran in late February 2026.
If Saudi Arabia were to punish the UAE by flooding the market today, they would be setting their own house on fire. A price collapse would wreck the fiscal foundation required for Vision 2030, Crown Prince Mohammed bin Salman’s multi-trillion-dollar economic diversification mandate. More importantly, as The Financial Times recently noted, Prince Abdulaziz is a master of the “Saudi lollipop”—the unexpected, voluntary cut that punishes short-sellers and stabilizes the market. His silence today is merely the inverse of that strategy. He is letting the market absorb the shock of the OPEC+ fractures without providing the panic that speculators desperately crave.
The UAE Factor: Cracks in the Gulf Cartel
To understand the Saudi silent treatment OPEC strategy, one must dissect the grievances of the departing party. The UAE did not leave on a whim. The Abu Dhabi National Oil Company (ADNOC) has poured roughly $150 billion into an aggressive capital expenditure program over the past decade, expanding its nameplate production capacity to 4.85 million bpd.
Under the old OPEC+ constraints, the UAE was forced to idle nearly a third of that capacity. Think about the economic friction of that reality. A prominent analysis from the Baker Institute previously estimated that quota constraints cost Abu Dhabi upward of $50 billion annually in foregone revenue. From the Emirati perspective, they were single-handedly subsidizing Saudi Arabia’s price management strategy.
When Abu Dhabi officially cut ties on May 1, 2026, it stripped the cartel of roughly 12 percent of its overall production and its third-largest member. But the timing of the exit reveals a deep irony—one that Riyadh is acutely aware of.
The UAE wanted freedom to pump. But right now, they physically cannot move the volumes they desire. The retaliatory blockade of the Strait of Hormuz by Iran has essentially trapped Gulf exports. While the UAE does possess the Habshan–Fujairah pipeline (ADCOP) which bypasses the choke point, that infrastructure maxes out around 1.5 to 2 million bpd. It cannot absorb ADNOC’s full unconstrained capacity. Riyadh knows that Abu Dhabi has essentially declared independence on a deserted island. There is no need for Saudi Arabia to fight a rival who is currently logistically contained by a regional war.
Hormuz, Trump, and the Geopolitical Chessboard
We cannot view OPEC future Saudi strategy 2026 in a vacuum. The cartel’s internal drama is playing out against the most volatile geopolitical backdrop in a generation.
The resumption of Trump-era dynamics in Washington has placed maximum pressure on Tehran, emboldening US shale producers while demanding that Gulf allies fall strictly in line with American security architectures. Riyadh, however, has spent the last five years carefully hedging its bets, building a surprisingly durable energy alliance with Moscow through the expanded OPEC+ framework, and courting Beijing as its primary buyer.
The Hormuz disruption has torn up the standard macroeconomic playbook, creating a cascading crisis for global trade. We are witnessing severe supply chain dislocations, with the most acute economic pain felt not in Washington or London, but across import-dependent South Asian corridors. Nations like Pakistan—currently navigating precarious structural reforms, a heavy external debt burden, and complex domestic constitutional amendments—find themselves exceptionally vulnerable to this imported inflation. As energy prices dictate the cost of freight, agriculture, and manufacturing, the macroeconomic contagion spreading through emerging markets is profound.
Riyadh recognizes this fragility. A Saudi-led price war right now wouldn’t just hurt the UAE; it would introduce catastrophic volatility into a global economy already buckling under the weight of regional conflicts and sticky inflation. By maintaining a steady hand and quietly engineering the recent May 3 agreement to gently adjust output by a mere 188,000 bpd among the remaining seven core OPEC+ members, Saudi Arabia is acting as the central bank of oil. They are choosing hegemony through stability rather than hegemony through volume.
Vision 2030: The Domestic Calculus Restraining the Spigots
If geopolitics provides the context for Saudi restraint, domestic economics provides the ironclad mandate. The Kingdom is in the thick of executing Vision 2030. The sovereign wealth fund, the Public Investment Fund (PIF), requires immense, uninterrupted liquidity to finance giga-projects like NEOM, the Red Sea development, and aggressive investments in global sports and technology.
Bloomberg Intelligence data consistently suggests that Saudi Arabia requires oil to hover near $85 to $90 a barrel to balance its budget and fund these sovereign ambitions without tapping too deeply into foreign reserves.
The UAE’s exit theoretically pressures Saudi Arabia to capture market share before the energy transition accelerates. But the Saudi technocrats understand that market share at $40 a barrel is useless to them right now. They need cash flow. They will happily let the UAE negotiate its own bilateral deals with China and India. Saudi Aramco’s unmatched scale, combined with its deeply entrenched, long-term supply contracts in Asia, ensures that the Kingdom will not be easily dislodged from its primary markets.
Furthermore, a disciplined, quiet Saudi Arabia remains an attractive prospect for foreign investors. As the government continues to float secondary offerings of Aramco shares—a vital mechanism for raising tens of billions of dollars for the PIF—projecting an image of a chaotic, warring cartel is bad for business. Silence is the ultimate corporate flex.
Global Implications for Oil Markets: The Leaner Cartel
What does this mean for the future of the organization? The OPEC+ fractures are undeniable. Following the departures of Qatar (2019), Ecuador (2020), and Angola (2023), the loss of the UAE reduces the organization’s total output footprint. Pundits are quick to write the cartel’s obituary, as they have done every decade since the 1970s.
Yet, paradoxically, a smaller OPEC may prove to be a more agile instrument for Riyadh. The UAE was the loudest dissenting voice in the room, constantly challenging Saudi baselines and demanding capacity recognition. With Abu Dhabi out of the room, Prince Abdulaziz bin Salman exercises virtually uncontested control over the remaining core—Algeria, Kuwait, Kazakhstan, Oman, Iraq, and Russia.
Yes, chronic overproducers like Iraq and Kazakhstan will continue to test the boundaries of their quotas, as Reuters investigations have repeatedly documented. But managing these minor infractions is a standard diplomatic chore for the Saudi Energy Ministry. Stripped of its primary internal challenger, OPEC transitions from a multi-polar cartel into a streamlined extension of Saudi foreign policy.
The Future Outlook: Saudi Arabia’s Long Game
Looking ahead through the remainder of 2026, the global energy markets must adjust to a new paradigm. The UAE will undoubtedly maximize its production capacity the moment the geopolitical temperature cools and the Strait of Hormuz fully reopens. They will aggressively court Asian buyers, likely offering competitive pricing structures outside the rigid OPEC framework.
When that happens, the true test of the Saudi Arabia long game OPEC strategy will arrive. Will Riyadh finally unleash its 3 million bpd of spare capacity to remind Abu Dhabi who controls the marginal barrel?
Likely not in the way the market fears. Expect Saudi Arabia to respond with surgical precision rather than brute force. They will leverage their vast downstream investments—refineries and petrochemical plants deeply integrated into the economies of China and South Korea—to lock in demand that the UAE cannot easily steal. They will use their unmatched political weight to squeeze the UAE diplomatically, reinforcing the reality that while Abu Dhabi may have the oil, Riyadh holds the keys to broader regional security and integration.
The silent treatment is not a sign of weakness; it is the ultimate expression of confidence. Having weathered shale revolutions, global pandemics, and countless regional wars, the architects of Saudi oil policy know that mutinies are temporary, but geology is permanent. The United Arab Emirates has taken a bold, calculated risk to walk away from the table. But Saudi Arabia isn’t just sitting at the table anymore—they own the house. And in this house, silence is the heaviest weapon of all.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


For six years, the USMCA functioned as a predictable backstop for North American supply chains — a rare constant through a volatile trade era. That predictability ended on July 1, 2026. The United States Trade Representative confirmed it would not agree to renew the USMCA in its current form following the agreement’s mandatory six-year joint review, and by September, the standoff had escalated sharply: new Section 338 tariffs on Canadian goods, a doubling of steel and aluminum duties, and stalled Canada-US talks, even as Mexico continued active, if difficult, bilateral negotiations. For supply chain executives, the question is no longer whether North American trade rules will change — it is how fast, and which sourcing models survive the transition.
Key Takeaways
- The USTR announced on July 1, 2026 that it would not renew the USMCA in its current form, following the agreement’s mandatory six-year joint review — though the agreement remains legally in force while negotiations continue, and full withdrawal by any party would take six months to take effect.
- New Section 338 tariffs on Canada-origin goods took effect August 19, 2026 at a 50% ad valorem duty, applying even where USMCA duty-free status would otherwise apply, following the collapse of a September round of Canada-US talks.
- An estimated 85% of Mexican exports to the US remain USMCA-compliant and exempt from newer tariff actions, including a Section 301 forced-labor enforcement action covering 60 economies — while Canada has not opened formal, text-based bilateral negotiations tied to the review at all.
- The central unresolved dispute with Mexico is automotive content requirements: Washington is seeking a 50% US-specific content threshold for vehicles to qualify for preferential USMCA access, which Mexico is resisting and has linked to relief from existing Section 232 tariffs on autos (25%) and steel/aluminum (50%).
- Despite the tariff escalation, nearly 60% of goods imported from Canada and Mexico continue to enter the US duty-free, underscoring that North American trade disruption in 2026 remains targeted and negotiated rather than a wholesale breakdown of integration.
How the Standoff Reached This Point
The current confrontation traces back through a specific legal and political sequence. After the US Supreme Court struck down IEEPA-based tariffs in February 2026, the administration pivoted to alternative legal authorities: a 10% tariff on Canada and Mexico under Section 122 of the Trade Act of 1974 (with an exemption maintained for USMCA-compliant goods), alongside a separate, unaffected 25% tariff on Canadian and Mexican steel, aluminum, and certain auto products under Section 232 of the Trade Expansion Act of 1962 — subsequently raised to 50% for steel and aluminum.
The USMCA’s mandatory six-year joint review, triggered by a provision written into the original 2020 agreement, then became the vehicle for a more fundamental renegotiation push. On July 1, 2026, the USTR confirmed it would not renew the agreement in its current form, citing purported shortcomings and ongoing trade deficits with both neighbors. Crucially, this announcement did not terminate the agreement or preferential trade — the USMCA remains in force while the three governments work through the issues raised, and any formal withdrawal by a party would not take effect for six months, a design feature intended to preserve negotiation leverage without triggering an immediate supply chain shock.
The situation escalated further by September: the US deployed the rarely used Section 338 tariff authority against Canada specifically, roughly doubling existing steel and aluminum rates and reintroducing tariffs from a zero baseline across a much wider set of Canadian goods, after a round of talks collapsed. Canada, notably, has not yet opened a substantive, text-based bilateral negotiating round tied to the joint review itself, unlike Mexico — engagement has remained largely at the ministerial-call level between Canada’s Trade Minister and the US Trade Representative.
The Two-Track Negotiation: Mexico vs. Canada
A critical, underappreciated fact for 2026 supply chain planning is that the US is running genuinely different negotiating tracks with its two USMCA partners:
Mexico has completed two full bilateral negotiating rounds covering automotive rules of origin, steel and aluminum, economic security, industrial goods, agriculture, labor, environmental standards, and regulatory compatibility. The core sticking point remains automotive content: Washington’s push for a 50% US-specific content requirement (versus the current North American-content framework) is being actively resisted by Mexico, which has explicitly linked any concessions to relief from existing Section 232 auto and metals tariffs. Mexican officials have noted that a separate Section 301 forced-labor enforcement action covering 60 economies produces no practical change for Mexican exporters specifically, since USMCA-compliant goods — an estimated 85% of Mexico’s US-bound exports — remain exempt as long as rules-of-origin requirements are satisfied.
Canada, by contrast, has not begun formal bilateral negotiations tied to the review at all, and its position has deteriorated sharply since July 1: the September Section 338 action roughly doubled steel and aluminum rates and reintroduced tariffs across a substantially broader set of goods from a zero baseline, representing the most significant escalation in the relationship since the review began.
What This Means for Supply Chain Restructuring
Rules of Origin Are Now a Live Compliance Risk, Not a Static Baseline
With automotive content requirements under active renegotiation and other sectors facing scrutiny, businesses that have treated USMCA rules-of-origin qualification as a fixed, one-time certification exercise face material risk. A targeted change to a single rule of origin, tariff classification, or certification requirement can affect thousands of suppliers and shipments across an integrated production network simultaneously — meaning sourcing and logistics models that currently qualify for preferential treatment may not continue to qualify under a revised framework, even without any change to the physical supply chain itself.
Mexico Remains the More Stable Near-Term Sourcing Base
Given Mexico’s active, structured bilateral negotiation track and the 85% USMCA-compliance exemption rate for its exports, Mexico currently presents a comparatively more predictable near-term sourcing environment than Canada, where the absence of formal negotiations combined with the September escalation has introduced acute uncertainty. This is a reversal of the historical assumption that Canada — as the more institutionally aligned partner — represents lower trade-policy risk.
Automotive and Metals-Intensive Supply Chains Face the Sharpest Exposure
The unresolved automotive content dispute with Mexico and the doubled steel/aluminum tariffs on Canada concentrate risk specifically in vehicle manufacturing, auto parts, and any metals-intensive industrial supply chain — sectors where BCG’s analysis has noted that tariff costs, layered onto supply disruption, could threaten the survival of some auto and auto parts companies, with downstream effects on retail prices, annual vehicle sales, and industry employment.
The Duty-Free Baseline Still Holds — For Now
The single most important stabilizing fact for supply chain planning is that nearly 60% of goods imported from Canada and Mexico continue to enter the US duty-free despite the standoff, and full treaty withdrawal by any party remains widely viewed as unlikely given the depth of North American supply chain integration and the six-month withdrawal notice period built into the agreement’s design. This suggests businesses should plan for continued negotiation-driven volatility in specific sectors (autos, steel, aluminum) rather than a wholesale collapse of North American trade preference.
Supply Chain Restructuring Strategies for 2026–2027
- Segment supplier risk by rules-of-origin sensitivity, not just by country. A supplier whose qualification depends on automotive content thresholds under active renegotiation carries fundamentally different risk than one in a sector untouched by the current disputes.
- Build contractual flexibility into sourcing agreements for tariff-classification changes. Given that thousands of suppliers can be affected by a single rule change, procurement contracts should include tariff-exposure adjustment mechanisms rather than assuming static classification.
- Treat Canada-sourced steel, aluminum, and metals-intensive inputs as higher near-term risk than comparable Mexican inputs, given the divergent negotiation tracks and the September escalation specifically targeting Canadian goods.
- Monitor the Section 232 auto tariff–content requirement linkage closely. Mexico’s explicit linking of content-rule concessions to Section 232 relief means any resolution is likely to arrive as a package, not sector by sector — businesses should model scenarios for both continued impasse and a bundled resolution.
- Avoid over-reacting to headline tariff announcements without checking USMCA-compliance exemption status. With roughly 85% of Mexican exports and 60% of combined Canada-Mexico imports still qualifying for duty-free treatment, the practical tariff exposure for a specific supply chain often differs substantially from the headline rate.
Frequently Asked Questions
Is the USMCA ending in 2026?
No. The USTR declined to renew the USMCA in its current form as of July 1, 2026, but the agreement remains legally in force while negotiations continue; a formal withdrawal by any party would take six months to take effect and is considered unlikely given deep supply chain integration.
How are US tariffs on Canada different from tariffs on Mexico in 2026?
Canada faces a more severe and less negotiated situation: new Section 338 tariffs took effect in August 2026 at 50% on certain goods, talks collapsed in September, and Canada has not opened formal bilateral negotiations. Mexico has completed two full bilateral negotiating rounds, and roughly 85% of its US-bound exports remain USMCA-compliant and tariff-exempt.
What is the main unresolved issue in the USMCA renegotiation with Mexico?
Automotive content requirements — the US is seeking a 50% US-specific content threshold for vehicles to qualify for preferential access, which Mexico is resisting and has linked to relief from existing steel, aluminum, and auto tariffs.
Conclusion
The 2026 North American tariff standoff is best understood not as a collapse of continental trade integration but as a genuine, high-stakes renegotiation running on two very different tracks — a structured, if difficult, Mexico process and a stalled, escalating Canada process. With nearly 60% of Canada-Mexico imports still entering the US duty-free and full treaty withdrawal remaining a low-probability outcome, the practical task for supply chain leaders is precision: distinguishing which specific inputs, sectors, and supplier relationships carry genuine renegotiation risk from the broader base of trade that remains, for now, stable.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
With the November 3, 2026 midterm elections roughly two months away, multiple independent forecasting models are converging on a similar conclusion: Democrats are currently favored to retake control of the U.S. House of Representatives, though the size of any majority — and control of the Senate — remains genuinely uncertain.
This piece breaks down what the leading models actually say, why historical patterns favor the out-of-power party in midterms, and which structural factors could still complicate a Democratic pickup.
The Current Numbers
Heading into the cycle, Republicans hold a narrow 218-seat majority, with Democrats at 212 seats and several vacancies. Because of that narrow margin, Democrats need to flip only a small net number of seats — commonly cited as roughly three to six, depending on how upcoming special elections in safely Democratic vacant seats resolve — to reclaim the majority.
Several independent models have published 2026 House projections:
- A Cornell University-based academic forecasting team, presenting at the American Political Science Association’s annual meeting, projects Democrats winning approximately 226 seats to Republicans’ 209, with simulations showing a plausible range as wide as 206 to 258 Democratic seats.
- A separate independent forecasting outlet (FiftyPlusOne) gives Democrats an 85% probability of winning the House majority, with a median projected outcome of 230 seats, and a national House popular-vote margin estimated at roughly +7 points for Democrats.
- Aggregator and prediction-market platforms tracking the race show a broadly consistent picture: Democrats favored, with meaningful — not negligible — uncertainty remaining.
Researchers behind the Cornell model were notably direct about what it would take for the forecast to be wrong: given the model’s historical accuracy, a Republican House majority holding would likely mean “either everything has gone their way or something unprecedented has happened.”
Why History Favors Democrats Structurally
Election forecasters lean heavily on one of the most consistent patterns in American politics: the president’s party almost always loses House seats in midterm elections.
- Looking back across 36 midterm elections since 1882, the White House party avoided losing a net of at least three seats in only four of them — 1934, 1962, 1998, and 2002 — each occurring under unusual circumstances (the Great Depression recovery, the Cuban Missile Crisis aftermath, post-9/11 unity, and the Clinton impeachment backlash, respectively).
- Democrats need a uniform national swing of roughly 1.1% from the 2024 House results to flip control — a relatively low bar by historical standards.
- Special elections held throughout 2025 provide an early, concrete signal: across roughly 31 state legislative and House special elections, Democratic candidates outperformed the 2024 presidential ticket’s vote share by an average of 15.4 points (median 13 points) — more than ten times the swing needed to flip the House.
The Redistricting Wildcard
No 2026 forecast is complete without accounting for the unusual mid-decade redistricting activity that has reshaped the House map since the 2024 election. Aggressive redistricting in several Republican-controlled states has given the GOP additional structural insulation heading into this cycle — a countervailing force against the historical midterm pattern and the favorable special-election trendline described above. This is the central tension every current model is trying to price in: strong Democratic generic political environment signals, against a map that has been deliberately reshaped to blunt exactly that kind of environment.
The GOP Counter-Strategy
Republican strategists are not treating the historical pattern as inevitable. Key elements of the party’s defensive posture include:
- Leaning on redistricting gains in states where new maps have already been implemented, effectively “banking” seats that would otherwise be more competitive under prior district lines.
- Fundraising and turnout operations targeted specifically at the small number of genuinely competitive districts where the national environment is expected to matter most.
- Nationalizing the midterm around specific policy contrasts rather than running on incumbency alone, given that broad “stay the course” messaging tends to perform poorly for an incumbent president’s party in a midterm.
What Swing Districts Are Actually Deciding This
Rather than the national popular vote, the real decision point sits in a relatively small number of competitive districts — often those that saw redistricting changes, those with retiring incumbents, or historically split-ticket suburban seats. Readers tracking this race closely should watch:
- Districts with open seats created by incumbent retirements, which historically see larger swings than seats with incumbents running for reelection.
- Suburban districts that have trended away from the GOP in recent cycles, where the current generic-ballot environment would need to hold through November to matter.
- Newly redrawn districts in states where redistricting fights are still working through courts — some maps used in 2026 could still face late legal challenges.
What Competitors Are Missing
Much of the horserace coverage of this cycle reports the topline “Democrats favored” number without explaining why two structurally different forces — a strongly Democratic-leaning political environment on one hand, and an aggressively re-drawn map on the other — are pulling against each other simultaneously. That tension, not the headline probability number, is the actual story of the 2026 House cycle, and it’s why even a “85% favored” forecast still carries real uncertainty worth taking seriously rather than treating as a foregone conclusion.
Key Dates to Watch
- Ongoing — ballot access deadlines and any late redistricting litigation in contested states
- September–October 2026 — final pre-election generic ballot and fundraising disclosures
- November 3, 2026 — Election Day
- Early November 2026 — initial results; close districts may take days to certify
Q: Are Democrats favored to win the House in the 2026 midterms?
As of early September 2026, multiple independent forecasting models favor Democrats to win a U.S. House majority. One academic model projects roughly 226 Democratic seats to 209 Republican seats; another independent forecaster puts Democrats’ probability of winning the House at 85%, with a median projection of 230 seats. Republicans currently hold an 218-seat majority, and Democrats need only a small net seat gain to flip control.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
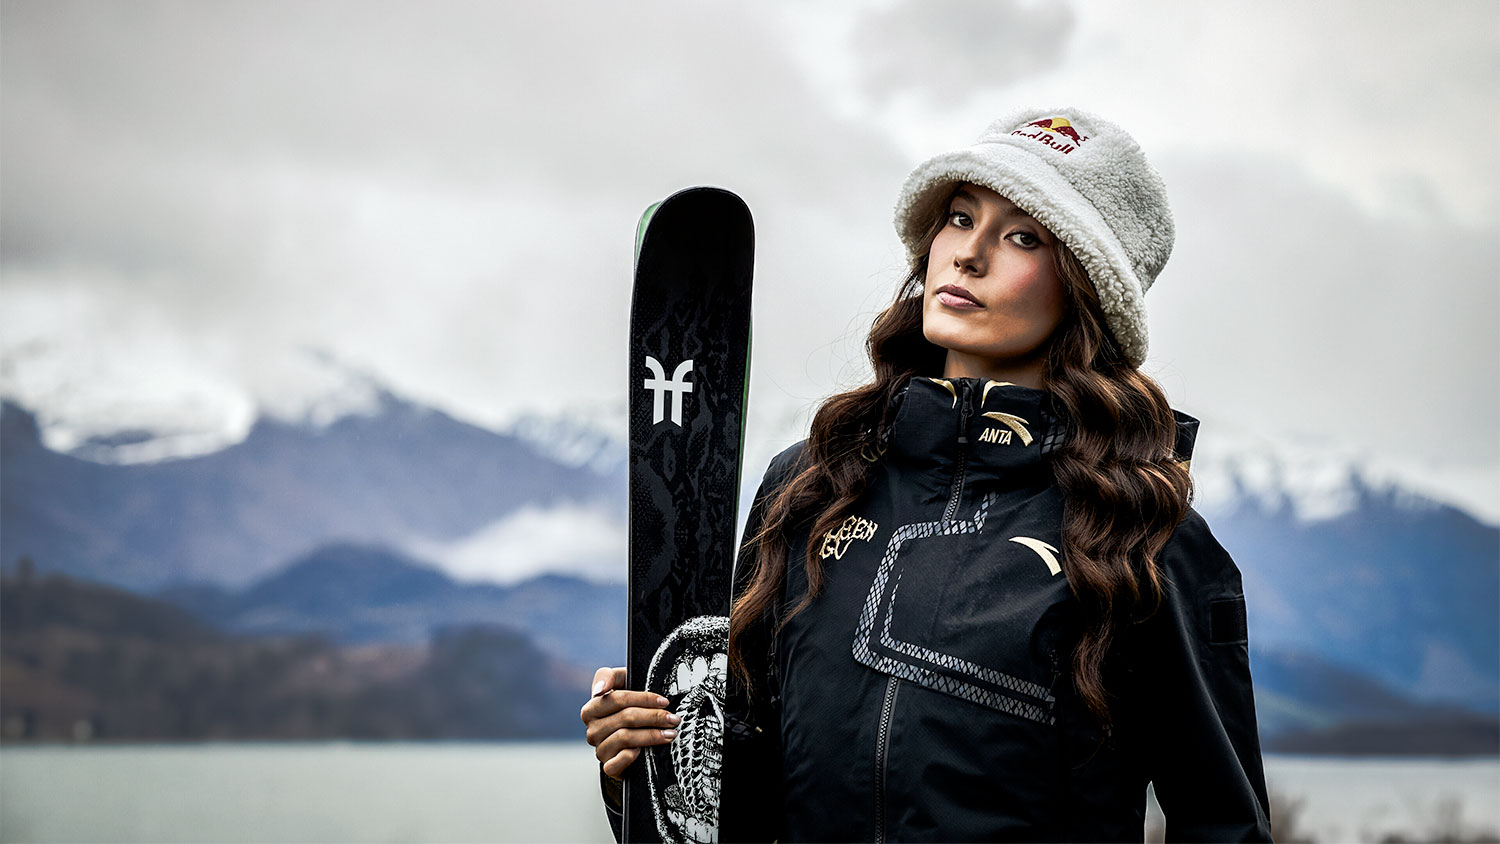
Six-time Olympic medalist Eileen Gu appeared on Jay Shetty’s “On Purpose” podcast (released August 31, 2026) to unpack the psychological framework behind her career, built around the mantra “train like I’ve never won and compete like I’ve never lost.” Off the slopes, Gu has parlayed her athletic profile into an estimated $50 million net worth, driven substantially by roughly $23.1 million in single-year endorsement earnings from brands including Louis Vuitton, Victoria’s Secret, Tiffany & Co., and Red Bull.
Eileen Gu: Career, Mindset & Brand at a Glance
| Metric | Figure |
|---|---|
| Total Olympic medals | 6 (across Beijing 2022 and Milano Cortina 2026) |
| Beijing 2022 medals | 2 gold, 1 silver |
| Milano Cortina 2026 medals | 1 gold, 2 silver |
| Estimated net worth (2026) | ~$50 million (Celebrity Net Worth, via Yahoo Sports) |
| Reported single-year endorsement earnings | ~$23.1 million (New York Times, cited 2025 figure) |
| Annual skiing prize-money earnings | Typically under $200,000 |
| Estimated annual endorsement income | $20 million+ |
| Age (as of 2026) | 22 |
| Education | Graduated Stanford University, June 2026 |
| Recent career move | Named Senior Associate at venture capital firm Benchmark |
| Major endorsement partners | Louis Vuitton, Victoria’s Secret (VS Collective founding member), Tiffany & Co., Red Bull, Porsche, IWC Schaffhausen, Fendi, Gucci |
| Modeling representation | Signed with IMG Models |
Sources: Jay Shetty’s “On Purpose” podcast (Aug. 31, 2026), Olympics.com, Yahoo Sports, Hello Magazine, and en.Tempo.co — all Feb.–Sept. 2026.
Deep Dive: The Psychology Behind the Podium, and the Business Behind the Brand
The Mantra, Unpacked: Why Two Contradictory Mindsets Coexist
Gu’s central framework — “train like I’ve never won and compete like I’ve never lost” — is deliberately built around psychological contradiction, and she’s been explicit in interviews about why that tension is the point rather than a flaw. In training, the “never won” half of the mantra keeps her in a self-critical, improvement-focused mindset regardless of past results, treating every practice session as though prior success carries no weight. In competition, the “never lost” half flips that entirely: total confidence, free of self-doubt, at the exact moment performance matters most. Gu has described competing with what she calls an “insatiable, almost obsessive, all-in mentality” — but she’s also cautioned that this intensity cannot be sustained indefinitely, which is precisely why she confines it to competition windows rather than treating it as a constant state.
“It’s Difficult to Win, But Way Harder to Stay There”
Gu has directly addressed the specific challenge of sustained excellence rather than a single peak performance, telling Shetty that so much changes for an athlete between ages 18 and 22 — the exact window spanning her Beijing 2022 and Milano Cortina 2026 Olympic appearances. Her framing treats her mantra not as a one-time psychological trick for a single competition, but as a sustainability mechanism: the “train like I’ve never won” half specifically functions to keep her hungry and prevent complacency across multiple competitive cycles, which she credits as the actual differentiator between athletes who win once and those who remain at the top over years.
“Evidence Over Affirmation”: A Distinct Confidence-Building Method
Beyond the headline mantra, Gu has described a related but distinct approach she calls “evidence over affirmation” — building competitive confidence from accumulated proof of capability (training data, prior performance, physical preparation) rather than from self-affirming statements alone. This is a meaningfully different psychological technique than generic positive self-talk: rather than telling herself she can succeed, her stated approach is to construct a body of concrete evidence through training that makes confidence a logical conclusion rather than a hopeful assertion. The distinction matters for anyone attempting to apply her framework outside elite sport — it suggests the actionable takeaway isn’t the affirmation itself, but the training rigor that generates evidence to draw confidence from.
The Business Reality: Endorsements Dwarf Competition Earnings by a Wide Margin
It’s worth being precise about where Gu’s wealth actually comes from, since the numbers are stark: her typical annual skiing prize money runs under $200,000, while her endorsement income has been reported at over $20 million annually and her single-year total endorsement earnings at approximately $23.1 million according to New York Times reporting. That roughly 100-to-1 ratio between competition earnings and endorsement income is not unusual among elite global athletes with strong commercial appeal, but it does mean that framing Gu primarily as a “skier who also does endorsements” inverts the actual economics of her career — the more accurate framing, financially speaking, is a global brand ambassador who also happens to compete at an elite level in freestyle skiing.
A Genuinely Diversified Brand Portfolio, Not a Single-Category Play
Gu’s endorsement portfolio spans several distinct commercial categories rather than concentrating in one lane: luxury fashion (Louis Vuitton, Fendi, Gucci, Tiffany & Co.), lingerie and lifestyle (as a founding member of Victoria’s Secret’s VS Collective, alongside athletes like Megan Rapinoe), automotive and performance brands (Porsche, Red Bull), luxury watches (IWC Schaffhausen), and a separate roster of China-market-specific partners including Bank of China, China Mobile, and Luckin Coffee. This category diversification is itself a deliberate brand-building strategy — it reduces Gu’s commercial dependence on any single industry’s marketing cycles or economic conditions, and positions her simultaneously in Western luxury markets and Chinese consumer markets, an unusually broad dual-market commercial footprint for an athlete her age.
The Pivot Into Venture Capital Signals a Post-Competition Business Strategy Already in Motion
Perhaps the most forward-looking data point in Gu’s business trajectory is her recent appointment as a Senior Associate at Benchmark, the venture capital firm led by Bill Gurley. This is a meaningfully different move than another endorsement deal or fashion campaign — it represents Gu building operating experience inside the institutional investing world while still an active competitive athlete, a sequencing choice that suggests a longer-term strategy of transitioning from “athlete with a personal brand” toward “operator with direct involvement in company-building and capital allocation” well before her competitive career concludes.
The Cross-Cultural Positioning That Underpins the Commercial Success
Gu’s commercial appeal is substantially built on a genuinely distinctive positioning: born and raised in San Francisco, she has competed for China since 2019 — a choice that drew public criticism from some in the US at the time but has since translated into standout commercial value in the Chinese market specifically, where she has been described by industry observers as a “golden star” with mainstream crossover appeal comparable to how Tony Hawk is positioned in US action sports culture. That dual-market credibility — genuine commercial traction in both major Western luxury markets and the Chinese domestic market simultaneously — is a structurally rare position for any athlete to occupy, and is arguably as important to her endorsement value as her competitive results themselves.
Actionable Takeaways for Readers Applying Gu’s Framework
- Separate your training mindset from your performance mindset deliberately, rather than trying to hold one constant state. Gu’s framework suggests self-criticism has a specific place (skill-building) and total confidence has a different, separate place (execution) — conflating the two may undermine both.
- Build confidence from accumulated evidence, not from repeated self-affirmation alone. If you’re preparing for a high-stakes moment — a presentation, an interview, a competition — Gu’s “evidence over affirmation” method suggests documenting concrete preparation and past performance data as your actual confidence foundation.
- Recognize that peak intensity is not sustainable as a constant state. Gu has been explicit that an all-in competitive mentality cannot be maintained indefinitely — treat high-intensity focus as something to deploy at specific moments rather than as your baseline operating mode.
- If building a personal brand, consider deliberate category diversification rather than single-lane concentration. Gu’s endorsement spread across fashion, lifestyle, automotive, and finance reduces dependency on any one industry’s cycles — a principle transferable well beyond professional sports.
- Treat major life transitions (like Gu’s Stanford graduation and Benchmark role) as planned sequencing rather than reactive pivots. Her move into venture capital appears to be a deliberate long-horizon career step taken while her athletic career is still active, rather than a post-retirement scramble — a sequencing lesson relevant to anyone building a career with a defined athletic or performance-based shelf life.
Frequently Asked Questions
What is Eileen Gu’s training mantra?
Gu’s stated mantra is “train like I’ve never won and compete like I’ve never lost” — a deliberately contradictory framework that keeps her self-critical and improvement-focused during training while adopting total, evidence-based confidence during actual competition.
How much is Eileen Gu worth in 2026?
Eileen Gu’s net worth is estimated at approximately $50 million as of 2026, according to Celebrity Net Worth as reported by Yahoo Sports, with the substantial majority of that wealth coming from endorsements and brand partnerships rather than skiing prize money.
What brands does Eileen Gu endorse?
Gu’s endorsement portfolio includes Louis Vuitton, Victoria’s Secret (as a founding member of the VS Collective), Tiffany & Co., Red Bull, Porsche, IWC Schaffhausen, Fendi, and Gucci, alongside China-market partners including Bank of China, China Mobile, and Luckin Coffee.
Does Eileen Gu have a career outside of skiing?
Yes — beyond her endorsement and modeling work (she is signed with IMG Models), Gu graduated from Stanford University in June 2026 and was subsequently named a Senior Associate at the venture capital firm Benchmark, signaling a deliberate move into institutional investing alongside her continued competitive skiing career.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Trump’s North America Flag Map Explained: Viral Image, USMCA Tensions

2026 Midterms: How Democrats Are Competing in Deep-Red Senate Seats

North American Tariff Standoff 2026: Supply Chain Guide

2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover

Analyzing Anthropic’s $15 Billion Credit Facility: What It Means for Stock Health

Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown

Johnny Ray and Nicole Mississippi: Attala County Case Explained

Clarence Thomas Unfiltered: The Ted Cruz Interview on Ethics and Identity

Fond du Lac Stalking Case: Serial-Killer Memorabilia, Skulls & the Criminal Complaint
Johnny Ray and Nicole Mississippi: Attala County Case Explained

Best Fitness Apps and Wearables That Connect to Health Insurance in 2026
2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover
Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown

RFK Jr. Confirmation Investigation 2026: Health Policy Fallout Explained
Fond du Lac Stalking Case: Serial-Killer Memorabilia, Skulls & the Criminal Complaint

CRM Stock, Workday, Cisco: What Earnings Signal Now
Clarence Thomas Unfiltered: The Ted Cruz Interview on Ethics and Identity

Shanghai Ravioli Chicken Recall 2026: Full Product List & Refund Guide
-

 Featured5 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Democracy5 years ago
Missing You! SPSC
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills