Analysis
Singapore’s Bold Bid to Become Asia-Pacific’s Gold-Trading Powerhouse: Why the City-State Is Racing to Capture Bullion Liquidity and Central-Bank Vaults

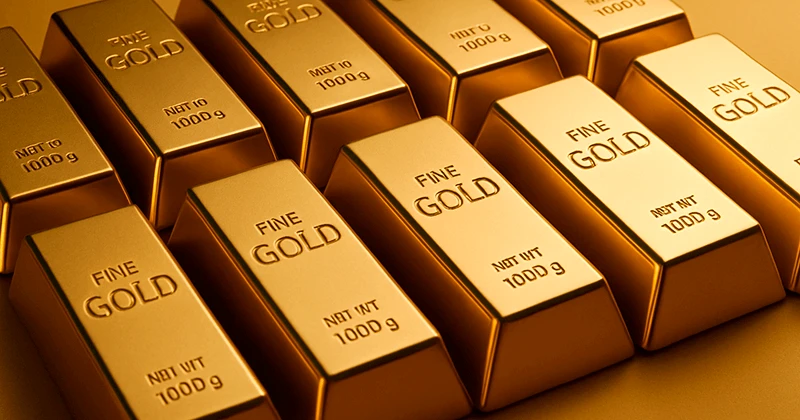
When gold briefly touched US$5,600 per troy ounce earlier this year — a price that would have seemed fantastical a decade ago — it was not traders on the floor of the London Metal Exchange who were most animated. It was central bankers from Warsaw to Kuala Lumpur, family offices in Singapore and Abu Dhabi, and sovereign wealth funds quietly recalibrating their exposure to a metal that has become the defining safe-haven asset of a fractured geopolitical era.
Even after a sharp pullback triggered by the outbreak of conflict in the Middle East dragged prices to around US$4,430 per ounce by late March, the structural story remains emphatically intact: gold’s gravitational centre is shifting east. And Singapore, with its formidable financial architecture and a reputation for regulatory elegance, intends to plant its flag firmly at that new centre. On March 27, 2026, the Monetary Authority of Singapore (MAS) and the Singapore Bullion Market Association (SBMA) unveiled four strategic focus areas designed to transform the city-state into Asia-Pacific’s premier Singapore gold-trading hub. It is, in every sense, a declaration of intent.
Table of Contents
The Eastward Drift of Bullion Power
To understand the ambition, first understand the moment. The World Gold Council projects central banks globally will purchase approximately 850 tonnes of gold in 2026, sustaining what has become one of the most consequential structural shifts in reserve management since Bretton Woods. Central-bank buying in 2025 reached 863 tonnes — historically elevated and geographically widespread, spanning Poland, Kazakhstan, Brazil, Malaysia, and Indonesia. In Asia alone, new entrants to official gold accumulation emerge almost quarterly, motivated by a common logic: in a world of dollar weaponisation, sanctions risk, and mounting geopolitical entropy, gold is the only truly neutral reserve asset.
J.P. Morgan Global Research forecasts combined central bank and investor gold demand averaging some 585 tonnes per quarter in 2026, underpinning its projection that prices could approach US$5,000 per ounce by year-end. Meanwhile, the World Gold Council’s annual survey recorded the highest central bank intention to buy gold since the survey was first conducted in 2019.
The institutional demand is substantial on its own. But pair it with the explosive growth of Asian retail and family-office demand — bar and coin demand is forecast to exceed 1,200 tonnes globally in 2026 — and the market opportunity for a well-positioned regional hub becomes unmistakable. Singapore, which removed goods and services tax on investment-grade precious metals in 2012, has long been a magnet for bullion storage and retail investment. What it has lacked is the deep capital-market plumbing — the derivatives, clearing infrastructure, and sovereign-custodian credibility — that would allow it to punch at the weight of London or Zurich. The initiative announced on March 27 is designed to close that gap with surgical precision.
Four Pillars, One Strategic Vision
The key focus areas were developed by a Gold Market Development Working Group that MAS and SBMA established in January 2026, building on detailed discussions and studies with industry participants in 2025. The working group reads like a who’s who of global bullion banking: DBS, ICBC Standard Bank, JPMorgan Chase, UBS AG, United Overseas Bank, SGX Group, and the World Gold Council sit at its core, supported by vault operators including Brink’s, Loomis International, and Malca-Amit, alongside trading houses StoneX APAC and YLG Bullion Singapore.
The four focus areas are individually significant. Taken together, they constitute a comprehensive blueprint for building a Singapore bullion market with genuine global depth.
1. Capital-Market Products: Building the Price-Discovery Engine
The first pillar is the development of gold-related capital-market products to promote price discovery and build liquidity. This is arguably the most technically demanding of the four goals and, in the long run, the most consequential. London dominates global gold pricing precisely because it is where the world’s deepest pool of paper gold — forwards, OTC derivatives, leases — meets its deepest pool of physical metal. Singapore currently lacks this two-sided market.
What might such products look like? Singapore-listed gold ETFs with physical backing in local vaults, gold forwards priced off a Singapore benchmark, and gold-linked structured notes accessible to regional wealth managers are all credible candidates. The SGX Group’s involvement in the working group hints at the ambition: a futures contract priced off kilobar gold (the one-kilogram bar standard prevalent across Asian markets and an accepted COMEX delivery contract) could serve as a genuinely Asian benchmark, less exposed to the idiosyncrasies of London’s 400-troy-ounce large-bar convention.
Establishing a vibrant Asia gold trading liquidity pool in Singapore would also give Asian producers, refiners, and jewellers a local hedge that does not require them to transact through time zones that are awkward for the region — an enduring frustration with London’s primacy.
2. Vaulting Standards: The Architecture of Trust
The second focus area — establishing robust, internationally aligned vaulting and logistics standards — is less glamorous but no less critical. The London Bullion Market Association (LBMA), which sets global Good Delivery standards for gold bars, provides the template. Singapore already hosts internationally reputable vault operators, but the absence of a formalised, regulator-backed standards framework has historically created friction for institutional clients accustomed to the certainty of LBMA accreditation.
Closing this gap matters for a straightforward commercial reason: institutional gold trading at scale — whether by a sovereign wealth fund, a pension manager, or an international trading house — requires documented chain-of-custody assurance, insurance frameworks, and logistics protocols that meet international audit standards. Singapore’s aspiration to house central-bank bullion, in particular, makes this pillar foundational. No central bank will deposit reserves in a jurisdiction whose vaulting standards are ambiguous.
The presence of Metalor Technologies Singapore — one of the world’s premier precious-metals refiners — among the working group’s technical participants signals that Singapore intends to offer not merely storage but an integrated precious-metals ecosystem: refining, vaulting, trading, and settlement, all under one regulatory canopy.
3. A Clearing System for OTC Gold Settlement
The third focus area may be the most operationally complex: building a clearing system to support secure and efficient over-the-counter settlement for trading both large bars (the 400-troy-ounce London convention, approximately 12.4 kilograms) and kilobars (one kilogram, the Asian institutional standard) in Singapore. This is, effectively, the plumbing that turns a storage location into a trading hub.
Currently, significant OTC gold trades involving Asian counterparties are typically settled through London infrastructure or via bilateral arrangements that carry meaningful counterparty risk. A Singapore-based clearing facility — ideally with central-counterparty clearing to eliminate bilateral exposure — would reduce settlement risk, lower transaction costs, and allow the market to function across Asian time zones without dependence on Western intermediaries.
The group will help establish a clearing system to support secure and efficient over-the-counter settlements when large bar and kilobar gold is trading in Singapore. Large bars of gold, which weigh about 12.4 kilograms, are the preferred standard for institutional trading and settlement in the London market. Kilobar, which has a weight of one kilogram, is the preferred standard in Asian markets and is an accepted delivery contract for COMEX gold futures contracts in the US.
The Singapore gold clearing system 2026 initiative thus serves a dual purpose: it creates the infrastructure for efficient local settlement and positions Singapore as a natural location for gold trading during Asian hours — a gap that neither London nor New York can fill on their own.
4. Central-Bank Vaulting: The Sovereign Dimension
The fourth and arguably most geopolitically resonant focus area is MAS’s stated intention to explore providing vaulting services for foreign central banks and sovereign entities. The gold is understood to be stored in MAS-owned vaults. This is a genuinely significant departure from Singapore’s existing role in the bullion ecosystem — and a direct play for the most coveted and creditworthy clients in the gold market.
Singapore’s proposal could potentially attract nations that have challenged the status and credibility of historic hubs such as London and New York. A number of countries including Germany have repatriated gold for security reasons, and there have been similar moves from Poland, the Netherlands and Serbia.
MAS Deputy Chairman Chee Hong Tat — who is also Singapore’s minister for national development — framed the initiative with characteristic measured confidence. “We are working closely with the industry to see how we can position Singapore as a gold trading hub in Asia,” he told reporters. He emphasised that Singapore’s ambitions are anchored in long-term ecosystem-building, not short-term price speculation: “When it comes to investments, there will be ups and downs. If you look at what we are doing, we are not placing bets on whether the prices in the short term will go up or go down. What we are doing is to create the ecosystem for gold trading activity to be based out of Singapore.”
For emerging-market central banks in Southeast Asia, South Asia, and the Gulf — particularly those that have historically stored reserves in New York or London but now seek diversification — Singapore offers something qualitatively distinct: a neutral, politically stable, rule-of-law jurisdiction in their own time zone, operated by a regulator with an impeccable international reputation. In an era when reserve assets can be frozen by Western governments with a keystroke, that proposition carries weight that is difficult to overstate.
The Competitive Landscape: Singapore vs. Hong Kong, Dubai, and the West
No analysis of the Singapore vs Hong Kong gold hub rivalry is complete without acknowledging the scale of Hong Kong’s ambitions. Hong Kong signed a cooperation pact with the Shanghai Gold Exchange and reiterated a pledge to expand gold-storage capacity to 2,000 tons within three years. A public campaign unveiled this year promotes the special administrative region as a trading, financing and storage hub for gold, with a government-run clearing system slated to begin trials this year.
Hong Kong’s trump card is proximity to mainland China — the world’s largest consumer and one of its largest producers of gold. All Chinese gold imports flow through the Shanghai Gold Exchange (SGE), creating captive volumes that give Hong Kong structural advantages in physical metal flow. The SGE cooperation pact is designed to extend those flows offshore, creating a mechanism for international investors to access Chinese gold demand through a familiar common-law jurisdiction.
But the Hong Kong model has vulnerabilities that Singapore is quietly exploiting. First, Hong Kong’s geopolitical positioning has become complex since 2020, and a meaningful cohort of international investors and central bankers view its regulatory independence with greater scepticism than in previous decades. Second, the SGE partnership, while commercially powerful, tethers Hong Kong to Beijing’s preferences in ways that could constrain its appeal to the same sovereign clients both cities covet. Third, Hong Kong’s clearing system remains under development — still finalising details of its proposed clearing system, including the type of bars permitted for delivery and the currencies in which trade can be settled.
MAS Deputy Chairman Chee Hong Tat said there is likely room for more than one regional trading centre for gold as rising uncertainty gives more investors reason to pivot to the safe-haven asset. “I think the space is big enough for us to coexist and for both cities to be able to grow our respective services,” said Chee. “There are some overlaps in the clients that we serve and the market segments that we target, but it’s also not completely identical.”
That diplomacy is appropriate. But the reality is that for central banks outside China’s sphere of influence — those in Southeast Asia, South Asia, the Middle East, and parts of Africa and Latin America that are actively diversifying reserve locations — Singapore and Hong Kong are not complementary; they are alternatives. Singapore’s pitch to this cohort rests on three durable advantages: political neutrality, regulatory credibility, and a track record of building world-class financial infrastructure without the complications of a major superpower’s hand on the tiller.
Dubai, the other significant rival for Asia-Pacific gold trading hub status, has carved out a genuine niche in physical gold — particularly for African production flowing towards Asian consumption. But its regulatory ecosystem for capital-market products is still maturing, and it lacks Singapore’s bench strength in institutional banking, derivatives, and financial technology.
London, the global benchmark, faces a different kind of threat: relevance drift. The post-Brexit fragmentation of European financial markets, combined with growing Asian dissatisfaction with a pricing benchmark set entirely outside their time zone, creates structural demand for a credible Asian alternative. Singapore is the only candidate with the institutional depth to satisfy that demand comprehensively.
The Economic Case: Jobs, Revenue, and Financial Resilience
Singapore’s gold-hub ambitions are not merely about prestige. The economic dividend from establishing the city-state as a genuine Singapore bullion market centre is measurable and meaningful. MAS and SBMA noted: “Our goal is to anchor high-value activities here, create good jobs for Singaporeans, enhance the resilience and diversity of Singapore’s financial sector, and benefit market participants in Singapore and the region.”
The job-creation vector runs across multiple domains: vaulting and logistics operations requiring highly specialised security and technical skills; trading and relationship management roles that would see Singapore-based professionals managing bullion flows across the region; research and analysis functions supporting pricing, risk management, and market intelligence; and compliance and regulatory roles as the ecosystem scales. Each segment represents high-value employment that aligns with Singapore’s broader strategic objective of moving up the economic value chain.
There is also a financial-sector resilience argument. Singapore’s economy is uniquely exposed to global trade flows and financial-market volatility. A thriving gold ecosystem — which tends to perform precisely when other financial assets are under stress — would provide a countercyclical buffer for the city-state’s economy, reducing correlated risk across its financial-services sector. Gold’s demonstrated capacity to retain value during periods of geopolitical turbulence, dollar weakness, and financial-market dislocation makes it an attractive addition to Singapore’s financial product mix.
The tax revenue implications are harder to quantify but potentially significant. Singapore’s zero-GST treatment of investment-grade precious metals already attracts substantial bullion import and export activity. A deeper ecosystem — one that includes clearing, settlement, central-bank custody, and listed derivatives — would generate substantial transactional and corporate tax flows, as well as income from the highly paid professionals it attracts.
Risks and Challenges: The Road From Ambition to Infrastructure
Intellectual honesty requires acknowledging the headwinds. Building a genuine Asia gold trading liquidity 2026 hub is not a matter of announcing working groups and waiting for the market to arrive. London’s primacy is self-reinforcing: it commands the deepest liquidity pool precisely because the deepest liquidity pool is already there. Persuading traders, banks, and institutional investors to shift settlement and pricing activity to Singapore requires a critical-mass threshold that is genuinely difficult to reach.
The MAS SBMA gold market development working group has wisely sequenced its ambitions — beginning with infrastructure and standards before capital-market products, and with an explicit acknowledgment that implementation details will take months to finalise. This is prudent. Rushed infrastructure in gold markets creates precisely the kind of settlement uncertainty that drives sophisticated clients back to established hubs.
Regulatory alignment with LBMA standards, in particular, requires careful bilateral engagement. The LBMA’s accreditation processes for Good Delivery refiners and vault operators are rigorous and time-consuming. Singapore will need to demonstrate that its standards are not merely internationally “aligned” but genuinely interoperable — that a bar vaulted in Singapore can move seamlessly into and out of the London market without friction.
The geopolitical environment, while providing the tailwind for gold demand, also creates complexity. Central banks remained firm buyers of gold in 2026, even as prices were skyrocketing to records in January, though the institutions’ appetite for bullion could face a stern test amid rising geopolitical tensions in the Middle East. A prolonged conflict that pushes energy prices materially higher could sustain inflationary pressures that complicate interest-rate trajectories — creating short-term headwinds for gold prices even as structural demand remains intact. Singapore’s hub ambitions are a decade-long project; short-term price volatility is noise.
Finally, there is the challenge of liquidity chicken-and-egg dynamics. Derivatives markets need market-makers; market-makers need volume; volume requires end-users; end-users require liquidity. Breaking this circularity requires either regulatory mandates (which MAS has historically been reluctant to impose) or creative commercial incentives that bring anchor market-makers into the ecosystem early. The presence of JPMorgan Chase and UBS in the working group suggests that tier-one international banks are prepared to play this role — but their commitment to active market-making in Singapore-listed gold products remains to be demonstrated in practice.
What This Means for Global Investors and the Future of Asian Finance
For institutional investors and family offices, Singapore’s gold-hub initiative is worth watching closely for two reasons. First, the Singapore gold-related capital market products that emerge from the working group will create new instruments for accessing Asian gold markets — potentially including ETFs, forwards, and structured notes that offer superior cost and settlement efficiency compared to routing through London or New York. Second, and more broadly, Singapore’s emergence as a MAS gold vaulting centre for sovereign entities signals a structural shift in where the world’s financial infrastructure is being built.
The city-state’s strategic gambit is fundamentally a bet on three durable trends: the continuing shift of economic weight to Asia, the sustained de-dollarisation impulse among emerging-market central banks, and the structural demand for gold as a hedge against geopolitical entropy. All three trends have powerful momentum and are unlikely to reverse in the medium term.
Turning Singapore into what one might call the Zurich of the East — a politically neutral, impeccably regulated custodian of global wealth, positioned at the intersection of the world’s most dynamic economic geography — would represent one of the most consequential feats of financial statecraft in Asia’s modern economic history. The working group’s mandate runs through 2026, with periodic implementation updates promised. By year-end, the contours of Singapore’s new gold architecture should be clear.
Gold, after all, has always been less about the metal itself than about the institutions trusted to hold it. Singapore, on March 27, 2026, announced its candidacy for that trust at a regional scale. The audition has begun.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


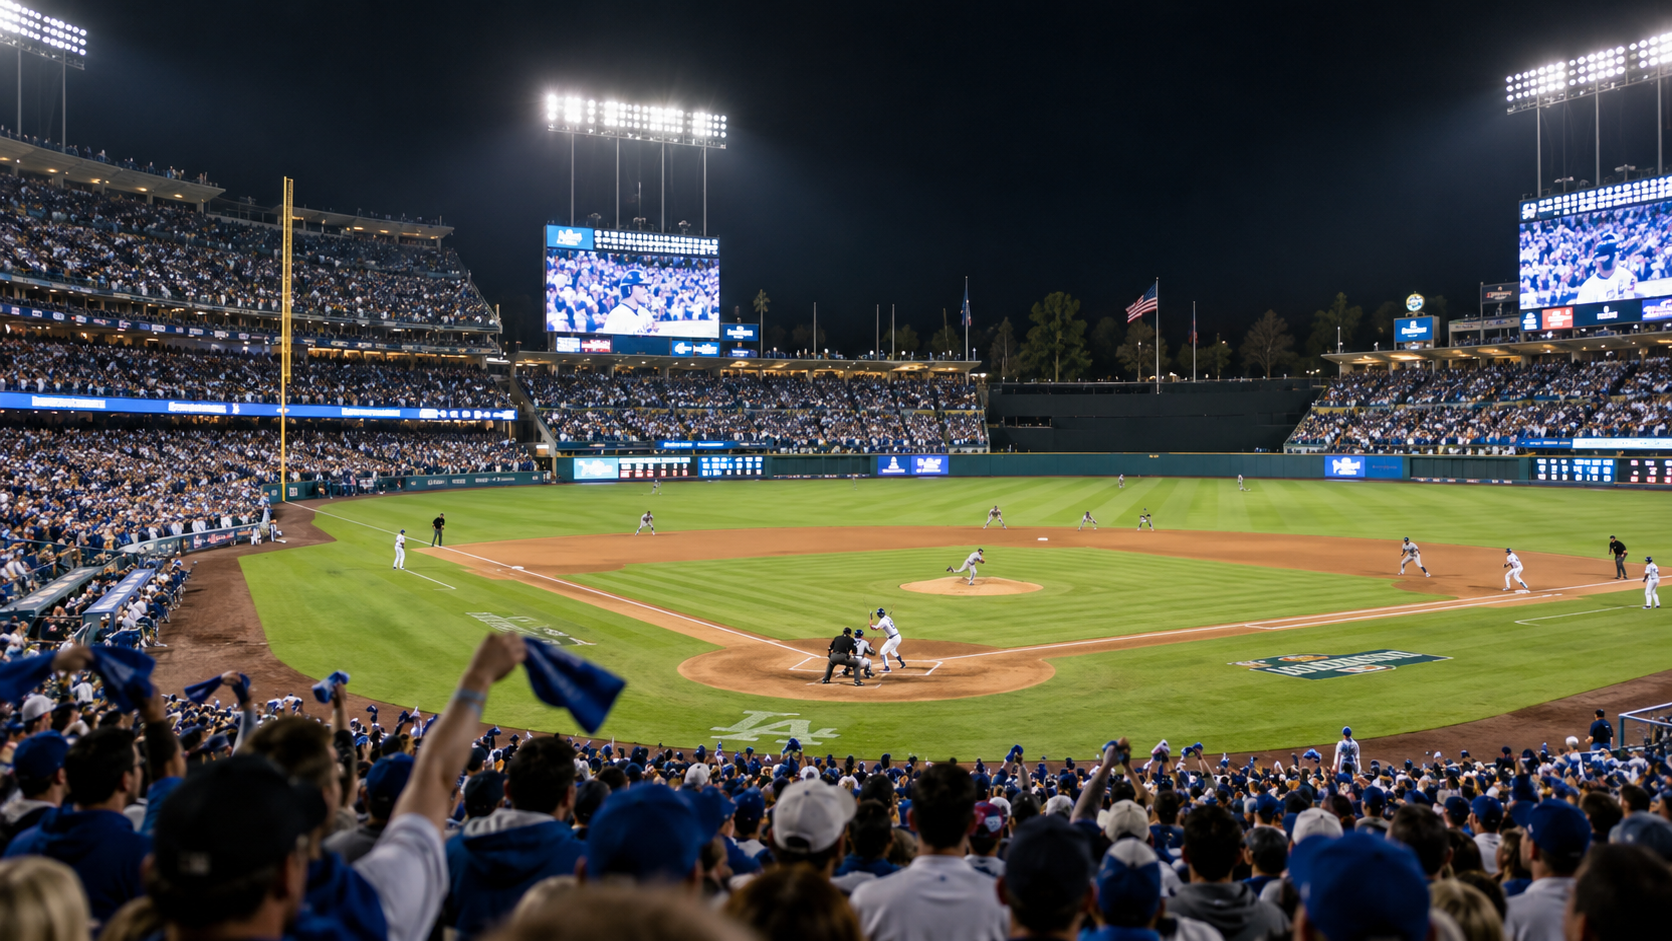
October is Major League Baseball’s postseason month, with the League Championship Series leading toward the World Series. MLB’s official October 9 update listed league championship broadcasting arrangements and said its complete postseason schedule was subject to change. That is the appropriate basis for a service article, rather than relying on viral bracket graphics. Sources: MLB and NBA.
The important context competitors can overlook
The playoff path moves through the Wild Card Series, Division Series, League Championship Series and World Series. Series lengths differ, affecting travel planning, pitching strategies and when a potential deciding game may occur. Weather, broadcast adjustments and series ending early can all change the actual date of a matchup. A guide should therefore distinguish tentative “if necessary” games from guaranteed events. For primary-source checks and current reporting, see MLB and NFL. The key distinction is practical broadcast and bracket explainer with no fictitious results.
October baseball moves through elimination series toward the World Series. Games marked ‘if necessary’ depend on earlier series results. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
Use MLB’s live bracket and broadcast information for tonight’s specific matchup, while this article provides the enduring format explanation. If publishing a result, record the completed date and source. Viewers should check the network, streaming eligibility and local restrictions before paying. Avoid declaring future participants or game outcomes without an official final score.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Where is the authoritative 2026 playoff schedule? MLB publishes and updates it at MLB.com/postseason.
Why are some dates marked if necessary? Best-of-series matchups end once a team wins the required number of games.
How the MLB postseason bracket works
Major League Baseball’s postseason includes division winners and wild-card teams, followed by a sequence of elimination series that eventually determines each league champion and the World Series participants. The rounds use different series lengths; that affects pitching strategy, bullpen workload and how quickly a team can be eliminated. A single-game result in a best-of-series contest is important but not always decisive. Readers should consult MLB’s official postseason hub for the bracket rather than rely on an old graphic that may not reflect completed games.
Home-field advantage, seeding and tiebreaking rules add context to the matchup schedule. Those details can vary by competition edition, so the official rules should be checked instead of recycled from a prior year. When a postseason series has not yet finished, the next opponent remains conditional. An article should say “winner of Series A will face…” rather than assign a future opponent before the result exists.
Why starting pitching changes a short series
Starting pitchers often shape the first half of a game, but playoff success requires bullpen management, defense, baserunning and timely hitting. A team may start its most experienced pitcher in the first game and then adjust the rotation based on rest, health and earlier results. Managers must also decide when to use their strongest relief pitchers. Those choices can matter more in a short series than in a long regular season where roles and workloads can be smoothed across many games.
Baseball statistics need sample-size discipline. A hitter’s performance over ten postseason plate appearances tells less about underlying ability than a much longer period of play. Analysts can compare strikeout rates, on-base production and matchup tendencies while avoiding exaggerated claims drawn from one home run or one defensive error. Recent injuries and announced starting lineups can change the outlook quickly.
Broadcast rights and local time differences
A game carried by a U.S. broadcaster may require a different provider for an international audience. Some streaming services include blackout restrictions and authenticated subscriptions. Before directing readers to a platform, check the league’s official listing for the game, region and date. A schedule can shift because of series outcomes or weather; do not assume every potential Game 6 or Game 7 will occur. Conditional games should be clearly labeled so viewers do not subscribe or travel based on a nonexistent fixture.
Fans outside North America should verify dates carefully. A game beginning late at night in U.S. Eastern Time can appear on the following morning in Pakistan or elsewhere. A credible global article uses time-zone labeling and, where practical, provides local conversions while directing readers to official confirmations.
Planning a trip to a postseason game
Buy tickets through the team’s verified ticket office or a recognized authorized resale route. Read what happens to a ticket for an “if necessary” game that is never played. Lodging and transportation may be nonrefundable even when the ticket itself is refunded under a particular policy. Stadium entry rules, bag restrictions and transport can vary by venue. Travel budgets should include potential schedule shifts, especially when the identity of the next opponent is not yet known.
Reseller offers that look dramatically cheaper than the going rate can be fraudulent. Confirm seat location, transfer method and the platform’s buyer-protection terms. Never assume an image of a barcode sent by a stranger proves a usable ticket. The simplest defense is to purchase through verified channels and retain the order record.
A bracket-tracking method that stays accurate
For each series, maintain the teams, seeds, current games-won tally, next confirmed game time, probable or announced starters, broadcaster and a direct MLB link. Update each row only after official results. Distinguish “clinched” from “leads series.” If a matchup concludes earlier than its maximum length, remove unused dates or mark them canceled; otherwise a static editorial calendar can appear inaccurate within hours.
The purpose of a postseason guide is not to predict every winner. It is to make a fast-moving bracket understandable and give fans reliable answers on what happens next, where to watch and which details remain uncertain.
Baseball postseason questions answered
Does every potential game on a postseason schedule occur?
No. A best-of-seven series ends when one team reaches four wins. Games listed as “if necessary” do not take place if the series has already been decided. Ticket buyers and travelers should understand refund or cancellation policies associated with those conditional dates before arranging flights and hotels.
Why do playoff teams use pitchers differently?
A shorter series changes the cost of saving an elite relief pitcher or spacing starting assignments. Managers may make aggressive substitutions to protect a narrow lead, while maintaining enough arms for a possible next game. Such choices can look different from regular-season strategy, when teams plan around a longer schedule and broader workload management.
Can a postseason match move after its first announcement?
Yes. Broadcast planning, prior series results and circumstances such as weather can affect schedules. MLB’s official game page and league notices should be checked shortly before travel or viewing. An editorial table that fails to update conditional games can easily mislead readers as the bracket advances.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
SpaceX CEO Elon Musk has escalated a public dispute over Starlink’s delayed commercial launch in India, sarcastically addressing Reliance Industries Chairman Mukesh Ambani as “Prime Minister Ambani” and questioning whether he holds outsized influence over the country’s telecom landscape. The remarks, posted on X in early October 2026, center on claims that entrenched interests—particularly around Reliance Jio—are slowing satellite broadband approvals to protect market dominance. Indian authorities have rejected the accusations as baseless, emphasizing a uniform regulatory process for all licensed satellite operators. Bloomberg
Musk’s Escalating Posts and Arguments for Starlink
Musk first accused unnamed “oligarchs” of blocking Starlink to maintain a “monopolistic chokehold on the Indian people,” describing the situation as “a crime against the people of India.” He followed by asking, “Is Ambani the real boss of India?” after noting that Starlink is licensed in over 165 countries and has spent five years complying with Indian requirements. In a subsequent post addressed as “Dear Prime Minister Ambani,” he offered a “humble apology” for not recognizing Ambani’s role and urged him to allow competition, arguing that satellite internet could connect underserved areas. Times of India
Musk highlighted potential benefits: improved access for children to education, opportunities for small businesses to reach global markets, and life-saving connectivity during natural disasters when terrestrial networks fail. He later pushed back against critics, stating that competition would benefit Indian consumers with more choices, that Ambani “is not going out of business,” and that Starlink would need affordable pricing to gain traction. Times of India
Government Position: No Monopoly, Uniform Rules for All Licensees
Union Communications Minister Jyotiraditya Scindia has directly addressed the claims, stating that “India does not allow a monopoly in any sector.” He confirmed that three companies hold Global Mobile Personal Communication by Satellite (GMPCS) licences: Starlink, Reliance’s Jio Satellite Communications, and Bharti-backed Eutelsat OneWeb. All three are at a similar regulatory stage and can begin commercial services only after each individually completes security clearances (assessed primarily by the Ministry of Home Affairs) and the government finalizes the revenue-based spectrum charging framework. CNBC TV18
The Department of Telecommunications has described suggestions of discriminatory treatment as “baseless and misconceived.” Security requirements include data localization, lawful interception capabilities, Indian gateways, and related technical demonstrations—conditions that apply equally across licensees. Spectrum assignment is set to be administrative rather than auction-based, with a usage charge of around 5% of adjusted gross revenue (lower for rural/remote areas) nearing finalization with the Telecom Regulatory Authority of India. Business Standard
Starlink’s Approval Timeline and Remaining Hurdles
Starlink received its GMPCS licence from the Department of Telecommunications in June 2025 and IN-SPACe authorization for its Gen-1 constellation in July 2025, following years of engagement that began with an application around November 2022. Provisional spectrum for testing has been available in some cases, but commercial operations require the outstanding security clearances and spectrum assignment. OneWeb and Jio Satellite secured earlier licences but face the same final milestones. Amazon’s Project Kuiper has also expressed interest and is under review. Business Standard
India’s Telecom Landscape and Connectivity Gaps
Reliance Jio remains India’s largest wireless operator, with roughly 500–530 million connections and about 39% market share as of mid-to-late 2026 data, closely trailed by Bharti Airtel at around 38%. Together the two private players dominate the market, with Vodafone Idea and BSNL holding smaller shares. Jio has driven significant growth in 5G adoption and fixed broadband. TelecomLead
Despite high overall coverage, a digital divide persists. TRAI and related data show India with over 1.09 billion internet subscriptions as of early 2026, but rural penetration stands at about 48 subscriptions per 100 people versus roughly 127 in urban areas. Large numbers of people live within mobile broadband footprints yet do not use the internet, with rural-urban gaps remaining notable. Satellite services are positioned by regulators as particularly suited for remote, border, hilly, and island areas that are harder to serve with terrestrial infrastructure. Government programs such as BharatNet continue expanding fiber and mobile coverage in villages. The Policy Edge
Broader Implications
The exchange underscores tensions between global satellite broadband ambitions and national regulatory, security, and competitive frameworks in one of the world’s largest telecom markets. Proponents of faster Starlink entry argue it could accelerate connectivity in hard-to-reach areas and introduce pricing and service competition. Authorities maintain that the process prioritizes security, data protection, and a level playing field among multiple licensed players rather than favoring any single incumbent. As of mid-October 2026, commercial satellite broadband services from any of the three licensees have not yet launched, pending the completion of remaining individual clearances and spectrum finalization.
Musk’s posts have drawn responses from opposition figures, including Rahul Gandhi, but the core dispute remains centered on the pace and nature of regulatory approvals for satellite internet in India. Further clarity is expected once security assessments conclude and the spectrum pricing regime is formally implemented.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
“Min Ah” is one of the most searched names in Korean drama, and it points to more than one actress. The one driving the biggest buzz right now is Shin Min-a.
Key Takeaways
- Biggest news: Shin Min-a stars as Empress Navier in Disney+’s The Remarried Empress, which premieres November 4, 2026, per Soompi.
- Cast: Ju Ji-hoon plays Emperor Sovieshu, Lee Se-young plays Rashta, and Lee Jong-suk plays Prince Heinrey.
- Scale: the story is based on a web novel and webtoon that recorded about 2.97 billion cumulative global views as of July 2026, and it is Disney+’s first K-romance fantasy (SBS Star).
- Name confusion: other well-known “Min Ah” performers include Kang Min-ah and Minah (Bang Min-ah) of Girl’s Day. This article explains who is who.
| Name | Known for | Latest news |
|---|---|---|
| Shin Min-a | Leading roles in major dramas and films | The Remarried Empress (Nov 4, 2026) |
| Kang Min-ah | Actress represented by H&Entertainment | Drama Sympathetic Cells with Kim Myung-soo; premiere date announced June 2026 (MyDramaList) |
| Minah (Bang Min-ah) | Former Girl’s Day member turned actress | Born May 13, 1993; Girl’s Day debut in 2010 (Dramabeans) |
Shin Min-a’s Next Big Role: The Remarried Empress
Disney+ confirmed on August 26 that the series would premiere on November 4, releasing a teaser and character posters (Soompi). The story follows Navier, the “perfect empress” of the Eastern Empire, who is told by her husband that he wants a divorce after he falls for a runaway slave, Rashta. Instead of accepting defeat, Navier asks permission to remarry, choosing the prince of a rival kingdom.
Release plan
According to industry coverage, the ten-part series will debut with a four-episode drop and then release two episodes each Wednesday through a November 25 finale, and it streams on Hulu in the U.S. (Resonate). The same report says the first three episodes will screen at the Busan International Film Festival, which runs October 6–15.
Why it matters
This is the clearest sign of how K-drama has become a global asset. Platforms are paying for fantasy adaptations of internet-born stories with huge built-in audiences, and they are casting established leads to carry them.
Why Shin Min-a’s Popularity Travels
- Longevity. She has worked consistently in Korean drama since the early 2000s, and her credits on MyDramaList span more than two decades (MyDramaList).
- Genre range. From romantic comedy to Netflix thriller Karma and a 2026 film, The Eyes, in which she plays dual roles (MyDramaList).
- Global platforms. Disney+, Netflix, and Hulu give Korean series simultaneous worldwide releases.
The Other “Min Ah” Actresses
Kang Min-ah
A Seoul-born actress with credits since the 2010s. MyDramaList lists a 2026 drama, Sympathetic Cells, with Kim Myung-soo, whose premiere date was announced in June (MyDramaList).
Minah (Bang Min-ah)
She debuted with Girl’s Day in 2010, made her acting debut on the tvN variety program Roller Coaster, and later won a Best New Actress trophy at the 2013 Gwangju International Film Festival for the film Holly. She led the 2020 film Snowball, which earned a Screen International Rising Star Asia Award at the New York Asian Film Festival (Dramabeans).
How to Search the Right Person
Add the family name: “Shin Min-a,” “Kang Min-ah,” or “Bang Minah.” Spelling varies in English (Min-a, Mina, Min Ah), which is why results get mixed.
Frequently Asked Questions
Who is Min Ah in K-drama?
There are several, but the most prominent right now is Shin Min-a, starring in The Remarried Empress.
When does The Remarried Empress premiere?
November 4, 2026, on Disney+ (Soompi).
Who is in the cast?
Shin Min-a, Ju Ji-hoon, Lee Jong-suk, and Lee Se-young.
Is Min Ah the same as Minah from Girl’s Day?
No. Minah is Bang Min-ah, a different performer (Dramabeans).
How popular is the source story?
The webtoon had about 2.97 billion global views as of July 2026 (SBS Star).
Whichever Min Ah you were searching for, the pattern is the same: Korean drama talent now finds its audience everywhere at once.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

MLB Playoffs 2026: Postseason Format, Broadcast Guide and How to Track the Bracket

Elon Musk Calls Mukesh Ambani the “Real Boss of India” Over Alleged Monopoly Concerns

Legal Pioneer and Defender of Justice: The Life, Works, and Legacy of Navi Pillay

Inside the Modern Republican Party Platform: Tax Policy, Immigration, and Governance

Anne Carson: Genius of Hybrid Forms and 2026 Nobel Laureate in Literature

Analyzing the Republican Voter Enthusiasm Gap: Turnout Metrics and Polling Data

The West Wing Legacy: Why the Political Drama Is More Relevant Than Ever

Remembering Kianna Underwood: The Nickelodeon Actress Behind “All That” and “Little Bill”

Min Ah: The Global Impact and Rising Popularity of the K-Drama Star

Pakistan Warns UN Security Council of AI Risks to Global Peace and Equality

Bloodhound Q50: Remembering the Tragic Loss of Chicago’s Rising Drill Star

Remembering Eliana Moreno: The Legacy of NBC LA’s “Eli in the Heli”

Horror Box Office Economics: ROI, Market Share and the 2026

iOS 27 Release Date & Siri AI: The Ultimate Tech News Guide for iPhone 18 Users
Min Ah: The Global Impact and Rising Popularity of the K-Drama Star

Fortress Diplomacy: How China’s Secretive Hongqi N701 Matches America’s Legendary “Beast”

Rep. Thomas Massie’s Impeachment Push Against Pete Hegseth, Explained
Remembering Kianna Underwood: The Nickelodeon Actress Behind “All That” and “Little Bill”
-

 Featured5 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Democracy5 years ago
Missing You! SPSC
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills