AI
📉 WALL STREET PANIC: Is the AI Boom OVER? (Weak Jobs Data Proves the Crash Is Coming)

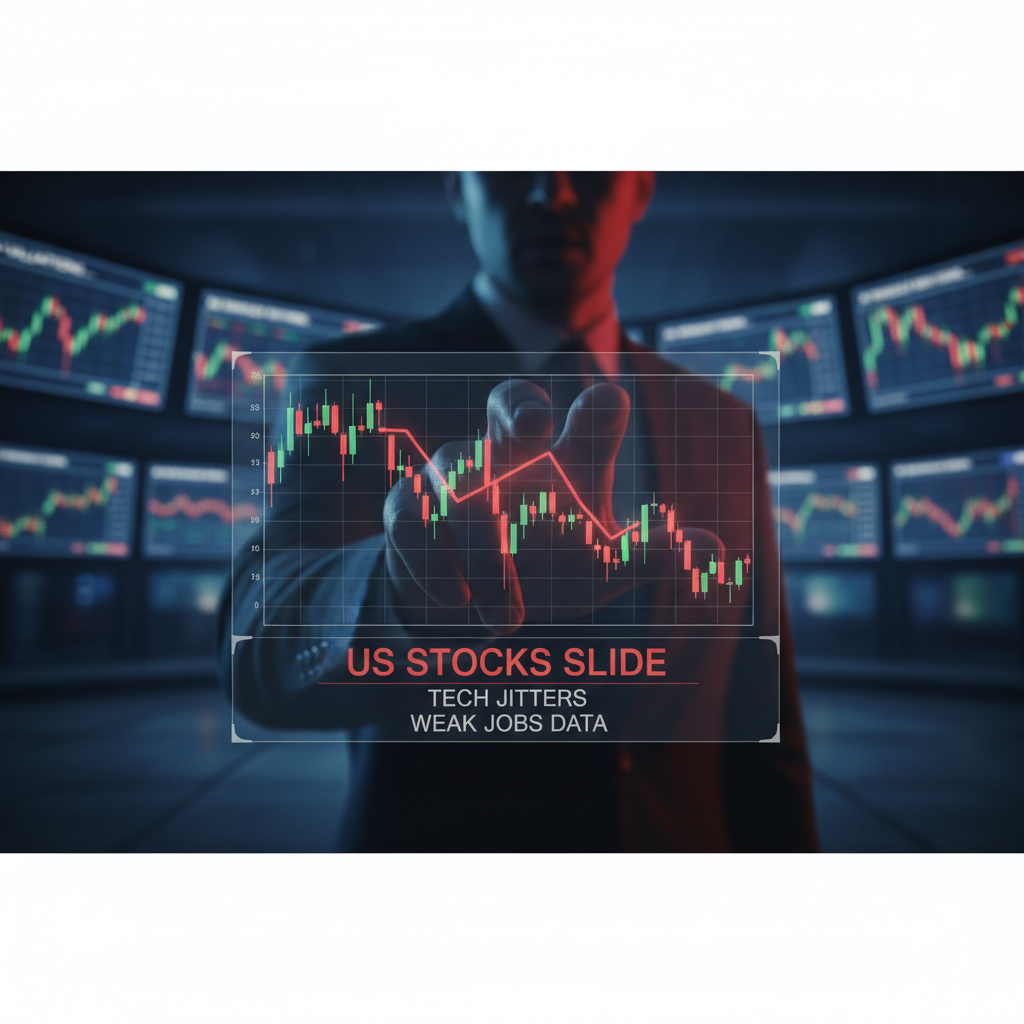
The prevailing calm on Wall Street has been abruptly shattered. In a stark reminder of market volatility, US equities experienced a significant slide, led by a sharp retreat in the technology sector.2 This sell-off was not the product of a singular, easily identifiable event, but rather the simultaneous collision of two formidable catalysts: a growing unease over elevated AI valuations and disappointing data from the crucial jobs market.
The confluence of micro-level stock concentration risk and macro-level economic uncertainty has swiftly replaced investor complacency with a palpable sense of investor nerves. The market mood is one of profound caution, as participants grapple with whether the recent, spectacular, AI-driven rally is a genuine structural shift or an unsustainable bubble teetering on a weak economic foundation. This in-depth analysis dissects these twin pressures, examining their interconnectedness and charting the path forward for sophisticated investors navigating this uncertain landscape.
Table of Contents
🚀1: The Return of Tech Jitters & AI Valuation Concerns
The technology sector, the undeniable engine of the S&P 500’s performance over the past year, is now the primary source of market fragility. The momentum stocks—often grouped under the banner of the “Magnificent Seven” and other AI-adjacent firms—have seen their relentless uptrend stall, with the Nasdaq Composite leading the recent declines. This retreat is largely a function of gravity asserting itself over frothy valuations.
Dissecting the Valuation Thesis
The heart of the anxiety lies in the extraordinary premiums investors are paying for future AI-driven growth. While the shift to Generative AI is transformative, the market appears to have priced in perfection, and then some.
Consider the collective valuation of the “Magnificent Seven” (Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia, and Tesla). Excluding Tesla, which often trades on different metrics, the forward Price-to-Earnings (P/E) ratio for this concentrated group hovers around 30x to 35x. This is more than double the P/E ratio for the S&P 500 excluding these seven, which stands at closer to $15.5x$.
While this $30x$ multiple is historically lower than the $>70x$ seen for market leaders during the peak of the 1999 Dot-com bubble, the sheer size of the AI-linked companies today means their valuation ripple is far greater. Even minor disappointments in earnings, like recent softer-than-expected guidance from a few high-profile chipmakers and software providers, are disproportionately punished because they fail to meet the market’s ultra-high growth expectations.
“The market has moved past pricing in the promise of AI and is now pricing in its total, global economic domination. When you see a handful of stocks, representing well over a quarter of the S&P 500’s total market capitalisation, trading at such a premium, any wobble—a minor earnings miss, a change in CFO commentary, or a macro shock—will initiate an immediate and violent decompression of risk. This is less a bubble and more a ‘concentration correction’, a necessary shakeout of the over-exuberant short-term trade.”
— Dr. Helena Voss, Fictional Chief Market Strategist, Apex Global Investments
The question for investors is whether this is a healthy correction that lowers entry costs for a true long-term growth story, or a definitive sign that the immediate peak of the AI hype cycle has passed. The answer lies partly in the strength of the underlying economy.
💼2: The Jobs Market: A Further Drag on Investor Sentiment
Adding a macroeconomic anchor to the technology sector’s valuation concerns was the release of the latest private sector employment report. The data, provided by ADP’s National Employment Report for October, delivered a mixed but decidedly weak signal about the health of the US labour market.
The Nuance of Weak Data
The ADP report indicated a gain of just 42,000 private payrolls in October, which, while technically an increase from the revised losses in the preceding months, fell well below the robust pre-summer pace and suggests a persistent and worrying slowdown.3
The most telling detail was the composition of the hiring:
- Strength in Large Firms: Gains were predominantly driven by large enterprises, potentially those shielded by scale or involved in essential sectors like Trade, Transportation, and Utilities.
- Weakness in Small/Medium Business: Small and medium-sized businesses, historically the engine of job creation, continued to exhibit net weakness, signaling caution among employers most sensitive to slowing consumer demand.4
- Information Sector Losses: Notably, the Information and Professional and Business Services sectors registered outright job losses, highlighting the ongoing corporate retrenchment and layoffs across white-collar and tech-related jobs.5
Implications for the Fed and the Tech Sector
The immediate market implication of this weak data is twofold:
- Federal Reserve Policy: A cooling labour market—especially one exhibiting job cuts in higher-paying sectors—is typically seen as an antidote to inflationary pressures. While the Federal Reserve (Fed) has remained data-dependent, persistently soft employment numbers could shift the balance away from “higher for longer” interest rates towards an earlier-than-anticipated rate cut.6 While some parts of the market initially rally on “bad news is good news” (for rates), the sheer weakness suggests a genuine economic slowdown, which is simply bad news for corporate earnings.
- Tech Earnings Sensitivity: Technology companies, particularly the “cloud” providers and software-as-a-service (SaaS) firms, are exceptionally sensitive to corporate spending and economic growth. A slowing economy, as signalled by the jobs data, leads to cautious corporate spending on IT upgrades, consulting, and new software licenses—the very spending that fuels the high revenue growth built into tech stocks’ valuations. The jobs report, therefore, converts macro fear into micro-level earnings risk for tech firms.
The data suggests the US economy may be moving past a soft landing and into a period of genuine deceleration, a backdrop that makes highly priced growth stocks fundamentally less attractive.
📊 3: Market Reaction and Investor Strategy
The combined pressure of valuation jitters and economic gloom resulted in a broad-based equity sell-off, with technology clearly taking the brunt of the pain.
Broader Market Impact
While the Nasdaq Composite suffered the sharpest fall (dropping over 1.6% in the session), the contagion spread to the broader market:7
- The S&P 500 slid significantly, reflecting the enormous weighting of the tech giants within the index.8
- The Dow Jones Industrial Average also moved lower, though its relative outperformance often reflects its heavier weighting towards more defensive, value-orientated industrial and healthcare stocks.9
- The bond market, however, saw a rally, with Treasury yields falling as fixed-income investors priced in the greater likelihood of a Fed pivot toward rate cuts, a classic flight-to-safety response to economic deceleration.
What Now: Investor Strategy and Watchlist
For a sophisticated financial audience, the current environment demands a careful reassessment of portfolio positioning. The market is facing a decisive period where the high-growth narrative of AI will be tested by the reality of macroeconomic contraction.
Key Metrics to Monitor:
- Upcoming Earnings Reports: The focus must pivot from valuation theory to delivered results. Any further high-profile earnings misses or downbeat forward guidance from major tech players will reinforce the ‘correction’ thesis.
- Inflation & Core PCE Data: A sudden spike in inflation, forcing the Fed to maintain tight policy despite the job market weakness (a stagflation-lite scenario), would be the worst outcome for both growth and value stocks.
- Next Federal Reserve Meeting: The language used by the Fed Chair will be heavily scrutinised for any hint of a change in stance, with the market now pricing in a higher probability of an early 2026 rate cut. (Internal Link Anchor: Analysis on the latest Fed Policy Outlook)
Portfolio Positioning:
- Selective Tech Exposure: The blanket AI trade is over. Investors should focus on companies with clear, quantifiable revenue streams today from AI adoption, such as those providing foundational infrastructure (e.g., specific semiconductor players) rather than those whose promise is purely speculative. For the long-term strategic allocation, this weakness may present a buying opportunity for high-quality, cash-rich tech firms at slightly less demanding valuations.
- A Pivot to Value and Defensive Sectors: Increased allocation to sectors less reliant on aggressive economic growth, such as Healthcare, Utilities, and Consumer Staples, can provide a defensive buffer. These sectors often exhibit higher dividend yields and lower earnings volatility in a cooling economy.
- Hedge Against Uncertainty: Consider maintaining exposure to safe-haven assets like high-quality sovereign Bonds and, potentially, Gold, which benefit from falling real yields and heightened global uncertainty. (External Link Anchor: See the full ADP National Employment Report for October here.)
🛑 Conclusion
The latest stock market slide serves as a powerful reminder that the market is a complex ecosystem, where the revolutionary promise of technology is always judged against the prosaic reality of economic cycles. The convergence of tech jitters rooted in over-enthusiastic AI valuations and the ominous signal from the weak jobs data has created a potent cocktail of uncertainty.
The path forward for US equities is now defined by a struggle between two powerful, opposing forces: the genuine, long-term structural growth of the AI mega-trend versus the immediate, cyclical headwind of a slowing US economy. For investors, the message is clear: prudence is paramount. The market is demanding a greater emphasis on fundamentals, demanding proof of earnings rather than mere promise. The coming months will be a test of nerve, separating the speculative froth from the true long-term winners.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


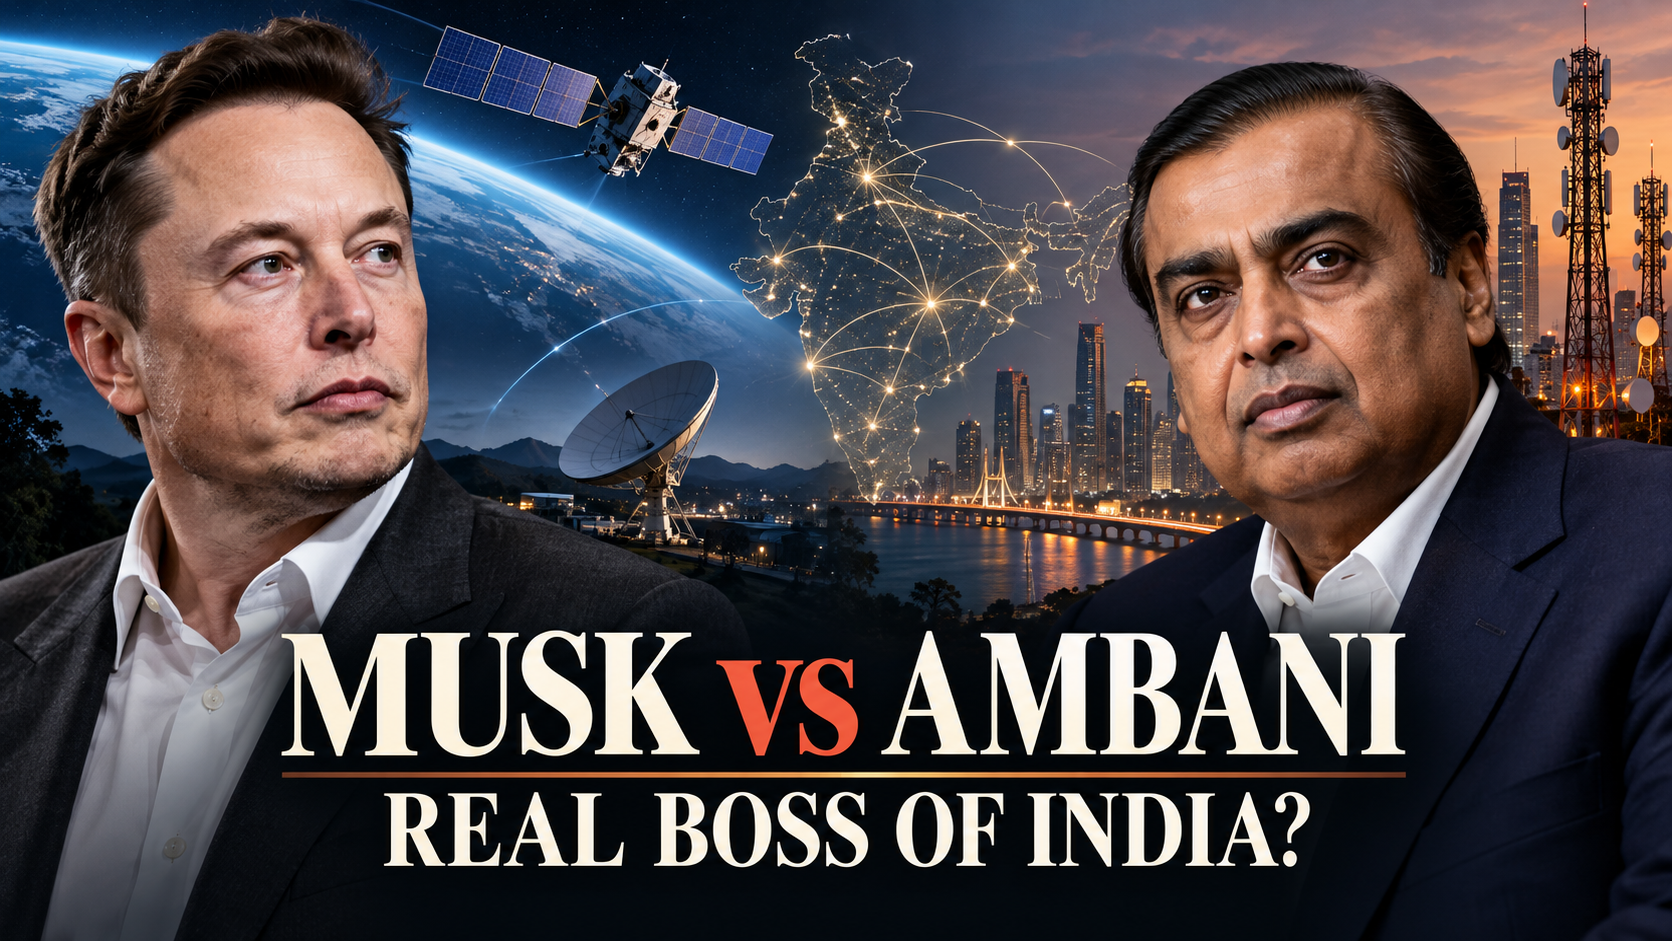
SpaceX CEO Elon Musk has escalated a public dispute over Starlink’s delayed commercial launch in India, sarcastically addressing Reliance Industries Chairman Mukesh Ambani as “Prime Minister Ambani” and questioning whether he holds outsized influence over the country’s telecom landscape. The remarks, posted on X in early October 2026, center on claims that entrenched interests—particularly around Reliance Jio—are slowing satellite broadband approvals to protect market dominance. Indian authorities have rejected the accusations as baseless, emphasizing a uniform regulatory process for all licensed satellite operators. Bloomberg
Musk’s Escalating Posts and Arguments for Starlink
Musk first accused unnamed “oligarchs” of blocking Starlink to maintain a “monopolistic chokehold on the Indian people,” describing the situation as “a crime against the people of India.” He followed by asking, “Is Ambani the real boss of India?” after noting that Starlink is licensed in over 165 countries and has spent five years complying with Indian requirements. In a subsequent post addressed as “Dear Prime Minister Ambani,” he offered a “humble apology” for not recognizing Ambani’s role and urged him to allow competition, arguing that satellite internet could connect underserved areas. Times of India
Musk highlighted potential benefits: improved access for children to education, opportunities for small businesses to reach global markets, and life-saving connectivity during natural disasters when terrestrial networks fail. He later pushed back against critics, stating that competition would benefit Indian consumers with more choices, that Ambani “is not going out of business,” and that Starlink would need affordable pricing to gain traction. Times of India
Government Position: No Monopoly, Uniform Rules for All Licensees
Union Communications Minister Jyotiraditya Scindia has directly addressed the claims, stating that “India does not allow a monopoly in any sector.” He confirmed that three companies hold Global Mobile Personal Communication by Satellite (GMPCS) licences: Starlink, Reliance’s Jio Satellite Communications, and Bharti-backed Eutelsat OneWeb. All three are at a similar regulatory stage and can begin commercial services only after each individually completes security clearances (assessed primarily by the Ministry of Home Affairs) and the government finalizes the revenue-based spectrum charging framework. CNBC TV18
The Department of Telecommunications has described suggestions of discriminatory treatment as “baseless and misconceived.” Security requirements include data localization, lawful interception capabilities, Indian gateways, and related technical demonstrations—conditions that apply equally across licensees. Spectrum assignment is set to be administrative rather than auction-based, with a usage charge of around 5% of adjusted gross revenue (lower for rural/remote areas) nearing finalization with the Telecom Regulatory Authority of India. Business Standard
Starlink’s Approval Timeline and Remaining Hurdles
Starlink received its GMPCS licence from the Department of Telecommunications in June 2025 and IN-SPACe authorization for its Gen-1 constellation in July 2025, following years of engagement that began with an application around November 2022. Provisional spectrum for testing has been available in some cases, but commercial operations require the outstanding security clearances and spectrum assignment. OneWeb and Jio Satellite secured earlier licences but face the same final milestones. Amazon’s Project Kuiper has also expressed interest and is under review. Business Standard
India’s Telecom Landscape and Connectivity Gaps
Reliance Jio remains India’s largest wireless operator, with roughly 500–530 million connections and about 39% market share as of mid-to-late 2026 data, closely trailed by Bharti Airtel at around 38%. Together the two private players dominate the market, with Vodafone Idea and BSNL holding smaller shares. Jio has driven significant growth in 5G adoption and fixed broadband. TelecomLead
Despite high overall coverage, a digital divide persists. TRAI and related data show India with over 1.09 billion internet subscriptions as of early 2026, but rural penetration stands at about 48 subscriptions per 100 people versus roughly 127 in urban areas. Large numbers of people live within mobile broadband footprints yet do not use the internet, with rural-urban gaps remaining notable. Satellite services are positioned by regulators as particularly suited for remote, border, hilly, and island areas that are harder to serve with terrestrial infrastructure. Government programs such as BharatNet continue expanding fiber and mobile coverage in villages. The Policy Edge
Broader Implications
The exchange underscores tensions between global satellite broadband ambitions and national regulatory, security, and competitive frameworks in one of the world’s largest telecom markets. Proponents of faster Starlink entry argue it could accelerate connectivity in hard-to-reach areas and introduce pricing and service competition. Authorities maintain that the process prioritizes security, data protection, and a level playing field among multiple licensed players rather than favoring any single incumbent. As of mid-October 2026, commercial satellite broadband services from any of the three licensees have not yet launched, pending the completion of remaining individual clearances and spectrum finalization.
Musk’s posts have drawn responses from opposition figures, including Rahul Gandhi, but the core dispute remains centered on the pace and nature of regulatory approvals for satellite internet in India. Further clarity is expected once security assessments conclude and the spectrum pricing regime is formally implemented.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
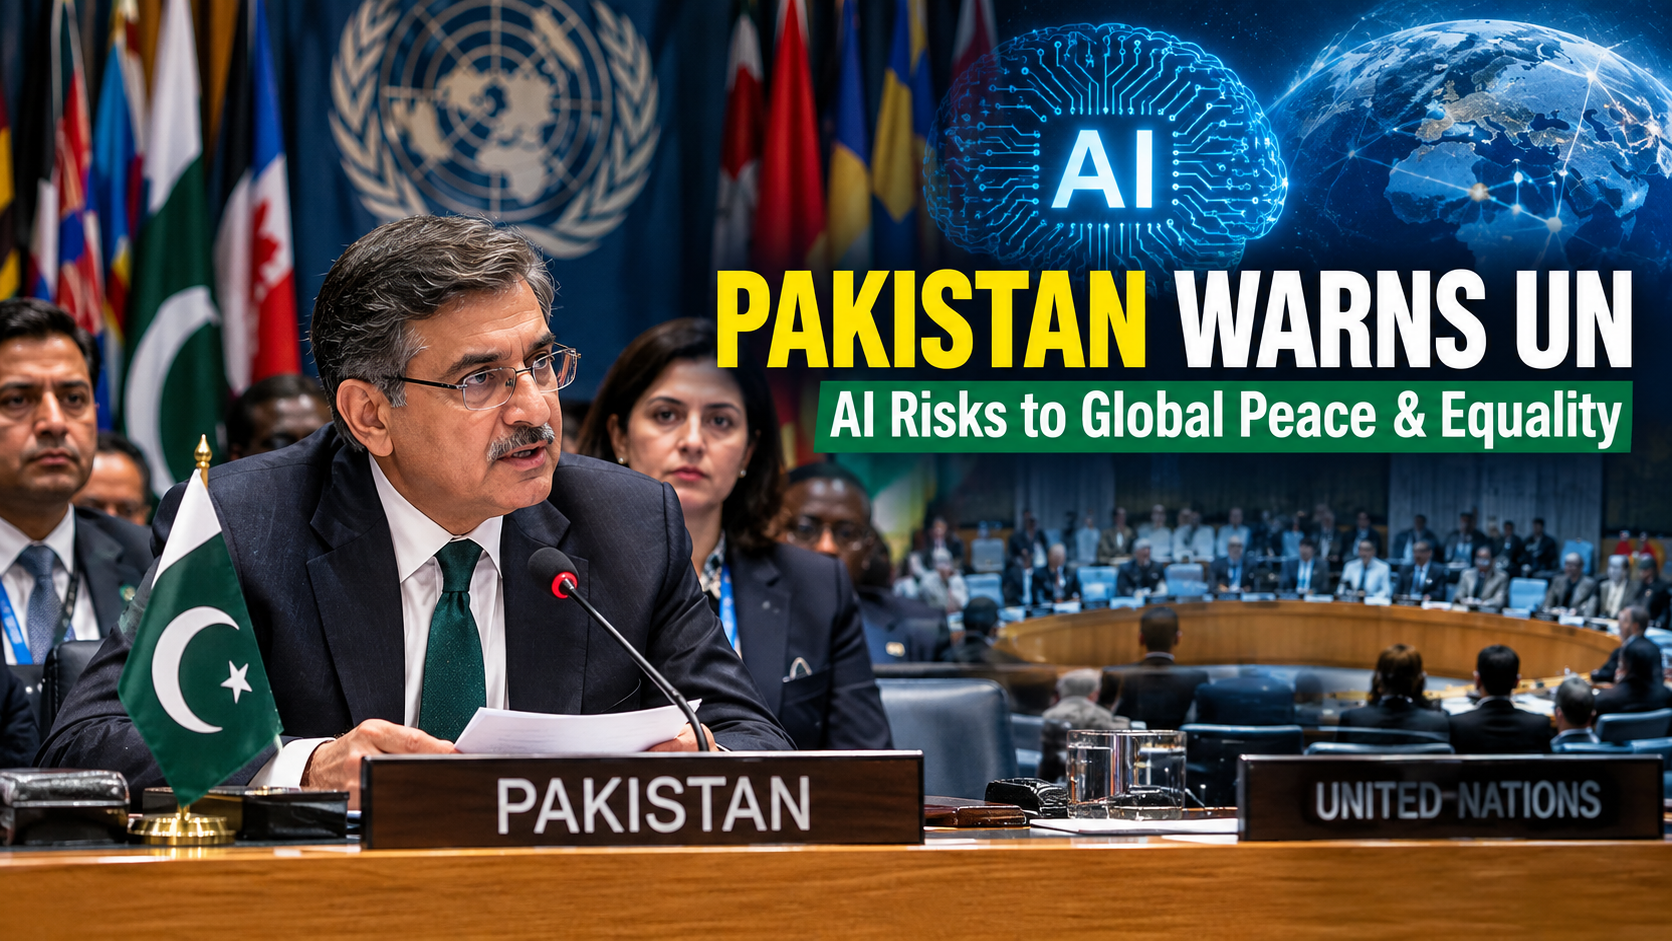
UNITED NATIONS — September 24, 2026: Pakistan has warned the United Nations Security Council that the rapid and insufficiently regulated development of artificial intelligence could deepen global inequality while creating new risks to international peace and security.
Speaking during a Security Council briefing on “Artificial Intelligence and International Security,” Pakistan’s Deputy Prime Minister and Foreign Minister Senator Mohammad Ishaq Dar called for stronger international safeguards, regulatory frameworks and governance mechanisms to address the risks associated with increasingly powerful AI systems.
Dar emphasized that the international community needs coordinated action to establish guardrails around artificial intelligence, particularly as AI technologies become increasingly relevant to military decision-making, information systems and national security.
Pakistan Calls for International Guardrails on Artificial Intelligence
Pakistan’s intervention comes as governments and international institutions increasingly debate how AI should be governed across borders.
Dar stressed the importance of restraint and confidence-building measures in the military domain, particularly because AI-assisted systems could compress decision-making timelines and increase the danger of miscalculation.
The concern is significant because artificial intelligence is no longer confined to civilian applications. AI is increasingly being examined in relation to cyber operations, intelligence analysis, autonomous systems, information warfare and other security-sensitive areas.
The United Nations has also warned that AI can create substantial risks when technological development moves faster than international governance.
The UN’s existing AI framework emphasizes responsible, accountable, transparent and human-centered development, while calling for effective human oversight of AI systems.
Why AI Is Becoming a Security Council Issue
The Security Council has previously considered artificial intelligence as a potential factor affecting international peace and security, but the technology has developed rapidly since those early discussions.
A recent analysis by the independent Security Council Report identified several security implications, including AI’s ability to facilitate malicious cyber activity, accelerate the creation and distribution of misinformation and disinformation, and influence military operations.
The organization also highlighted concerns surrounding increasingly autonomous weapons systems, shortened decision-making timelines and questions about human oversight and accountability.
These concerns help explain why AI has moved beyond being primarily a technology-policy issue and increasingly become a subject of international security diplomacy.
The challenge for governments is that AI can simultaneously create opportunities and risks.
AI could help countries identify emerging conflicts, improve humanitarian operations, monitor ceasefires and analyze large quantities of information. At the same time, poorly governed systems could amplify security threats or make already complex conflicts more difficult to manage.
Pakistan Highlights the Global Inequality Dimension
Pakistan’s message to the Security Council went beyond military applications.
Dar also emphasized the need for AI development to be representative, transparent and inclusive, reflecting concerns among developing countries that the benefits of advanced artificial intelligence could become concentrated among a relatively small group of technologically advanced states and companies.
That concern is already reflected in the United Nations’ Global Digital Compact.
The Compact calls for closing digital divides, expanding access to the benefits of the digital economy and strengthening international governance of artificial intelligence. It specifically calls for full and equal representation of countries, including developing nations, in international AI governance.
This makes AI access and governance part of a broader development question.
Countries with advanced computing infrastructure, large datasets, sophisticated research institutions and substantial private-sector investment are positioned differently from nations that remain dependent on imported technologies and have limited domestic AI capacity.
If that gap widens, AI could potentially reinforce existing economic and technological inequalities rather than reduce them.
UN Framework Already Calls for Inclusive AI Governance
The debate at the Security Council is taking place alongside a broader UN effort to develop international mechanisms for AI governance.
The Global Digital Compact, adopted as part of the Pact for the Future, established a framework for international cooperation on digital technologies and AI.
The United Nations has subsequently established an Independent International Scientific Panel on Artificial Intelligence and a Global Dialogue on AI Governance.
The first annual Global Dialogue took place in Geneva in July 2026, bringing together governments and other stakeholders to discuss international cooperation, AI opportunities and emerging risks.
The UN says the dialogue is intended to ensure that AI governance reflects the priorities of all nations rather than only those with the greatest technological capabilities.
For developing countries such as Pakistan, this process provides an avenue to raise questions about technological access, capacity-building, data governance and participation in international rule-making.
AI and Military Decision-Making Raise Particular Concerns
One of the most sensitive areas in the AI debate is military decision-making.
AI can process enormous volumes of information far faster than humans. That capability could potentially assist military planners and governments, but it also raises questions about what happens when decisions involving force are increasingly influenced by automated systems.
A shorter decision-making cycle can create pressure to respond before human officials have fully evaluated the available information.
That is why Pakistan’s emphasis on restraint and confidence-building is significant in the context of international security.
The broader UN position has also stressed the importance of retaining meaningful human control over decisions involving the use of force.
The central issue is not simply whether AI should be used in security applications, but how governments can establish accountability when AI-assisted systems contribute to consequential decisions.
Disinformation Adds Another Layer of Risk
AI-generated content presents another challenge for governments and international organizations.
Generative AI can make it easier to create convincing text, images, audio and video at scale. In a conflict environment, such capabilities could complicate efforts to distinguish authentic information from manipulated material.
The UN has identified misinformation and disinformation among the major concerns surrounding artificial intelligence, particularly where manipulated content can affect public trust, human rights or humanitarian operations.
For international institutions, the problem is therefore both technological and political: governments must develop mechanisms capable of addressing harmful AI-generated content without undermining legitimate expression or access to information.
Global AI Governance Is Becoming More Urgent
The current Security Council discussion reflects a larger international shift.
AI governance is no longer being discussed solely in terms of innovation, investment and economic competitiveness. Governments are increasingly considering questions involving national security, international stability, human rights, development and inequality.
The United States and China, for example, continue to compete technologically while also discussing mechanisms for AI safety and communication.
Meanwhile, the UN is developing a more inclusive multilateral framework intended to give countries a role in shaping international AI governance.
That creates an important distinction between AI development and AI governance.
The first concerns how quickly capabilities advance. The second concerns the rules, safeguards and institutions that determine how those capabilities are developed and deployed.
What Pakistan’s Position Means for Developing Countries
Pakistan’s intervention highlights an issue that is likely to remain central to future AI negotiations: who gets to shape the rules governing artificial intelligence?
Developing countries have an interest not only in managing AI-related risks but also in ensuring access to the technology’s potential benefits.
The UN’s Global Digital Compact recognizes the need for capacity-building, technology cooperation and support for developing countries to access, develop, use and govern AI systems.
That approach is particularly relevant as AI becomes increasingly connected to education, healthcare, agriculture, financial services, public administration and economic productivity.
Without adequate access to computing infrastructure, skills, data and investment, developing countries could find themselves primarily consuming technologies designed elsewhere.
Pakistan’s call for representative and inclusive AI governance therefore places technological development and international security within the same broader conversation.
The Challenge Ahead: Rules That Keep Pace With Technology
The Security Council’s latest discussion illustrates the central difficulty confronting policymakers.
Artificial intelligence is developing faster than many traditional regulatory processes can respond.
International rules must address security risks without unnecessarily blocking beneficial innovation. They must also account for differences between developed and developing countries while maintaining fundamental principles such as human rights, transparency and accountability.
The United Nations’ emerging governance architecture is an attempt to address that challenge through scientific assessment, international dialogue and greater participation by countries around the world.
Pakistan’s intervention adds another voice to that debate, particularly on the consequences of unequal access to AI capabilities and the risks associated with AI-assisted military decision-making.
Conclusion
Pakistan’s warning at the UN Security Council underscores the increasingly international character of the artificial intelligence debate.
The issue is no longer simply how quickly AI can advance. It is also about how the technology is governed, who participates in setting the rules, how military risks are controlled and whether the benefits of AI are distributed broadly enough to avoid deepening existing inequalities.
As AI becomes more deeply integrated into security, economies and public institutions, international cooperation will become an increasingly important part of managing both its opportunities and its risks.
For Pakistan and other developing countries, the emerging global AI governance system will be particularly important because the rules established today could influence access to technology, economic opportunities and participation in future international decision-making for years to come.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
The dominant narrative around artificial intelligence investment has always centred on equity valuations — Nvidia’s market capitalisation, hyperscaler earnings multiples, the concentration of the S&P 500 in a handful of AI-exposed names. That narrative is now incomplete. The more consequential shift underway in 2026 is happening in credit markets, and regulators are starting to say so explicitly.
An Unprecedented Pace of Capital Deployment
The Bank of England’s July 2026 Financial Stability Report puts it plainly: the pace of AI-related investment is unprecedented historically, with AI companies increasingly turning to the financial system — and specifically to debt financing — to fund infrastructure buildouts. This marks a meaningful departure from the equity-heavy funding model that characterised the first wave of the AI boom, when cash-rich technology giants largely self-funded expansion from balance-sheet reserves.
Why Debt, and Why Now
The shift toward debt financing reflects simple scale economics: data-center construction costs have grown large enough that even the best-capitalised technology companies are choosing to preserve equity and cash flexibility by tapping bond and private credit markets instead. This dynamic accelerated sharply through the first half of 2026, coinciding with the same window in which China’s export data showed chips, computer parts and power equipment accounting for roughly half of the country’s export growth — evidence that the AI infrastructure buildout is now a genuinely global capital-expenditure cycle, not a US-only phenomenon.
The Leverage Concentration Problem
The Bank’s Financial Policy Committee has flagged a specific structural fragility: equity gains in AI-related names have been driven in significant part by a narrow, concentrated set of companies, with a substantial increase in the use of leverage tied to these positions. That combination — narrow concentration plus rising leverage — is precisely the mechanism that has historically turned isolated valuation corrections into broader, self-reinforcing liquidity events.
Separately, the Bank’s broader assessment of credit markets warns that vulnerabilities in risky asset valuations, sovereign debt markets and risky credit segments — including private credit specifically — remain, with some having become more pronounced since its previous report, as globally higher interest rates and energy-driven cost increases add pressure on corporate borrowers across the board, AI-related or otherwise.
The Sovereign Debt Connection
Perhaps the most significant — and least discussed — finding from the Bank’s analysis concerns how an AI-related equity correction could interact with sovereign bond markets. In its modelled scenario, debt-to-GDP ratios rise following a hypothetical AI valuation correction, but the Bank notes that both the US Treasury market and UK gilt market continued to function well under the scenario tested — with an explicit warning that had those markets come under pressure instead, the consequences could have been considerably more severe.
That finding sits uncomfortably alongside the Federal Reserve’s own hawkish pivot under Chair Kevin Warsh, detailed elsewhere in this series. A Fed moving toward rate hikes rather than cuts directly raises the cost of the debt financing now underpinning much of the AI infrastructure buildout — a tightening that could pressure highly leveraged data-center financing structures at precisely the moment the sector’s borrowing needs are accelerating.
What Regulators Are Doing About It
Rather than attempting to directly restrain AI-related credit growth — not typically a central bank mandate — the Bank of England is focused on strengthening the plumbing that would need to absorb a shock if one occurs. It points specifically to reforms already announced for money market funds across the UK and Europe, alongside exploratory changes to bolster resilience in the gilt repo market, as the primary tools available to prevent an AI-financing-driven credit event from cascading into broader market dysfunction.
The Investor Takeaway
For fixed-income investors and credit allocators, the practical shift is this: AI exposure can no longer be assessed purely through equity valuation multiples. The debt structures financing data-center buildouts — their leverage ratios, their sensitivity to a hawkish Fed, and their concentration among a narrow set of borrowers — now represent a distinct and growing risk factor in global credit markets, one that central banks on both sides of the Atlantic are actively modelling, even as they stop short of calling it a bubble outright.
Featured Snippet
Is AI infrastructure being funded by debt or equity in 2026? AI companies are increasingly relying on debt financing rather than equity to fund data-center buildouts, a shift the Bank of England describes as historically unprecedented in pace, raising new financial stability questions around leverage concentration and credit market resilience.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Tesla, SpaceX and Starlink: The Real Business Story Behind Elon Musk’s October Buzz

Resilience Under Strain: The World’s Difficult 2026 Choices

Andy Harris in 2026: Freedom Caucus Influence, Spending and Congressional Power

MLB Playoffs 2026: Postseason Format, Broadcast Guide and How to Track the Bracket

Elon Musk Calls Mukesh Ambani the “Real Boss of India” Over Alleged Monopoly Concerns

Legal Pioneer and Defender of Justice: The Life, Works, and Legacy of Navi Pillay

Inside the Modern Republican Party Platform: Tax Policy, Immigration, and Governance

Anne Carson: Genius of Hybrid Forms and 2026 Nobel Laureate in Literature

Analyzing the Republican Voter Enthusiasm Gap: Turnout Metrics and Polling Data

Min Ah: The Global Impact and Rising Popularity of the K-Drama Star
Analyzing the Republican Voter Enthusiasm Gap: Turnout Metrics and Polling Data
Inside the Modern Republican Party Platform: Tax Policy, Immigration, and Governance
Anne Carson: Genius of Hybrid Forms and 2026 Nobel Laureate in Literature
Resilience Under Strain: The World’s Difficult 2026 Choices

Remembering Kianna Underwood: The Nickelodeon Actress Behind “All That” and “Little Bill”
Elon Musk Calls Mukesh Ambani the “Real Boss of India” Over Alleged Monopoly Concerns

The West Wing Legacy: Why the Political Drama Is More Relevant Than Ever
MLB Playoffs 2026: Postseason Format, Broadcast Guide and How to Track the Bracket
-

 Featured6 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-

 Democracy5 years ago
Missing You! SPSC
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day