Analysis
2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover

With the November 3, 2026 midterm elections roughly two months away, multiple independent forecasting models are converging on a similar conclusion: Democrats are currently favored to retake control of the U.S. House of Representatives, though the size of any majority — and control of the Senate — remains genuinely uncertain.
This piece breaks down what the leading models actually say, why historical patterns favor the out-of-power party in midterms, and which structural factors could still complicate a Democratic pickup.
Table of Contents
The Current Numbers
Heading into the cycle, Republicans hold a narrow 218-seat majority, with Democrats at 212 seats and several vacancies. Because of that narrow margin, Democrats need to flip only a small net number of seats — commonly cited as roughly three to six, depending on how upcoming special elections in safely Democratic vacant seats resolve — to reclaim the majority.
Several independent models have published 2026 House projections:
- A Cornell University-based academic forecasting team, presenting at the American Political Science Association’s annual meeting, projects Democrats winning approximately 226 seats to Republicans’ 209, with simulations showing a plausible range as wide as 206 to 258 Democratic seats.
- A separate independent forecasting outlet (FiftyPlusOne) gives Democrats an 85% probability of winning the House majority, with a median projected outcome of 230 seats, and a national House popular-vote margin estimated at roughly +7 points for Democrats.
- Aggregator and prediction-market platforms tracking the race show a broadly consistent picture: Democrats favored, with meaningful — not negligible — uncertainty remaining.
Researchers behind the Cornell model were notably direct about what it would take for the forecast to be wrong: given the model’s historical accuracy, a Republican House majority holding would likely mean “either everything has gone their way or something unprecedented has happened.”
Why History Favors Democrats Structurally
Election forecasters lean heavily on one of the most consistent patterns in American politics: the president’s party almost always loses House seats in midterm elections.
- Looking back across 36 midterm elections since 1882, the White House party avoided losing a net of at least three seats in only four of them — 1934, 1962, 1998, and 2002 — each occurring under unusual circumstances (the Great Depression recovery, the Cuban Missile Crisis aftermath, post-9/11 unity, and the Clinton impeachment backlash, respectively).
- Democrats need a uniform national swing of roughly 1.1% from the 2024 House results to flip control — a relatively low bar by historical standards.
- Special elections held throughout 2025 provide an early, concrete signal: across roughly 31 state legislative and House special elections, Democratic candidates outperformed the 2024 presidential ticket’s vote share by an average of 15.4 points (median 13 points) — more than ten times the swing needed to flip the House.
The Redistricting Wildcard
No 2026 forecast is complete without accounting for the unusual mid-decade redistricting activity that has reshaped the House map since the 2024 election. Aggressive redistricting in several Republican-controlled states has given the GOP additional structural insulation heading into this cycle — a countervailing force against the historical midterm pattern and the favorable special-election trendline described above. This is the central tension every current model is trying to price in: strong Democratic generic political environment signals, against a map that has been deliberately reshaped to blunt exactly that kind of environment.
The GOP Counter-Strategy
Republican strategists are not treating the historical pattern as inevitable. Key elements of the party’s defensive posture include:
- Leaning on redistricting gains in states where new maps have already been implemented, effectively “banking” seats that would otherwise be more competitive under prior district lines.
- Fundraising and turnout operations targeted specifically at the small number of genuinely competitive districts where the national environment is expected to matter most.
- Nationalizing the midterm around specific policy contrasts rather than running on incumbency alone, given that broad “stay the course” messaging tends to perform poorly for an incumbent president’s party in a midterm.
What Swing Districts Are Actually Deciding This
Rather than the national popular vote, the real decision point sits in a relatively small number of competitive districts — often those that saw redistricting changes, those with retiring incumbents, or historically split-ticket suburban seats. Readers tracking this race closely should watch:
- Districts with open seats created by incumbent retirements, which historically see larger swings than seats with incumbents running for reelection.
- Suburban districts that have trended away from the GOP in recent cycles, where the current generic-ballot environment would need to hold through November to matter.
- Newly redrawn districts in states where redistricting fights are still working through courts — some maps used in 2026 could still face late legal challenges.
What Competitors Are Missing
Much of the horserace coverage of this cycle reports the topline “Democrats favored” number without explaining why two structurally different forces — a strongly Democratic-leaning political environment on one hand, and an aggressively re-drawn map on the other — are pulling against each other simultaneously. That tension, not the headline probability number, is the actual story of the 2026 House cycle, and it’s why even a “85% favored” forecast still carries real uncertainty worth taking seriously rather than treating as a foregone conclusion.
Key Dates to Watch
- Ongoing — ballot access deadlines and any late redistricting litigation in contested states
- September–October 2026 — final pre-election generic ballot and fundraising disclosures
- November 3, 2026 — Election Day
- Early November 2026 — initial results; close districts may take days to certify
Q: Are Democrats favored to win the House in the 2026 midterms?
As of early September 2026, multiple independent forecasting models favor Democrats to win a U.S. House majority. One academic model projects roughly 226 Democratic seats to 209 Republican seats; another independent forecaster puts Democrats’ probability of winning the House at 85%, with a median projection of 230 seats. Republicans currently hold an 218-seat majority, and Democrats need only a small net seat gain to flip control.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


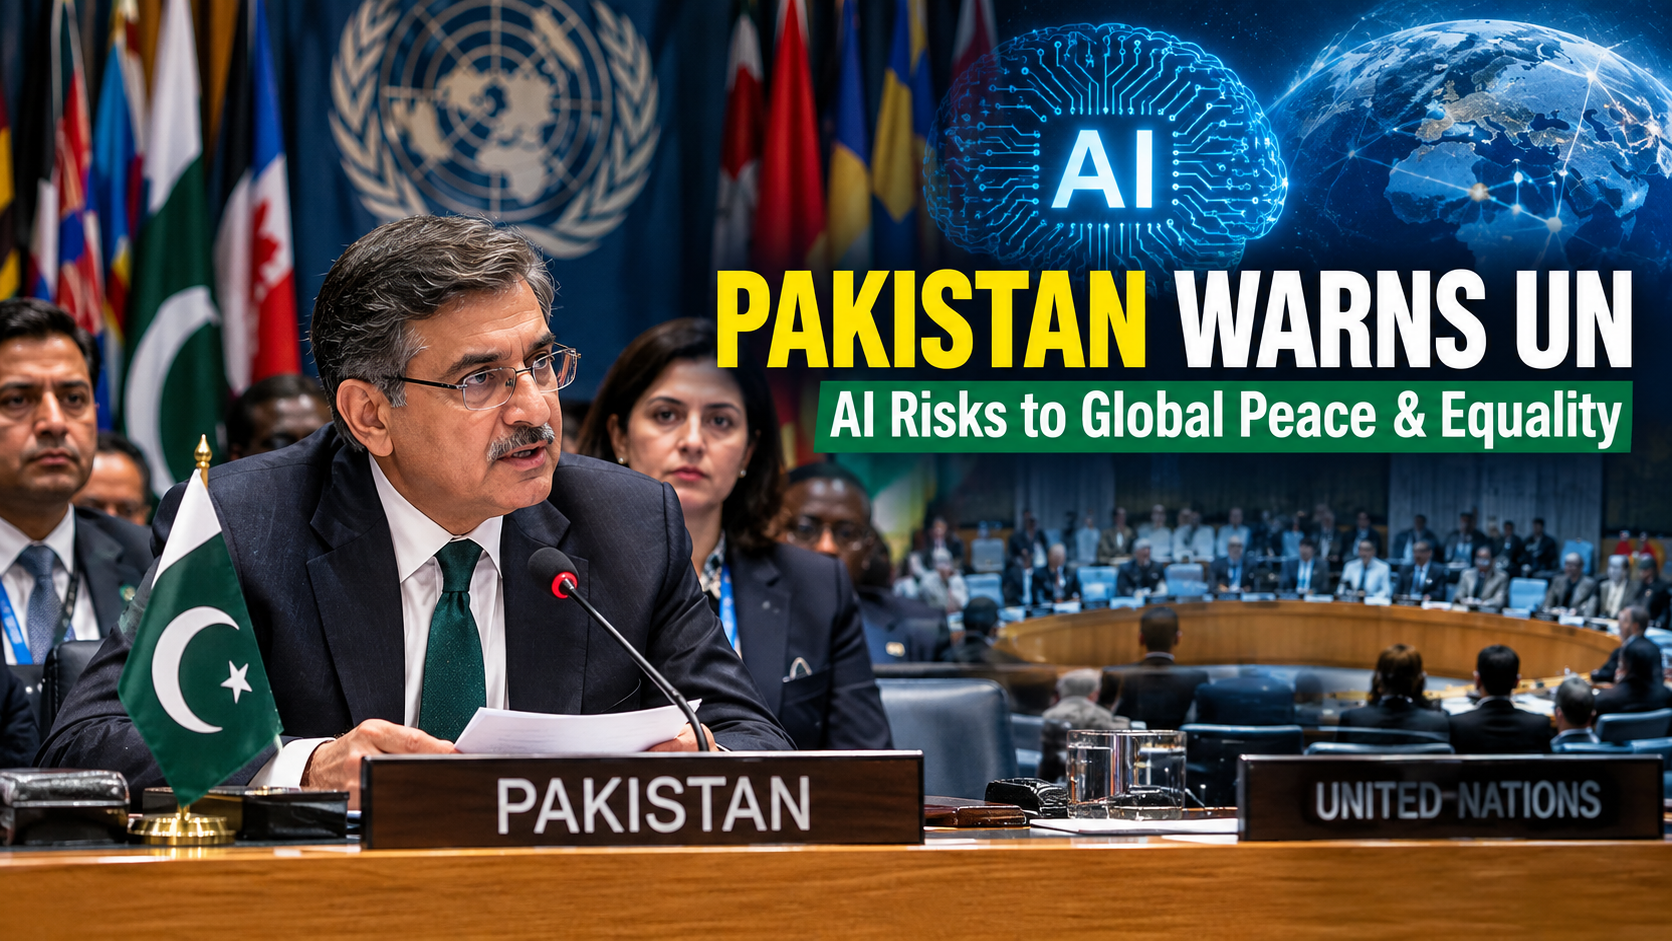
UNITED NATIONS — September 24, 2026: Pakistan has warned the United Nations Security Council that the rapid and insufficiently regulated development of artificial intelligence could deepen global inequality while creating new risks to international peace and security.
Speaking during a Security Council briefing on “Artificial Intelligence and International Security,” Pakistan’s Deputy Prime Minister and Foreign Minister Senator Mohammad Ishaq Dar called for stronger international safeguards, regulatory frameworks and governance mechanisms to address the risks associated with increasingly powerful AI systems.
Dar emphasized that the international community needs coordinated action to establish guardrails around artificial intelligence, particularly as AI technologies become increasingly relevant to military decision-making, information systems and national security.
Pakistan Calls for International Guardrails on Artificial Intelligence
Pakistan’s intervention comes as governments and international institutions increasingly debate how AI should be governed across borders.
Dar stressed the importance of restraint and confidence-building measures in the military domain, particularly because AI-assisted systems could compress decision-making timelines and increase the danger of miscalculation.
The concern is significant because artificial intelligence is no longer confined to civilian applications. AI is increasingly being examined in relation to cyber operations, intelligence analysis, autonomous systems, information warfare and other security-sensitive areas.
The United Nations has also warned that AI can create substantial risks when technological development moves faster than international governance.
The UN’s existing AI framework emphasizes responsible, accountable, transparent and human-centered development, while calling for effective human oversight of AI systems.
Why AI Is Becoming a Security Council Issue
The Security Council has previously considered artificial intelligence as a potential factor affecting international peace and security, but the technology has developed rapidly since those early discussions.
A recent analysis by the independent Security Council Report identified several security implications, including AI’s ability to facilitate malicious cyber activity, accelerate the creation and distribution of misinformation and disinformation, and influence military operations.
The organization also highlighted concerns surrounding increasingly autonomous weapons systems, shortened decision-making timelines and questions about human oversight and accountability.
These concerns help explain why AI has moved beyond being primarily a technology-policy issue and increasingly become a subject of international security diplomacy.
The challenge for governments is that AI can simultaneously create opportunities and risks.
AI could help countries identify emerging conflicts, improve humanitarian operations, monitor ceasefires and analyze large quantities of information. At the same time, poorly governed systems could amplify security threats or make already complex conflicts more difficult to manage.
Pakistan Highlights the Global Inequality Dimension
Pakistan’s message to the Security Council went beyond military applications.
Dar also emphasized the need for AI development to be representative, transparent and inclusive, reflecting concerns among developing countries that the benefits of advanced artificial intelligence could become concentrated among a relatively small group of technologically advanced states and companies.
That concern is already reflected in the United Nations’ Global Digital Compact.
The Compact calls for closing digital divides, expanding access to the benefits of the digital economy and strengthening international governance of artificial intelligence. It specifically calls for full and equal representation of countries, including developing nations, in international AI governance.
This makes AI access and governance part of a broader development question.
Countries with advanced computing infrastructure, large datasets, sophisticated research institutions and substantial private-sector investment are positioned differently from nations that remain dependent on imported technologies and have limited domestic AI capacity.
If that gap widens, AI could potentially reinforce existing economic and technological inequalities rather than reduce them.
UN Framework Already Calls for Inclusive AI Governance
The debate at the Security Council is taking place alongside a broader UN effort to develop international mechanisms for AI governance.
The Global Digital Compact, adopted as part of the Pact for the Future, established a framework for international cooperation on digital technologies and AI.
The United Nations has subsequently established an Independent International Scientific Panel on Artificial Intelligence and a Global Dialogue on AI Governance.
The first annual Global Dialogue took place in Geneva in July 2026, bringing together governments and other stakeholders to discuss international cooperation, AI opportunities and emerging risks.
The UN says the dialogue is intended to ensure that AI governance reflects the priorities of all nations rather than only those with the greatest technological capabilities.
For developing countries such as Pakistan, this process provides an avenue to raise questions about technological access, capacity-building, data governance and participation in international rule-making.
AI and Military Decision-Making Raise Particular Concerns
One of the most sensitive areas in the AI debate is military decision-making.
AI can process enormous volumes of information far faster than humans. That capability could potentially assist military planners and governments, but it also raises questions about what happens when decisions involving force are increasingly influenced by automated systems.
A shorter decision-making cycle can create pressure to respond before human officials have fully evaluated the available information.
That is why Pakistan’s emphasis on restraint and confidence-building is significant in the context of international security.
The broader UN position has also stressed the importance of retaining meaningful human control over decisions involving the use of force.
The central issue is not simply whether AI should be used in security applications, but how governments can establish accountability when AI-assisted systems contribute to consequential decisions.
Disinformation Adds Another Layer of Risk
AI-generated content presents another challenge for governments and international organizations.
Generative AI can make it easier to create convincing text, images, audio and video at scale. In a conflict environment, such capabilities could complicate efforts to distinguish authentic information from manipulated material.
The UN has identified misinformation and disinformation among the major concerns surrounding artificial intelligence, particularly where manipulated content can affect public trust, human rights or humanitarian operations.
For international institutions, the problem is therefore both technological and political: governments must develop mechanisms capable of addressing harmful AI-generated content without undermining legitimate expression or access to information.
Global AI Governance Is Becoming More Urgent
The current Security Council discussion reflects a larger international shift.
AI governance is no longer being discussed solely in terms of innovation, investment and economic competitiveness. Governments are increasingly considering questions involving national security, international stability, human rights, development and inequality.
The United States and China, for example, continue to compete technologically while also discussing mechanisms for AI safety and communication.
Meanwhile, the UN is developing a more inclusive multilateral framework intended to give countries a role in shaping international AI governance.
That creates an important distinction between AI development and AI governance.
The first concerns how quickly capabilities advance. The second concerns the rules, safeguards and institutions that determine how those capabilities are developed and deployed.
What Pakistan’s Position Means for Developing Countries
Pakistan’s intervention highlights an issue that is likely to remain central to future AI negotiations: who gets to shape the rules governing artificial intelligence?
Developing countries have an interest not only in managing AI-related risks but also in ensuring access to the technology’s potential benefits.
The UN’s Global Digital Compact recognizes the need for capacity-building, technology cooperation and support for developing countries to access, develop, use and govern AI systems.
That approach is particularly relevant as AI becomes increasingly connected to education, healthcare, agriculture, financial services, public administration and economic productivity.
Without adequate access to computing infrastructure, skills, data and investment, developing countries could find themselves primarily consuming technologies designed elsewhere.
Pakistan’s call for representative and inclusive AI governance therefore places technological development and international security within the same broader conversation.
The Challenge Ahead: Rules That Keep Pace With Technology
The Security Council’s latest discussion illustrates the central difficulty confronting policymakers.
Artificial intelligence is developing faster than many traditional regulatory processes can respond.
International rules must address security risks without unnecessarily blocking beneficial innovation. They must also account for differences between developed and developing countries while maintaining fundamental principles such as human rights, transparency and accountability.
The United Nations’ emerging governance architecture is an attempt to address that challenge through scientific assessment, international dialogue and greater participation by countries around the world.
Pakistan’s intervention adds another voice to that debate, particularly on the consequences of unequal access to AI capabilities and the risks associated with AI-assisted military decision-making.
Conclusion
Pakistan’s warning at the UN Security Council underscores the increasingly international character of the artificial intelligence debate.
The issue is no longer simply how quickly AI can advance. It is also about how the technology is governed, who participates in setting the rules, how military risks are controlled and whether the benefits of AI are distributed broadly enough to avoid deepening existing inequalities.
As AI becomes more deeply integrated into security, economies and public institutions, international cooperation will become an increasingly important part of managing both its opportunities and its risks.
For Pakistan and other developing countries, the emerging global AI governance system will be particularly important because the rules established today could influence access to technology, economic opportunities and participation in future international decision-making for years to come.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
Most celebrity business ventures are licensing deals wearing a founder’s costume. The name goes on the label, the cheque clears, and an operating company nobody has heard of does the actual work.
Jennifer Garner’s is not that. On 6 February 2026, she rang the opening bell at the New York Stock Exchange as Once Upon A Farm went public at $18 per share with a valuation of $724 million.
The company she co-founded is now a listed public entity with audited financials, a board seat in her name, and a stock price that has since gone down. That last detail is the most interesting part of the story.
Key Takeaways
- The IPO: Once Upon A Farm listed on the NYSE as OFRM, raising $197.9 million at the midpoint of its marketed range.
- The pop: shares closed day one up about 17%, then traded at $25.10 by 9 February — nearly 40% above the listing price.
- The reality check: the stock was down about 15% for the year by August 2026.
- The business is real: $225 million in annual revenue for the year ending September 2025, up more than 40%.
- Her role is contractual and disclosed: board director, co-founder and spokesperson, with compensation set out in the S-1.
What Once Upon A Farm Actually Is
The company sells organic, cold-pressed refrigerated food for children — pouches, smoothies, applesauce and oat bars — through grocery retail and direct-to-consumer channels.
It was founded by serial entrepreneurs Cassandra Curtis and Ari Raz, with Garner and CEO John Foraker joining as co-founders two years later. Foraker’s background matters to the credibility of the operation: he ran Annie’s Homegrown for more than a decade and served as a president at General Mills.
Note: founding-date reporting varies between 2011 and 2015 depending on the source. Verify before publication.
The Financial Trajectory
| Metric | Figure |
|---|---|
| Annual revenue (yr ending Sept 2025) | $225 million |
| Year-on-year growth | Over 40% |
| CAGR since 2018 | More than 60% |
| IPO valuation | $724 million |
| Capital raised | $197.9 million |
| Shares sold by company | ~7.6 million |
| Shares sold by existing holders | ~3.4 million |
| Lead bookrunners | Goldman Sachs, JPMorgan Chase |
A compound annual growth rate above 60% sustained over seven years is not a celebrity endorsement outcome. It is a consumer packaged goods outcome — and CPG is one of the hardest categories in which to build distribution from scratch.
What Her Actual Job Is
This is where the Once Upon A Farm story diverges most sharply from the celebrity-brand template, because the terms are public.
The S-1 discloses that Garner serves on the public company’s board of directors and continues as co-founder and spokesperson — “Farmer Jen” — a role for which she was paid $1 million in the prior year, with $2 million to $3 million in expected annual compensation through 2028, separate from stock options and an IPO-linked bonus.
She also worked the roadshow directly. Garner described the investor meetings to Forbes as rooms full of existing customers, noting that families already trusted the product.
That is a meaningful distinction for anyone assessing celebrity-backed companies. There is a difference between a founder who licenses a likeness and a founder who sits on the board, pitches institutional investors and has compensation disclosed in a registration statement.
The Mission Structure
Once Upon A Farm is a public benefit corporation — the “PBC” in its legal name — which means its charter permits management to weigh mission alongside shareholder returns.
Garner has framed the IPO itself as a mission decision. Selling to a major food conglomerate would have cost the existing team control of the business; a listing preserved it while raising capital.
The concrete expression of that mission is WIC certification. Getting products approved so low-income families can purchase them through the federal nutrition programme has been a stated priority, and the brand now holds that distinction in more than 20 states. Garner has called it the company’s north star.
It connects to a longer track record — she had been a trustee for Save the Children for several years before joining the company in 2017.
The Risks the Prospectus Discloses
A public listing forces disclosure that private celebrity ventures never face. Three risks stand out.
Tariff and sourcing exposure. The prospectus highlighted risks related to tariffs and trade barriers, particularly against Mexico and South America, from where the company sources a significant portion of its fruit and vegetable ingredients.
Key-person concentration. A brand built substantially on one founder’s public identity carries a risk no diversified CPG company does.
Acquisition framing. Ahead of the listing, Hedgeye analyst Bennett Cheer characterised the company as an acquisition “play” — a view that treats the IPO as a staging post toward a strategic sale rather than a destination.
The Post-IPO Slide, and What It Tells You
The stock’s path is the honest part of this story. Priced at $18, up 17% on day one, close to $25 within a week, then down roughly 15% for the year by August.
Garner’s stated response has been to ignore the daily price and focus on execution — her position being that the stock follows the mission rather than the reverse.
Whether or not one finds that convincing as investor communication, the underlying pattern is common and worth understanding. Consumer IPOs frequently pop on scarcity — the listing was described as a rare food offering that excited investors — and then reprice once the float settles and quarterly results replace the narrative.
For investors, the lesson generalises. A founder’s celebrity generates demand at listing. It does not generate gross margin.
The Broader Commercial Portfolio
Beyond Once Upon A Farm, Garner’s commercial activity follows a consistent pattern: long-term brand relationships rather than one-off endorsements.
She has been the recurring face of Capital One’s advertising campaigns, continuing through 2026. She brokered Once Upon A Farm’s first sports sponsorship in 2024 — a multi-year deal making it Angel City FC’s exclusive children’s snack partner.
She was named to the Forbes 50 Over 50 class of 2026 at age 54, alongside continued acting work.
What This Means for the Global Market in 2027
Coverage of celebrity businesses stops at the launch. Here is what actually determines outcomes.
Public listing is the real test of a celebrity brand. Private valuations are negotiated; public ones are voted on daily. Expect more celebrity-founded consumer companies to attempt listings after this precedent — and expect most to trade below their debut.
Governance disclosure becomes the differentiator. Once Upon A Farm published its founder compensation structure. Investors evaluating the next celebrity IPO should ask for the same and treat its absence as a signal.
Tariff exposure is the underpriced risk in food CPG. Companies sourcing produce from Mexico and South America face input volatility that margin models built in a stable trade environment do not capture.
The PBC structure will be tested. A public benefit corporation’s mission commitments have not yet been stress-tested against a sustained share price decline. Once Upon A Farm may become the case study.
Acquisition remains the likely endgame. If the Hedgeye thesis holds, a strategic buyer eventually acquires the brand. The question for shareholders is whether that happens above or below the $18 listing price.
Frequently Asked Questions
What company did Jennifer Garner found?
Garner is a co-founder and chief brand officer of Once Upon A Farm, an organic children’s food company. She joined in September 2017 alongside CEO John Foraker; the business was originally founded by Cassandra Curtis and Ari Raz.
When did Once Upon A Farm go public?
The company listed on the New York Stock Exchange under the ticker OFRM on 6 February 2026, pricing at $18 per share for a valuation of $724 million and raising $197.9 million.
How much revenue does Once Upon A Farm generate?
The company reported $225 million in annual revenue for the year ending September 2025, representing growth of more than 40% year-on-year and a compound annual growth rate above 60% since 2018.
Is Jennifer Garner paid by Once Upon A Farm?
Yes, and the terms are disclosed. She was paid $1 million in the year before the IPO, with $2 million to $3 million in expected annual compensation through 2028, separate from stock options and an IPO-linked bonus.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
Horror took 12.1% of US ticket sales in 2025, up from 9.8%. Inside the ROI gap between indie horror and studio blockbusters, and what 2026 changed.Horror is the only major genre currently increasing both its supply of films and its total grosses, while mid-budget production declines everywhere else. That single fact explains most of what is happening to theatrical distribution strategy.
Executive Summary / Key Takeaways
- Horror accounted for 12.1% of US domestic ticket sales in 2025, up from 9.8% in 2024, generating $843.88 million and 14.91% of total box office revenue through August 2025.
- Horror generated roughly $16 million per film in 2024 — about four times the drama average of $4 million and 33 times the documentary average.
- Indie economics are the extreme case: Terrifier 3 turned a $2 million budget into $51.6 million domestic, a 43.5x return, while Longlegs turned $10 million into $74.4 million.
- 2025 produced three $100 million-plus domestic horror titles — Sinners, Weapons and Final Destination Bloodlines — with Sinners delivering the largest horror domestic gross since It in 2017.
- 2026 sustained the run: Backrooms sits at $394.1 million worldwide on the all-time horror list, and studios now treat horror as a year-round release category rather than a seasonal one.
Through August 2025, horror films accounted for 14.91% of total box office revenue, generating $843.88 million, and the genre’s share of domestic ticket sales rose from 9.8% in 2024 to 12.1% in 2025, according to industry data compilations. In 2023 horror accounted for more than 10% of box office revenue, having doubled its share in a decade.
The efficiency figures are more striking than the share figures. Horror ranked fifth by gross in 2024 at $847 million but generated $16.0 million per film — four times the drama average and 33 times the documentary average — and produced 9.84% of domestic box office from just 7.8% of total releases, per the Screamwire Horror Industry Report.
2. Core Financial Analysis
2.1 The ROI ladder
| Film | Budget | Domestic / worldwide gross | Multiple | Category |
|---|---|---|---|---|
| Terrifier 3 | ~$2m | $51.6m domestic | 43.5x | Micro-budget indie |
| Longlegs | ~$10m | $74.4m domestic | ~7.4x | Indie / specialty |
| M3GAN | $10–20m | $126.9m | 6–12x | Studio genre (Blumhouse model) |
| Weapons | Mid-budget | $269.9m worldwide | — | Studio original, R-rated |
| Sinners | Mid-budget | $370.2m worldwide | — | Studio original, R-rated |
| Final Destination Bloodlines | Franchise | $317.8m worldwide | — | Franchise reboot |
| The Conjuring: Last Rites | Franchise | $499.1m worldwide | — | Established universe |
| Backrooms (2026) | A24 | $394.1m worldwide | — | IP adaptation |
Gross figures compiled from Wikipedia’s horror film records and the all-time list; budget and multiple data from the Screamwire report.
The distribution is bimodal, and that is the important structural point. Micro-budget indie horror delivers extraordinary multiples on small absolute returns. Franchise horror delivers large absolute returns on modest multiples. The squeezed middle — the $40–70 million genre film with no IP and no breakout hook — is where losses concentrate, which is the same squeeze killing mid-budget production across every other genre.
2.2 The 2025 originals
The most commercially significant development was the performance of original R-rated horror. Weapons became the second original R-rated film of the year to reach $100 million domestically after Sinners, at a time when the wider genre was under pressure, according to The Hollywood Reporter. Weapons reached the $100 million North American mark in its fourteenth day against nine days for Sinners, which opened to $48 million, and narrowly bested Jaws on an unadjusted basis to rank as the top-grossing R-rated horror film domestically — though its worldwide tally sat well behind Jaws globally.
Sinners‘ domestic gross of roughly $279.6 million was the largest for a horror film since It reached $328.8 million in 2017.
2.3 What 2026 looked like
The year front-loaded unusually. January and February accounted for the overwhelming majority of the genre’s Q1 revenue, buoyed by Scream 7, Send Help, Iron Lung and Primate, before March went quiet outside a few smaller titles, per IndieWire. The publication’s key observation: in 2026, studios are still treating horror as a year-round attraction rather than a seasonal afterthought.
By mid-year, horror had become one of the year’s dominant commercial stories, with Obsession — a Focus Features psychological thriller from Curry Barker — leading the genre and A24’s Backrooms adapting an internet creepypasta into a major release, according to trade roundups.
3. Structural Drivers and Competitor Gaps
Performance intensity is a budget line that pays. The commercial argument for immersive, physically demanding performances in genre film is not artistic — it is marketing efficiency. A transformation performance generates earned media, awards-adjacent coverage and word-of-mouth that a $40 million marketing spend would otherwise have to buy. Terrifier 3‘s 43.5x return did not come from advertising; it came from a performance and a reputation that travelled without it.
Horror is countercyclical in a specific way. Its economics do not depend on premium formats, international star recognition or family co-viewing — the three things a contracting theatrical market damages most. That is why horror supply is rising while mid-budget production falls generally.
Franchise universes compound. The Conjuring universe has grossed roughly $2.4 billion worldwide across eight films. Once an established universe exists, each subsequent entry carries lower marketing cost per dollar of gross, which is why studios pursue universe construction over one-off successes even when the one-offs have better multiples.
Streaming is a complement, not a substitute. Shudder set viewership records in 2024, doubling total hours, and horror’s October streaming share reached 15.8%. The genre appears to sustain both theatrical and at-home demand simultaneously, which is not true of most categories.
The gap in most coverage. Analysts consistently report horror’s revenue share without reporting its revenue efficiency. Share is a demand statistic; efficiency is an investment statistic. A genre producing 9.84% of domestic box office from 7.8% of releases is outperforming on a per-slot basis, and that ratio — not the headline share — is what should drive greenlight decisions.
4. Key Implications for Stakeholders
Entertainment investors. The barbell is the actionable structure: micro-budget indie horror for multiple, established franchise horror for absolute return, and nothing in between. The $40–70 million original genre film is the category to avoid.
Film industry observers. Watch whether 2026’s originals replicate 2025’s. The genre’s health currently rests on original R-rated titles performing at franchise levels, which is historically unusual and may not persist.
Distributors. The seasonal assumption is obsolete. January and February carried the majority of Q1 2026 horror revenue, and studios releasing horror year-round are capturing calendar slots that used to be conceded to family and awards product.
Producers. Casting for transformation is a defensible budget allocation in this genre specifically, because the performance itself functions as a marketing asset in a way it does not in most categories.
5. Frequently Asked Questions
Q1: How much of the box office is horror?
Horror accounted for 12.1% of US domestic ticket sales in 2025, up from 9.8% in 2024, and 14.91% of total box office revenue through August 2025 on $843.88 million of gross.
Q2: Is indie horror more profitable than studio horror?
On return multiple, yes. Terrifier 3 turned roughly $2 million into $51.6 million domestic — about 43.5x — while franchise titles like The Conjuring: Last Rites deliver far larger absolute grosses at lower multiples.
Q3: What was the highest-grossing horror film of 2025?
Among dedicated horror titles, The Conjuring: Last Rites led at $499.1 million worldwide, followed by Sinners at $370.2 million and Final Destination Bloodlines at $317.8 million.
Q4: Why are studios releasing horror year-round now?
Because the seasonal model left revenue on the table. In 2026, January and February produced the overwhelming majority of Q1 horror revenue, confirming that demand is not confined to autumn.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Pakistan Warns UN Security Council of AI Risks to Global Peace and Equality

Fortress Diplomacy: How China’s Secretive Hongqi N701 Matches America’s Legendary “Beast”

Jennifer Garner’s Latest Projects: Business Ventures Beyond Hollywood

Horror Box Office Economics: ROI, Market Share and the 2026

Inside Pete Hegseth’s Pentagon Speech Requirements: Structural Reforms and Defense Strategy

Remembering Eliana Moreno: The Legacy of NBC LA’s “Eli in the Heli”

Rep. Thomas Massie’s Impeachment Push Against Pete Hegseth, Explained

Bloodhound Q50: Remembering the Tragic Loss of Chicago’s Rising Drill Star

iOS 27 Release Date & Siri AI: The Ultimate Tech News Guide for iPhone 18 Users

Johnny Ray and Nicole Mississippi: Attala County Case Explained

Best iPhone 18 Pro Max Cases: Premium Protection for Apple’s 2026 Flagship

2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover

Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown
Bloodhound Q50: Remembering the Tragic Loss of Chicago’s Rising Drill Star
Remembering Eliana Moreno: The Legacy of NBC LA’s “Eli in the Heli”

2026 Midterms: How Democrats Are Competing in Deep-Red Senate Seats
Pakistan Warns UN Security Council of AI Risks to Global Peace and Equality

RFK Jr. Confirmation Investigation 2026: Health Policy Fallout Explained
-

 Featured5 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Democracy5 years ago
Missing You! SPSC
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills