Analysis
iOS 27 Release Date & Siri AI: The Ultimate Tech News Guide for iPhone 18 Users

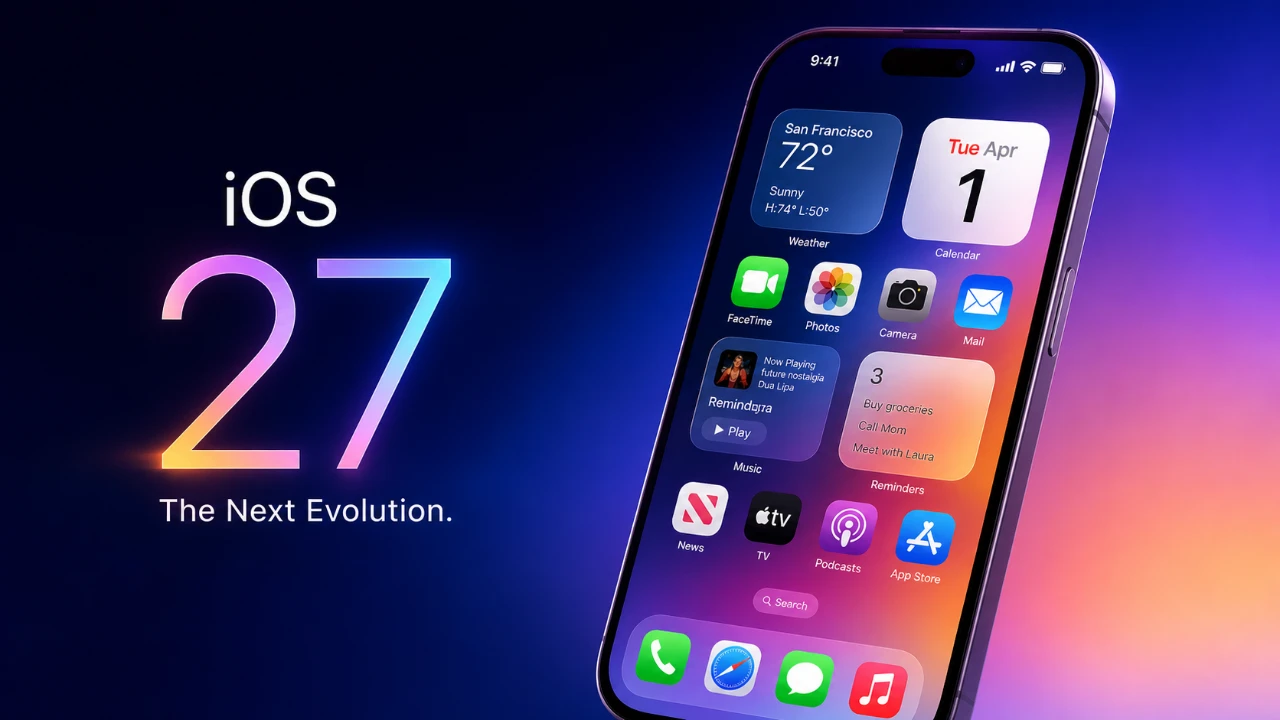
Table of Contents
Key Takeaways
- iOS 27 rolled out globally on Monday, September 14, 2026, alongside iPadOS 27, macOS 27, watchOS 27, tvOS 27, and visionOS 27.
- The headline feature is Siri AI, a rebuilt, app-based assistant built on Apple’s next-generation Foundation Models and developed with technical assistance from Google’s Gemini models.
- Full Siri AI functionality requires an iPhone 15 Pro/Pro Max or newer; owners of the standard iPhone 15 and older get iOS 27’s performance and design updates but not the AI assistant.
- At launch, Siri AI is English-only and is not yet available in the EU or China, pending regulatory clearance.
- Apple claims performance gains of up to 30% faster app launches, 70% faster Photos library loading, and 80% faster AirDrop transfers, even on older supported devices.
Apple’s fall software cycle has arrived, and this year the story isn’t just a new coat of visual paint — it’s the most significant rebuild of Siri in the assistant’s history. iOS 27 became available worldwide on September 14, 2026, roughly a week after the iPhone 18 Pro’s on-sale date, closing a beta cycle that began at WWDC on June 8. This guide breaks down what’s actually new, who gets the full experience, and how it stacks up against the broader wave of technology news shaping the AI assistant race in 2026.
What’s New in iOS 27
The centerpiece of iOS 27 is Siri AI, described by Apple as a ground-up rebuild rather than an incremental update. Unlike the old background-utility Siri, Siri AI runs as its own dedicated app, reachable both directly and by pulling down from the Dynamic Island. It’s powered by Apple’s next-generation Apple Foundation Models, which run partly on-device and partly in the cloud via Apple’s Private Cloud Compute infrastructure — Apple’s answer to the privacy concerns that dog cloud-based AI assistants generally.
Notably, reporting from 9to5Mac confirms Apple developed Siri AI with technical assistance from Google’s Gemini models — a striking admission for a company that has historically built its AI stack in-house, and a sign of how competitive the assistant landscape has become.
Beyond Siri, iOS 27 ships with more than 250 changes system-wide, according to coverage compiled from Apple’s own newsroom materials and outlets like MacRumors. Key additions include:
- Photos: A new Spatial Reframing tool for adjusting composition and perspective after a photo is taken, plus extended editing capabilities.
- Liquid Glass contrast controls: Refinements to the visual design language introduced in prior iOS versions.
- Expanded parental controls and child-safety tools.
- Performance overhaul: Apple says even an iPhone 11 Pro, first launched in 2019, will see meaningfully faster app-opening times after updating.
Siri AI Capabilities
Apple describes Siri AI as offering personal-context understanding, onscreen awareness, broader world knowledge, typed conversations, persistent conversation history, and cross-app actions. In developer-beta demonstrations, Siri AI pulled a tracking number from an email to create a reminder automatically, and organized receipt text into structured notes — the kind of multi-step, context-aware task that competing assistants have offered for longer, and that has been a recurring criticism of Apple’s AI strategy since Apple Intelligence first debuted in 2024.
Which iPhones Get the Full Experience?
This is the detail causing the most confusion among users, so it’s worth being precise:
| Device Tier | Gets iOS 27? | Gets Siri AI / Apple Intelligence? |
|---|---|---|
| iPhone 11 through iPhone 14 series, iPhone SE (2nd gen)+ | Yes | No — performance and design updates only |
| iPhone 15 / 15 Plus (standard) | Yes | No |
| iPhone 15 Pro / 15 Pro Max | Yes | Yes |
| iPhone 16 series and newer | Yes | Yes |
| iPhone 18 Pro (A20 Pro chip) | Yes | Yes — fullest experience, including custom Siri voices |
Advanced capabilities like custom Siri voices are further restricted to iPhone 17 Pro and newer, iPhone Air, and iPhone Duo — meaning even some Apple Intelligence-eligible devices won’t get every feature at launch. In the Home app, camera features powered by Apple Intelligence require an iCloud+ plan of at least 2TB, and AI image-generation features carry daily usage limits for non-paying iCloud users.
Regional and Language Rollout
Siri AI launches in English only, with Apple stating additional languages will arrive later in 2026 without committing to specific dates. More significantly, Siri AI is not available at launch in the European Union or in China, where Apple is still navigating regulatory requirements — the EU’s Digital Markets Act and China’s data-localization and AI-content rules being the most likely sticking points, based on the pattern of prior Apple Intelligence rollouts.
How iOS 27 Fits the Broader AI Assistant Race
This release lands amid an intensifying cycle of technology news around AI assistants generally, with Google, Amazon, and Microsoft all pushing more agentic, cross-app capable assistants through 2026. Apple’s decision to lean on Gemini for parts of Siri AI’s technical foundation — while still branding and gating the experience through its own hardware and privacy infrastructure — reflects a pragmatic, if unusual, strategic pivot for a company that has typically emphasized vertical integration.
For context on adoption speed: by June 2026, roughly 86% of iPhones sold within the previous four years were already running iOS 26, with 79% of the total active iPhone base on that version — a high baseline that gives Apple a strong distribution runway for iOS 27’s rollout.
Why This Matters for iPhone 18 Users Specifically
Buyers of the new iPhone 18 Pro, which launched roughly a week before iOS 27’s public release, get the fullest version of the experience out of the box: the A20 Pro chip, custom Siri voices, and full Apple Intelligence integration without needing to wait for eligibility thresholds that limit older hardware. For anyone weighing whether to upgrade purely for software reasons, the practical dividing line is the iPhone 15 Pro — anything below that tier gets iOS 27’s speed and design improvements, but not the AI assistant that’s driving this release’s headlines.
Frequently Asked Questions
What iPhones are compatible with iOS 27?
iOS 27 supports the iPhone 11 and later, plus the iPhone SE (2nd generation) and later — the same device range as iOS 26. However, Siri AI and Apple Intelligence features require an iPhone 15 Pro/Pro Max or newer.
Is Siri AI available in all languages and countries at launch?
No. Siri AI launches in English only and is not available at launch on iPhone or iPad in the European Union or in China, pending regulatory clearance.
Does iOS 27 slow down older iPhones?
Apple claims the opposite — the company says iOS 27 was built around a performance overhaul, with app launches up to 30% faster and AirDrop transfers up to 80% faster, even on older supported devices like the iPhone 11 Pro.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


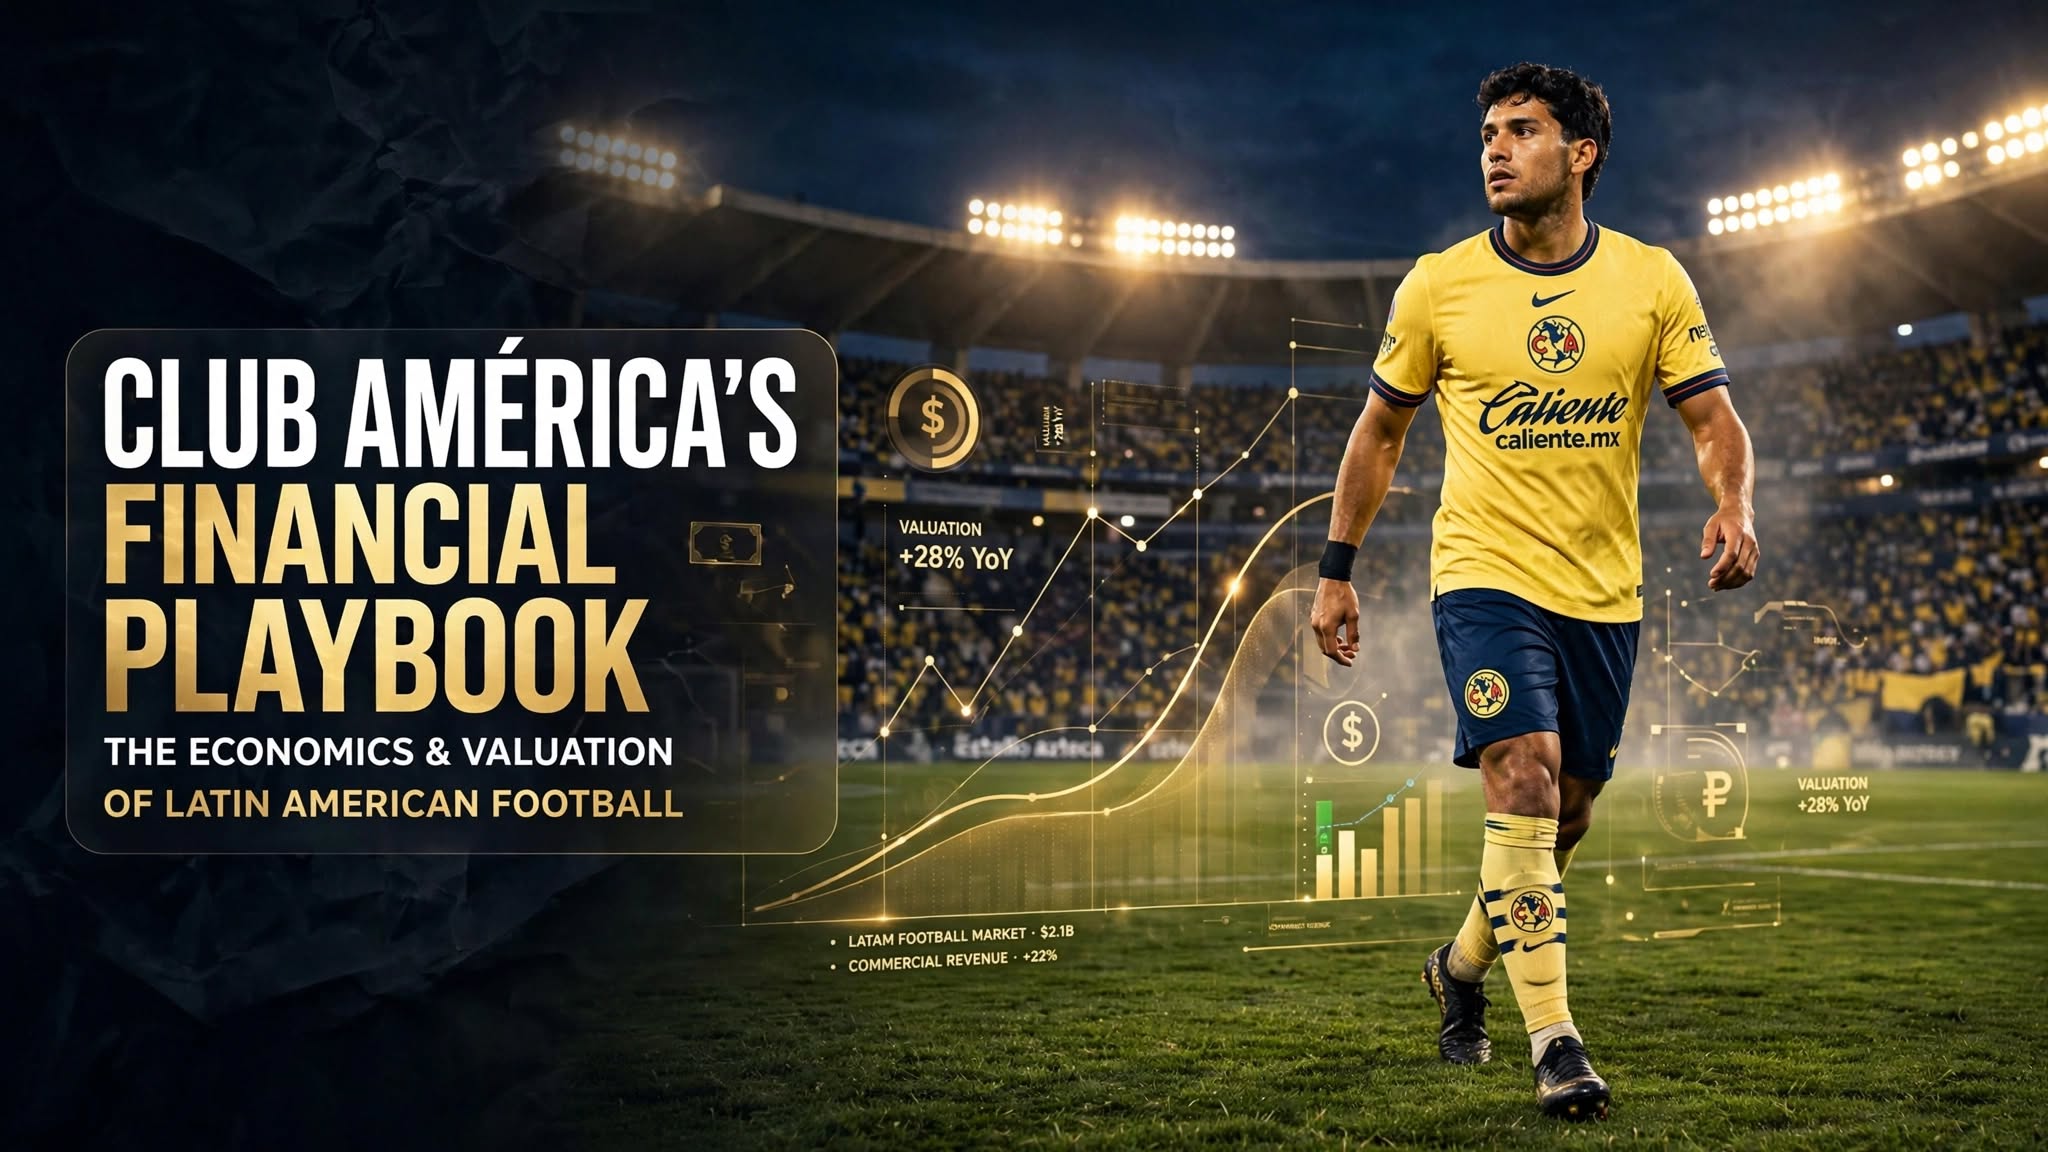
While most World Cup coverage focuses on stadiums and squads, the more consequential story in Mexican football has been playing out in enterprise-value deal structures. In late 2025, American investors closed a $490 million enterprise-value transaction for stakes in Club América and Mexico City’s iconic Azteca Stadium — a deal that, alongside a broader wave of U.S. capital entering Liga MX, reveals exactly how Latin American football is being financially re-architected just months before Mexico co-hosts the 2026 FIFA World Cup.
The Deal: Grupo Águilas and the $490 Million Structure
The transaction, announced in a joint statement to the Bolsa Mexicana de Valores (Mexico’s stock exchange), created a new holding entity called Grupo Águilas to own both Águilas del América and the 88,000-seat Estadio Azteca (rebranded Banorte Stadium), along with adjacent land, according to City A.M.’s reporting. The ownership structure splits 51% to Ollamani Group — controlled by former media tycoon Emilio Azcárraga Jean, who becomes Grupo Águilas’ executive president — and 49% to General Atlantic, the U.S. growth equity firm.
The deal’s most distinctive feature is its data and analytics component: Grupo Águilas engaged Kraft Analytics Group, a firm controlled by the owners of the NFL’s New England Patriots, specifically to support fan engagement and data analytics for the new entity, according to City A.M. — an explicit transfer of NFL-style commercial infrastructure into Mexican football operations.
Club América/Azteca deal structure:
| Element | Detail |
|---|---|
| Total enterprise value | $490 million |
| New holding entity | Grupo Águilas |
| Ollamani Group stake | 51% (Emilio Azcárraga Jean, executive president) |
| General Atlantic stake | 49% |
| Assets included | Águilas del América + Estadio Azteca (88,000 capacity) + adjacent land |
| Analytics partner | Kraft Analytics Group (New England Patriots ownership) |
| Club América standalone valuation | ~$770 million |
Why América Specifically: The Numbers Behind the Richest Club in Mexico
Club América’s standalone valuation of roughly $770 million, a figure that rivals mid-tier European clubs, makes it the most valuable soccer team in Mexico by a wide margin, according to reporting on the broader Liga MX investment wave. That scale advantage matters directly to the deal economics: América’s market value alone justifies a substantial share of the $490 million enterprise price even before accounting for the Azteca Stadium asset itself, one of the most recognizable sports venues in the world and a confirmed host site for the 2026 World Cup.
The Broader Pattern: American Capital’s Liga MX Land Grab
The Club América deal is the highest-profile example of a much wider trend. According to Front Office Sports, Querétaro became Liga MX’s first club with majority U.S. ownership when it was purchased by an American capital group for just over $120 million — a price point specifically attractive to investors because, as Querétaro investor Spiegel told FOS, “a lot of the leagues in Europe are more mature… you can’t expect that you will be able to increase revenue quickly by 30% to 50%,” whereas Mexican clubs remain underpriced relative to their audience scale.
Recent U.S.-linked Liga MX investment activity:
| Club | Investor Type | Deal Notes |
|---|---|---|
| Club América / Azteca Stadium | Growth equity + media (General Atlantic, Ollamani) | $490M enterprise value |
| Querétaro | American capital group | ~$120M; first majority US-owned Liga MX club |
| Necaxa | Celebrity investor group | Half-stake; modeled on Wrexham |
| Atlético San Luis | Buyout firm (via Atlético Madrid parent deal) | Acquired as part of broader Atlético Madrid transaction |
Why Liga MX, and Why Now
Three structural factors explain the timing of this capital influx. First, viewership: Liga MX is already one of the two most-watched soccer leagues in the United States alongside the English Premier League, with matches routinely drawing hundreds of thousands more viewers than MLS games and audiences that can swell into the millions for marquee fixtures, according to Front Office Sports. An Interticket study found the average Liga MX TV audience for a 2026 Clausura regular-season game reached 687,000 — comfortably ahead of NBC’s reported average Premier League audience of 510,000 in the same period, per ESPN’s reporting.
Second, the 2026 FIFA World Cup itself. Mexico is hosting 13 of the tournament’s 104 games across stadiums in Mexico City, Monterrey, and Guadalajara — the country’s first time on football’s biggest stage in 40 years — and figures within Mexican football believe the tournament will meaningfully raise the sport’s global commercial profile, according to Front Office Sports.
Third, structural governance reform. Liga MX is bound by a Court of Arbitration for Sport ruling requiring the return of promotion and relegation beginning with the 2026-27 season, according to ESPN. Sources told ESPN that outright relegation is unlikely to return in its traditional form; instead, the league is expected to expand the first division by promoting two teams from the second-tier Liga de Expansión and then permanently eliminate relegation going forward — a structure that would functionally mirror the closed, relegation-free model American investors are already familiar with from MLS, reducing downside risk for exactly the kind of capital now entering the league.
The Revenue Model Gap: Fragmented Rights, Unrealized Upside
Despite Liga MX’s viewership strength, its commercial infrastructure remains notably underdeveloped relative to its audience. TelevisaUnivision, which holds the bulk of U.S. broadcast rights, markets Liga MX as “the most-watched club soccer league in the country, regardless of language” — yet there is no single league-wide broadcast partner, with individual clubs instead negotiating separate rights deals, creating what ESPN describes as “a fragmented landscape for viewers.” Grupo Orlegi’s Alejandro Irarragorri told Front Office Sports that centralizing those rights would let Liga MX sell overseas coverage collectively rather than club-by-club — currently near-impossible outside the U.S. because no single club carries enough international fan base to interest overseas broadcasters on its own. The English Premier League’s 2022 milestone of earning more from overseas rights than domestic ones is the explicit long-term comparison being drawn.
Final Verdict
Club América’s $490 million enterprise-value transaction is best read as the clearest evidence yet that American investors view Mexican football the way private equity viewed European mid-tier clubs a decade ago: a market with Premier League-caliber viewership numbers, World Cup-driven momentum, and valuations that remain a fraction of comparable European assets. The addition of NFL-grade analytics infrastructure via Kraft Analytics Group, alongside the league’s looming governance shift toward a closed, relegation-light structure, signals that this is a bet on operational Americanization of Liga MX’s business model, not just a passive financial stake. The unresolved variable is media-rights centralization — until Liga MX clubs coordinate broadcast rights the way the Premier League does, the league’s valuation upside relative to its audience size will likely remain only partially realized, which is precisely the inefficiency the current wave of American capital appears to be betting it can help fix.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
The World Economic Forum’s Global Risks Report 2026 crystallizes a structural shift that has been building for nearly a decade: the world has entered an era of “multipolarity without multilateralism,” in which the erosion of rules-based international institutions is running well ahead of any emerging framework to replace them. For multinational corporations, this is no longer an abstract diplomatic concern to monitor from a distance — a 2025 Clarity Factory survey found that two-thirds of Chief Security Officers now maintain dedicated geopolitical intelligence teams, up sharply from a decade ago, even as many of those same teams struggle to get executive buy-in. Geopolitical risk software and corporate legal counsel functions that were once peripheral compliance cost centers have become, in the WEF’s own words, “inseparable from performance, resilience, and competitive advantage.”
Key Takeaways
- The WEF’s 2026 Global Risks Report explicitly frames the current moment as “multipolarity without multilateralism” — a more competitive, less rules-bound global order than at any point since the WTO’s founding in 1995.
- Two-thirds of Chief Security Officers now operate dedicated geopolitical intelligence functions, but nearly a third cite low executive understanding as the primary obstacle to having their insights actually inform business decisions.
- European multinationals cut China investment by 46% between 2021 and 2023, while U.S. firms in strategic sectors (semiconductors, software, telecommunications) have reduced staff, sales, and assets in China while reallocating R&D toward politically aligned locations.
- Despite clear financial impacts from geopolitical volatility, corporate responses remain fragmented and inconsistent — some firms, including HSBC, have actually dismantled dedicated geopolitical risk units, citing internal restructuring and cost constraints even as volatility intensifies.
- WEF interviews with senior executives from 20+ multinationals across Asia and Europe in 11 sectors reveal a clear strategic shift: companies are replacing globalized, just-in-time supply chains with regionalized configurations that prioritize agility and geopolitical insulation over pure cost efficiency.
From Predictable Rules to Transactional Diplomacy
The core diagnosis across multiple 2026 geopolitical risk reports is remarkably consistent: transactional diplomacy has replaced predictable alliance and institutional commitments. Security commitments and trade agreements that were once treated as durable, multi-decade fixtures now function more like negotiable deals subject to sudden reversal — a fundamental change in the operating assumptions multinational corporations have relied on for cross-border planning since the end of the Cold War.
| Structural Shift | 2026 Manifestation |
|---|---|
| Alliance predictability | Replaced by transactional, deal-based diplomacy |
| Institutional authority | WTO’s MC14 collapse exemplifies weakened multilateral enforcement |
| Trade agreement durability | Treated as negotiable rather than binding long-term commitments |
| Regulatory consistency | Increasing divergence across jurisdictions (“regulatory fragmentation”) |
| Market access | Increasingly politically selective rather than rules-based |
This isn’t a single-country phenomenon. The WEF’s analysis explicitly notes that while U.S. and Chinese actions are most closely watched, “all countries are affected by the changes underway,” and the transformation of the global order will continue to be shaped by the strategic interests of many countries and regions simultaneously — not a simple bilateral U.S.-China story.
The Feedback Loop: How Fragmentation Compounds Itself
One of the more sophisticated 2026 risk frameworks (from geopolitical risk consultancy analysis) identifies fragmentation not as a static condition but as an accelerating cycle: state-led industrial competition and financial strain feed social fracture and radical politics; those tensions then drive further coercion, regulatory pressure, and “grey-zone” confrontation between states; each force accelerates the next. This cyclical framing matters practically for corporate legal counsel and risk teams because it implies that waiting for stability to return before adapting corporate strategy is not a viable posture — the WEF’s own guidance is explicit that success in 2026 “is not about predicting outcomes. It is about recognizing patterns and moving early.”
Countries Are Taking Direct Control of Strategic Infrastructure
A related and increasingly significant trend is that governments are exercising stronger direct control over digital infrastructure and other strategic assets, treating them explicitly as instruments of geopolitical leverage rather than purely commercial infrastructure. This directly elevates the stakes for multinationals operating data centers, telecommunications infrastructure, or other digitally-classified “critical” assets across multiple jurisdictions, since the same infrastructure can suddenly become subject to national-security-driven intervention with little advance warning.
Corporate Response Patterns: A Widening Capability Gap
The most striking finding across 2026 corporate geopolitical risk research is the inconsistency of corporate responses despite near-universal acknowledgment of rising risk. This isn’t simply a matter of some companies being more sophisticated than others — the data reveals a genuine bifurcation in strategic posture:
| Response Pattern | Example/Evidence |
|---|---|
| Building dedicated geopolitical intelligence functions | Two-thirds of CSOs surveyed, per Clarity Factory 2025 |
| Struggling to translate intelligence into business decisions | Nearly one-third cite low executive understanding as primary obstacle |
| Dismantling existing geopolitical risk units | HSBC cited as a prominent example, citing restructuring/cost constraints |
| Reducing China-specific exposure proactively | European firms cut China investment 46% (2021-2023); US strategic-sector firms reducing staff/assets |
| Reallocating R&D to politically aligned locations | Documented across semiconductors, software, telecommunications sectors |
| Adopting “corporate diplomacy” as systematic function | Firms engaging governmental/civil-society stakeholders to manage political uncertainty as a distinct discipline |
This bifurcation creates a genuine competitive dynamic: firms that treat geopolitical risk as a core strategic input — embedded into capital expenditure decisions, supply chain design, and R&D location choices — are structurally better positioned than firms treating it as a discrete compliance exercise that can be scaled back when budgets tighten, as HSBC’s example illustrates.
Corporate Political Activity as Relational De-Risking
Recent academic research (ScienceDirect, 2026) on multinational enterprises navigating geopolitical tension identifies an evolving corporate strategy worth highlighting: corporate political activity (CPA), traditionally understood as tactical lobbying or constituency-building, is increasingly functioning as a vehicle for shaping engagement with host governments directly. By actively co-creating regulations or engaging in self-regulation, multinationals attempt to align business interests with national economic priorities — reducing exposure to adverse policy shocks through proactive relationship-building rather than reactive compliance alone.
This connects to the broader concept of corporate diplomacy: systematic engagement with governmental, supranational, and civil-society actors specifically to manage political uncertainty, which researchers now identify as the primary mechanism for managing “liability of origin” — the reputational and regulatory disadvantage multinationals face simply by virtue of their home country’s geopolitical standing in a given host market.
Strategic Shifts in Practice: What WEF’s Executive Interviews Reveal
Direct interviews with senior executives across 20+ multinationals in Asia and Europe, spanning 11 sectors, surfaced several concrete strategic patterns beyond the general “resilience” narrative:
- Regionalized supply chain configurations are replacing globalized, just-in-time models — prioritizing agility and geopolitical insulation even at the cost of some efficiency.
- Geopolitics is now a primary driver of capital expenditure decisions directly, not merely a risk factor layered onto otherwise-independent investment choices. Tariffs affecting both final goods and inputs are prompting explicit geographic reallocation of capex.
- U.S.-based production capacity investment is accelerating among surveyed executives, driven specifically by tariff-exposure mitigation and market-access security rather than traditional cost or talent considerations.
- Southeast Asia and India have emerged as preferred diversification destinations, reflecting both the “China plus one” sourcing pattern and genuine confidence in these regions’ own growth trajectories.
- M&A activity is being used for “matchmaking optimization” — not simply for scale, but specifically to expand regional footprints and secure access to critical skills and markets that geopolitical fragmentation has made harder to access through pure organic expansion or cross-border trade.
A Practical Geopolitical Risk Management Framework for 2026
- Elevate geopolitical intelligence functions to genuine board-level input, not a siloed advisory function. The finding that nearly a third of CSOs cite low executive understanding as their primary obstacle suggests the technical capability often exists — the translation into actual business decisions is the real bottleneck.
- Resist the temptation to scale back geopolitical risk capacity during cost-cutting cycles. HSBC’s example of dismantling a dedicated unit amid intensifying volatility is presented across multiple 2026 analyses as a cautionary counter-example, not a model to follow.
- Build regionalized, not merely diversified, supply chain configurations. The distinction matters: simple diversification across more countries doesn’t necessarily provide geopolitical insulation if those countries remain deeply interconnected through the same vulnerable trade routes or chokepoints.
- Treat corporate diplomacy as a formal, budgeted function rather than ad hoc government relations. Systematic stakeholder engagement is increasingly documented as the primary mechanism for managing “liability of origin” risk in geopolitically sensitive host markets.
- Embed geopolitical scenario planning directly into capital expenditure approval processes. Executives at surveyed multinationals report geopolitics is now a primary, not secondary, driver of capex decisions — risk teams should be positioned upstream in that process, not reviewing decisions after the fact.
FAQ
What does “multipolarity without multilateralism” actually mean for businesses?
It describes a world where power is increasingly distributed across multiple competing centers (the U.S., China, and various regional powers) without the rules-based institutional framework that historically constrained how that competition played out — meaning businesses face a wider range of possible outcomes with fewer reliable guardrails.
Are companies actually investing in geopolitical risk management, or is it mostly talk? It’s genuinely mixed. Two-thirds of Chief Security Officers now maintain dedicated geopolitical intelligence teams, but some major firms like HSBC have dismantled such units citing cost constraints, revealing significant inconsistency in how seriously companies are treating this risk category.
How are multinationals actually restructuring their supply chains in response to fragmentation?
Executive interviews reveal companies are shifting from globalized, just-in-time supply chain models toward regionalized configurations that prioritize agility and geopolitical insulation, with accelerating investment in U.S.-based production capacity and growing preference for Southeast Asia and India as diversification destinations.
What is “corporate diplomacy” and why does it matter now?
Corporate diplomacy refers to systematic engagement with governmental, supranational, and civil-society stakeholders to manage political uncertainty. It has become the primary mechanism multinationals use to manage the reputational and regulatory disadvantage of their home country’s geopolitical standing in sensitive host markets.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Choosing between the best CRM software and HR payroll systems in 2026 is no longer a matter of comparing feature checklists — it’s a decision about which vendor’s agentic AI architecture you want embedded in your revenue and workforce operations for the next five years. Salesforce’s Agentforce AI arm alone reached $1.2 billion in ARR, up 205% year-over-year in Q1 FY2027, while HubSpot crossed 299,458 paying customers and $3.45 billion in ARR. On the HR side, the story is about global compliance complexity: enterprises managing distributed teams across a dozen jurisdictions now need platforms that handle multi-currency payroll, localized labor law, and AI-driven workforce analytics simultaneously — not as separate systems stitched together with APIs.
Key Takeaways
- Salesforce remains the CRM market-share leader at roughly 20.7–23.8% (depending on source methodology), while HubSpot is the fastest-growing major CRM by customer count, particularly dominant in SMB and mid-market segments.
- AI is now a genuine CRM buying criterion, not a differentiator: 83% of CRM-adopting companies already use AI features, and CRM + AI delivers an estimated $13.50 ROI per dollar spent versus $3.10 for CRM alone.
- For HR payroll systems, the leading enterprise platforms — Workday, SAP SuccessFactors, Rippling, Deel, ADP Workforce Now, Ceridian Dayforce — are converging around unified HR-plus-finance-plus-AI architectures rather than standalone payroll tools.
- AI-agent pricing varies dramatically by vendor: built-in at no extra cost on platforms like GoHighLevel and Zoho Enterprise, versus roughly $500/seat for Salesforce Agentforce at the high end.
- Deel and similar platforms specializing in global compliance and payroll have become essential — not optional — infrastructure for any enterprise hiring across multiple countries in 2026.
Best CRM Software 2026: The Three-Way Enterprise Battle
| Platform | Market Position | AI Product | Best Fit |
|---|---|---|---|
| Salesforce | Market share leader (~20.7–23.8%) | Agentforce — most powerful/customizable, gated behind Enterprise+ tiers | 500+ employee enterprises with complex sales processes and dedicated admin teams |
| HubSpot | Fastest-growing by customer count (299,458+ customers) | Breeze AI — accessible out of the box, included in most plans | SMB/mid-market (1–500 employees) prioritizing usability and total cost of ownership |
| Microsoft Dynamics 365 | Strong in Microsoft-ecosystem enterprises | Copilot — most deeply embedded in daily workflows (Outlook, Teams) | Organizations already standardized on Microsoft 365/Azure |
The Cost Reality at Scale
For a 25-person team, HubSpot Professional runs approximately $38,040/year versus $49,500/year for Salesforce Enterprise — an $11,500 annual gap that widens to roughly $70,000 at 100 users before layering on Salesforce Marketing Cloud (from $1,250+/month). This is the central best CRM software decision point for growing companies: HubSpot generally delivers better ROI and faster time-to-value for mid-market teams, while Salesforce’s higher ceiling of customization and its AppExchange ecosystem (over 7,000 applications) justify the premium specifically for organizations with genuinely complex, multi-team sales processes.
AI Agent Pricing Varies by an Order of Magnitude
| Platform | AI Agent Pricing Model |
|---|---|
| GoHighLevel, Zoho (Enterprise), Freshsales | Built in at no extra seat cost |
| Pipedrive | +$20/seat |
| HubSpot Breeze | ~+$50/seat |
| Salesforce Agentforce | ~$500/seat (or ~$175/user/month for agentic capabilities specifically) |
This spread is the single most important line item CFOs should scrutinize before signing a multi-year CRM contract in 2026 — the “AI tax” on a per-seat basis can rival or exceed the base license cost at the high end of the market.
Agentforce and Breeze AI: What “Autonomous” Actually Means in Practice
The defining 2026 shift across every major CRM is the move from AI that suggests to AI that acts. Salesforce Agentforce has already secured 9,500+ paid deals and processed 3.2 trillion tokens, executing autonomous workflows like lead qualification and follow-up outreach without human initiation for each step. HubSpot’s Breeze Agents similarly research companies, draft outreach, and handle support tickets autonomously. The practical data point for buyers: 83% of sales teams using AI grew revenue in the past year, compared to teams without AI, and AI-enabled sales platforms report 30% higher win rates and 25% faster deal cycles.
HR Payroll Systems: Managing Compliance Across a Global Workforce
The HR payroll systems landscape has bifurcated into two clear tiers for 2026 buyers:
| Tier | Leading Platforms | Core Strength |
|---|---|---|
| Unified HCM/ERP suites | Workday, SAP SuccessFactors, Oracle HCM Cloud | Deep integration of HR, finance, and workforce planning on a single data model |
| Global compliance specialists | Deel, Rippling, Papaya Global | Multi-jurisdiction payroll, localized labor law, contractor/EOR management |
| Mid-market all-in-one | Paylocity, Paycom, ADP Workforce Now, Ceridian Dayforce | Strong integrations, real-time payroll processing, robust reporting |
What Global Enterprises Should Evaluate Before Choosing
- Multi-jurisdiction support. The ability to manage payroll across different states or countries — including localized tax rules, currencies, and labor law — separates genuinely global-ready platforms from domestically focused ones with bolt-on international features.
- ERP and finance-system integration. Native connectors to systems like Workday, SAP SuccessFactors, or NetSuite matter more than CSV-import compatibility; enterprises should specifically ask about open API depth, not just the existence of an integration.
- Compliance and security certifications. SOC 2 Type II and ISO 27001 are increasingly treated as baseline requirements rather than differentiators, alongside GDPR and other regional data-privacy framework support.
- Employee self-service depth. Reducing HR administrative load through self-service benefits, payroll, and time-off management is now a core expectation, not a premium feature.
- Real-time data processing. Platforms like Ceridian Dayforce differentiate specifically on processing payroll and HR changes instantly rather than in batch cycles, reducing compliance risk for distributed teams operating across time zones.
A Procurement Framework for 2026
| Organization Size | Recommended CRM Path | Recommended HR/Payroll Path |
|---|---|---|
| SMB (under 100 employees) | HubSpot or GoHighLevel (built-in AI, lower TCO) | Rippling, BambooHR, or Gusto-tier platforms |
| Mid-market (100–1,000) | HubSpot Professional/Enterprise, or Dynamics 365 if Microsoft-native | Paylocity, Paycom, or Deel for distributed teams |
| Global enterprise (1,000+) | Salesforce (Agentforce) for complex, multi-team sales orgs | Workday or SAP SuccessFactors, layered with Deel/Papaya for EOR needs |
FAQ
Which CRM has the best AI in 2026?
Salesforce Agentforce is the most powerful and customizable AI engine available in a commercial CRM, but it requires significant configuration and is gated behind Enterprise and Unlimited plan tiers. HubSpot’s Breeze AI is more accessible out of the box and better suited to fast, self-service adoption for mid-market teams.
Is HubSpot or Salesforce better for a growing company?
HubSpot generally offers better ROI and lower total cost of ownership for companies with 1–500 employees, while Salesforce’s higher ceiling of customization and enterprise-grade AppExchange ecosystem justify its premium specifically for larger organizations with genuinely complex sales processes.
What should a global enterprise prioritize in an HR payroll system?
Multi-jurisdiction support (localized tax rules, currencies, and labor law compliance), native ERP integration, and security certifications like SOC 2 Type II and ISO 27001 should be non-negotiable evaluation criteria for any organization managing a workforce across multiple countries.
How much does AI functionality add to CRM costs?
It varies enormously by vendor — from built-in at no extra cost on platforms like Zoho Enterprise and GoHighLevel, to roughly $20/seat on Pipedrive, $50/seat on HubSpot Breeze, and as much as $500/seat for Salesforce Agentforce’s full agentic capabilities.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

iOS 27 Release Date & Siri AI: The Ultimate Tech News Guide for iPhone 18 Users

Club América’s Financial Playbook: The Economics and Valuation of Latin American Football

Best iPhone 18 Pro Max Cases: Premium Protection for Apple’s 2026 Flagship

Fragmentation of Multilateralism 2026: Geopolitical Risk for MNCs

Top CRM and HR Software Solutions for Managing a Global Workforce in 2026

Trump’s North America Flag Map Explained: Viral Image, USMCA Tensions

2026 Midterms: How Democrats Are Competing in Deep-Red Senate Seats

North American Tariff Standoff 2026: Supply Chain Guide

2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover

Johnny Ray and Nicole Mississippi: Attala County Case Explained
2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover

Best Fitness Apps and Wearables That Connect to Health Insurance in 2026

Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown

RFK Jr. Confirmation Investigation 2026: Health Policy Fallout Explained
2026 Midterms: How Democrats Are Competing in Deep-Red Senate Seats

Fond du Lac Stalking Case: Serial-Killer Memorabilia, Skulls & the Criminal Complaint
North American Tariff Standoff 2026: Supply Chain Guide

Shanghai Ravioli Chicken Recall 2026: Full Product List & Refund Guide
-

 Featured5 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Democracy5 years ago
Missing You! SPSC
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills