News
Analyzing Anthropic’s $15 Billion Credit Facility: What It Means for Stock Health

Amid all the attention on Anthropic’s reported $2 trillion IPO valuation target, a quieter but arguably more consequential financial detail has emerged: the company is finalizing a $15 billion pre-IPO credit facility, according to Bloomberg reporting. Debt financing decisions made in the months before a public listing say a great deal about a company’s capital needs and risk profile — here’s what this facility actually signals for investors evaluating Anthropic’s long-term stock health.
Table of Contents
Key Takeaways
- Anthropic is reportedly finalizing a $15 billion revolving credit facility, up from an earlier reported target exceeding $10 billion.
- The facility is being arranged by the same banks reportedly leading the equity IPO — Morgan Stanley, Goldman Sachs, and JPMorgan — which previously provided Anthropic debt financing.
- The credit line exists alongside a reported ~$42 billion net loss in 2025, even as the company reached positive adjusted operating income in Q2 2026.
- Debt facilities of this size are typically used for working capital flexibility and compute infrastructure spending, not permanent capital structure financing.
- How this facility is drawn down and disclosed in the S-1 will be a key signal of Anthropic’s capital intensity relative to its revenue growth.
What a Pre-IPO Credit Facility Actually Is
A revolving credit facility functions differently from the equity capital an IPO raises. Rather than permanent capital in exchange for ownership, it’s a line of credit the company can draw on and repay as needed — similar in concept to a corporate credit card with a very large limit, typically secured against assets or backed by the company’s cash flow and creditworthiness.
Companies preparing for an IPO often arrange credit facilities in the months beforehand for several reasons:
- Bridging capital needs before IPO proceeds are actually received
- Funding capital expenditures (in Anthropic’s case, compute infrastructure) without diluting equity holders further before the offering
- Signaling creditworthiness to public market investors, since securing a large facility from top-tier banks implies those banks’ credit committees have reviewed and approved the company’s financial position
- Maintaining flexibility for opportunistic spending, such as compute capacity commitments, without needing to raise additional equity
Why $15 Billion, and Why Now
Reporting indicates the facility’s size grew from an earlier target exceeding $10 billion to the current $15 billion figure — an increase that tracks with Anthropic’s own revenue and infrastructure scaling over the same period. This timing is notable: the facility is being finalized in parallel with the IPO process itself, not as a separate, unrelated financing event.
The banks arranging the facility — Morgan Stanley, Goldman Sachs, and JPMorgan — are the same institutions reportedly competing for lead roles on the equity offering. This dual relationship (debt provider and equity underwriter) is common in large-cap tech IPOs, but it means these banks have deep, direct visibility into Anthropic’s balance sheet and cash flow needs heading into the roadshow — visibility that goes well beyond what’s captured in investor-relayed revenue run-rate figures.
What the Facility Signals About Compute Spending
Frontier AI companies face a structural challenge that traditional software companies don’t: the cost of training and running large language models scales directly with usage and model capability, creating enormous ongoing capital expenditure needs even as revenue grows. Anthropic’s reported ~$42 billion net loss in 2025 — roughly five times its $8.3 billion loss the year before — reflects this dynamic directly.
A $15 billion credit facility gives Anthropic a funding buffer to continue scaling compute infrastructure — including a reported multi-year computing arrangement with SpaceX potentially worth tens of billions of dollars — without depending entirely on either operating cash flow or dilutive equity raises to fund that growth in real time.
Debt vs. Equity: What It Means for Post-IPO Stock Health
For investors evaluating the eventual publicly traded stock, the credit facility matters in a few concrete ways:
1. Balance Sheet Leverage
A $15 billion facility, even if not fully drawn, represents a real contingent liability. Public market investors will want to see, once the S-1 becomes public, how much of the facility is drawn, at what interest rate, and under what covenants — details that affect the company’s financial flexibility during any future growth slowdown.
2. Reduced Near-Term Dilution Pressure
By using debt rather than additional equity rounds to fund infrastructure spending in the run-up to the IPO, Anthropic avoids diluting existing shareholders further before the offering — a detail that modestly supports the per-share economics for both pre-IPO investors and eventual public shareholders, assuming the debt is serviceable.
3. A Read on Lender Confidence
Top-tier banks don’t extend $15 billion in committed credit without confidence in a company’s ability to service that debt. The facility’s existence — and its growth from an earlier sub-$10 billion target — is itself a data point suggesting lenders are underwriting continued revenue growth, even if that growth eventually falls short of the more bullish $100–120 billion full-year 2026 projections.
Comparing Anthropic’s Financial Profile
| Metric | Figure | Context |
|---|---|---|
| 2025 net loss | ~$42 billion | ~5x the $8.3B loss in 2024 |
| Q2 2026 adjusted operating income | Positive | First reported profitability inflection |
| Pre-IPO credit facility | ~$15 billion | Up from earlier >$10B target |
| Revenue run rate (July 2026) | ~$65 billion | Up from $9B at end of 2025 |
| Series H valuation (May 2026) | $965 billion | Prior to IPO valuation discussions |
The juxtaposition here is the crux of the entire investment debate: explosive revenue growth alongside historically large net losses, bridged by both a Series H equity raise and now a substantial credit facility. Whether that combination represents a company appropriately investing for scale, or one whose unit economics remain fundamentally unproven, is likely to be the central question analysts probe once the S-1’s audited figures are public.
Risks Specific to the Credit Facility
- Interest rate exposure. Revolving facilities of this size typically carry floating interest rates tied to benchmark rates; higher-for-longer rate environments increase the carrying cost of any drawn balance.
- Covenant risk. Large credit facilities often include covenants — financial conditions the borrower must maintain — that could restrict operational or capital allocation flexibility if triggered.
- Refinancing dependency. If compute spending needs continue to outpace operating cash flow generation well into the post-IPO period, the company may need to return to debt or equity markets again, a scenario that could pressure the stock if it happens sooner than investors expect.
FAQ
What is Anthropic’s $15 billion credit facility for?
It’s reportedly intended to give Anthropic balance sheet flexibility to fund continued compute infrastructure spending and working capital needs ahead of and around its IPO, without relying solely on operating cash flow or additional equity dilution.
Who is providing Anthropic’s credit facility?
Reporting indicates Morgan Stanley, Goldman Sachs, and JPMorgan — the same banks reportedly leading the equity IPO — are involved in structuring the facility, alongside their prior role as Anthropic’s debt financiers.
Does the credit facility mean Anthropic is in financial trouble?
Not necessarily. Large credit facilities are a standard and often prudent tool for capital-intensive, high-growth companies, especially ahead of an IPO. It should be read alongside the company’s reported positive adjusted operating income in Q2 2026, not as a standalone distress signal.
How will this affect Anthropic’s stock after it goes public?
The facility itself is a balance sheet item that will be disclosed in the company’s audited financials. Its size relative to the company’s cash flow generation, along with the interest rate and covenant terms, will be key details investors evaluate when assessing the stock’s financial risk profile post-listing.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


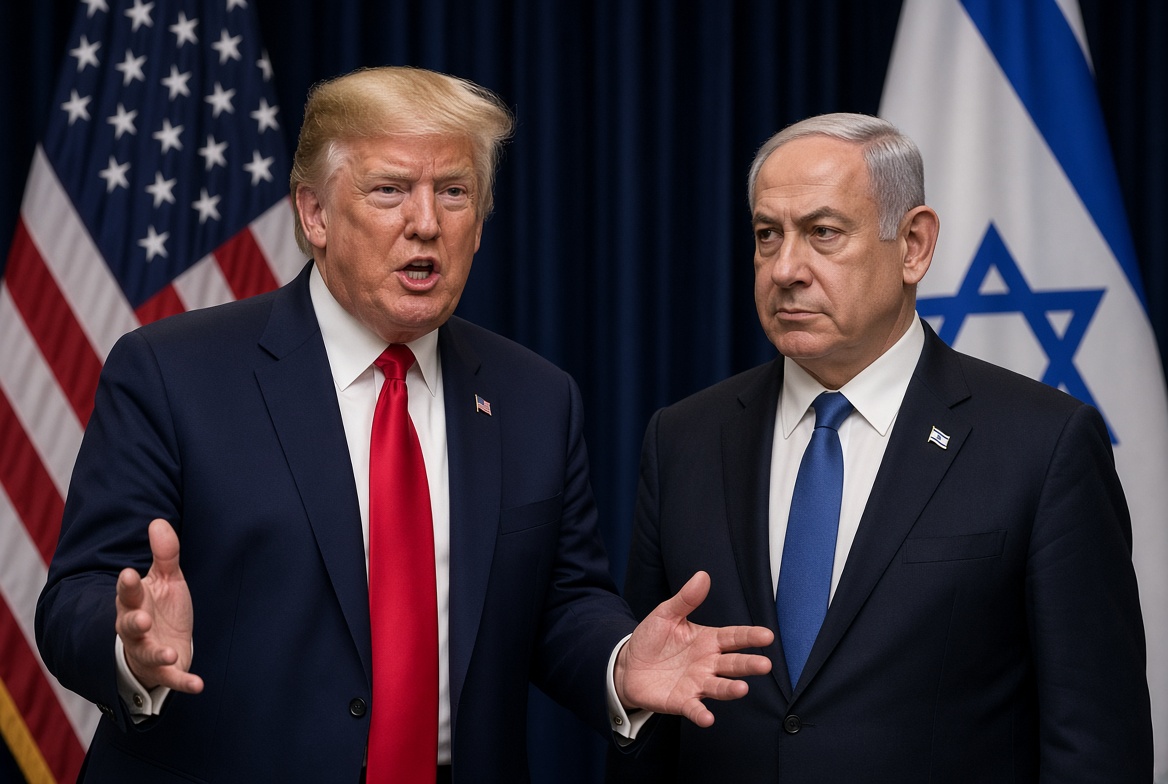
President Donald Trump said Tuesday that the United States will end its roughly $4 billion in annual funding to Israel by the close of this year under an agreement he reached months ago with Israeli Prime Minister Benjamin Netanyahu.
Speaking by phone on Fox News’ Fox & Friends as Americans voted in the midterm elections, Trump stated that the two leaders had decided to halt the payments because Israel “doesn’t need it” and to remove what he described as a damaging political talking point used by critics.
“Now, as far as paying Israel, Bibi Netanyahu and I have made a deal that we give Israel $4 billion a year, and we made a deal months ago that we’re stopping,” Trump said. “We’ve already agreed that by the end of this year we won’t be paying Israel. Now, we’ll help Israel if they need it.”
Trump added that Netanyahu had raised the idea himself, saying the Israeli leader told him it would be “appropriate” not to receive the aid given domestic political controversy in the United States. He specifically referenced criticism from Democratic Michigan Senate candidate Abdul El-Sayed and others on the left, calling continued payments “a bad talking point”.
The announcement immediately raised questions about implementation. The current U.S.-Israel Memorandum of Understanding, which provides about $3.8 billion annually in military assistance, does not expire until 2028. U.S. military aid to Israel is appropriated by Congress, and experts noted that abrupt termination of ongoing programs—particularly in missile defense and counter-drone systems—would face legal and logistical hurdles. Trump has not detailed the precise mechanism or timeline for ending the funding.
There was no immediate confirmation from Netanyahu’s office or Israel’s foreign ministry. Israeli defense and financial officials were reportedly caught off guard by the public statement. The U.S. State Department did not respond to requests for comment.
The move comes amid declining American public support for unconditional aid to Israel since the war in Gaza that began in 2023. A recent Quinnipiac University poll found that nearly half of U.S. voters overall, and two-thirds of Democrats, believe the United States is too supportive of Israel. Aid to Israel has also become a point of contention within the Republican Party, drawing criticism from some isolationist and “America First” voices.
Trump framed the decision as consistent with a strong alliance, emphasising that the U.S. would continue to support Israel “if they need it” and that Israel remains a key partner. He noted that Israel could still purchase American weapons.
Analysts described the timing—on Election Day—as potentially aimed at neutralising attacks from both progressive Democrats and some within the MAGA coalition. Former Republican Rep. Marjorie Taylor Greene wrote on X that the announcement was unlikely to change midterm results, while others questioned whether the pledge would hold after the election.
The development marks a significant rhetorical shift in a relationship that has included steady U.S. military financing for decades. Whether the stated cutoff materialises by the end of 2026, and in what form, remains unclear pending further details from the White House and any formal agreement with Israel.
References
Al Jazeera. (2026, November 3). Trump says US will stop giving Israel aid after year-end. https://www.aljazeera.com/news/2026/11/3/trump-announces-that-us-will-stop-paying-israel-after-year-end
Debusmann, B., Jr. (2026, November 3). Trump says US ‘won’t be paying Israel’ by end of year. BBC News. https://www.bbc.co.uk/news/articles/cmx2dlx86n9yo
Reuters. (2026, November 3). Trump says US will stop $4 billion in funding to Israel at end of 2026. https://www.reuters.com/world/middle-east/trump-says-us-will-stop-paying-israel-after-year-end-2026-11-03/
Times of Israel. (2026, November 3). Trump says US to end $4 billion in annual military aid to Israel by end of 2026. https://www.timesofisrael.com/trump-says-us-to-end-4-billion-in-annual-military-aid-to-israel-by-end-of-2026/
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
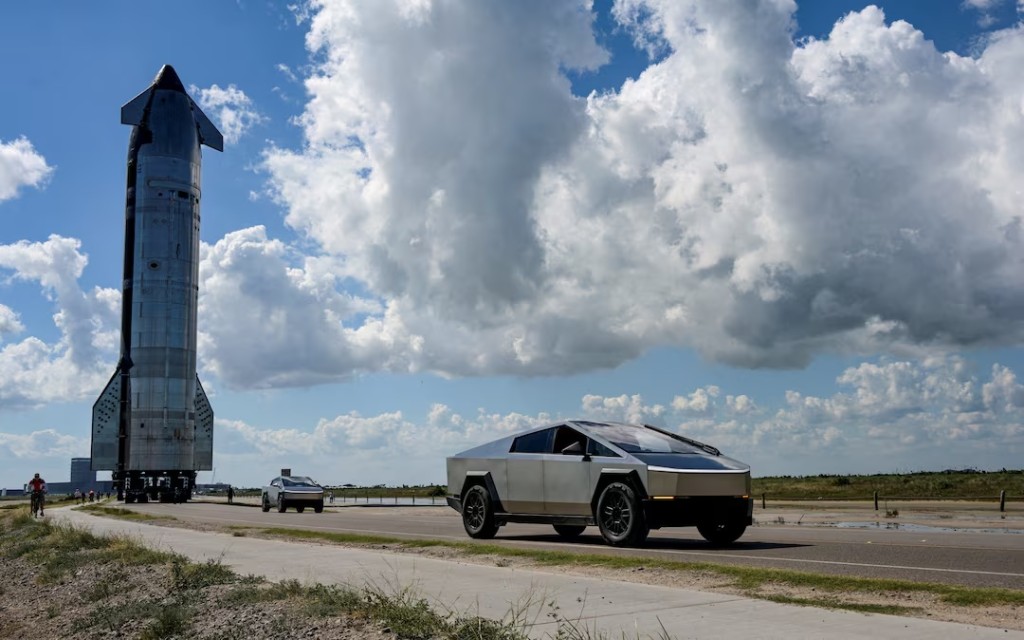
Three headlines about Elon Musk’s companies appeared to tell unrelated stories: a spectacular electric sports car, a possible corporate merger and growing dependence on satellite connectivity. Read together, they reveal a broader contest over capital, engineering and control of digital infrastructure.
The key is to separate announcements, proposals and operational results. A demonstrated vehicle capability is not a mass-production date. A corporate committee is not a completed merger. And satellite coverage is not the same as unrestricted service under every political or security condition.
Tesla Roadster: the spectacle and the schedule
Reuters reported in mid-October on a next-generation Tesla Roadster demonstration involving SpaceX-inspired thruster technology. The report also indicated that customer deliveries would not begin until 2028. The distinction between a prototype showcase and a product ready for buyers is the most important one for readers evaluating Tesla’s technology ambitions.
A dramatic unveiling can demonstrate engineering intent. What follows is less glamorous: homologation, manufacturing readiness, servicing plans, warranty commitments, cost control and repeatable performance in ordinary conditions. Prospective buyers should not treat estimated specifications or on-stage promises as final contract terms.
SpaceX–Tesla merger talks: possible is not agreed
Reuters reported on October 22 that a potential merger would require Musk’s approval, even as governance considerations complicated the discussion. Committees studying a deal have not, by themselves, established a price, transaction structure, regulatory clearance or shareholder outcome.
The strategic case is obvious to enthusiasts: electric vehicles, robotics, satellites, artificial intelligence and computing capacity might be marketed as a single integrated ecosystem. The drawbacks are equally serious. A conglomerate can obscure business-level performance, increase capital-allocation conflicts and make valuation harder. Directors and shareholders would need to scrutinise related-party interests and who benefits from any exchange ratio.
The less cinematic AI numbers
Reuters’ October earnings coverage described rapid revenue growth in SpaceX’s AI business alongside a sharp increase in capital spending. Investors should resist both extremes: dismissing all AI demand as hype or assuming revenue growth guarantees attractive free cash flow. Data-centre infrastructure needs chips, sites, power and expensive maintenance.
Fast revenue growth can coexist with high valuation risk. The test is whether new businesses eventually finance their own expansion while preserving adequate returns to capital providers.
Starlink’s national-security dilemma
Satellite networks promise resilience when terrestrial networks fail. They also create dependence on operators with technical control over service policies, access and availability. October reporting on Starlink and Ukraine highlighted how restrictions or changes in operational capability can acquire strategic significance. The Reuters account noted statements by Ukrainian officials about restored connectivity at high travel speeds; statements about the causes of earlier restrictions require careful attribution.
For governments and businesses, diversification may therefore matter almost as much as signal quality. Critical communications need backups, clear contracts and a plan for service interruption.
Five questions before believing the next Musk headline
| Claim | Verification test |
|---|---|
| A rocket or vehicle can perform a feat | Independent evidence of a completed demonstration |
| A car launches next year | Confirmed production, approvals and delivery schedule |
| Two companies are merging | Filed agreement, board and shareholder approvals |
| AI business is profitable | Cash flow, costs and credible segment disclosure |
| Satellite service is universally available | Licence, coverage, capacity and contractual terms |
Why the story matters outside the US
Pakistan and other emerging markets look to satellite broadband, low-cost electric technology and AI tools for development opportunities. They also face affordability, spectrum and regulatory questions. Importing a futuristic product is not a substitute for competition policy or infrastructure resilience.
Corporate governance will matter as much as engineering
A potential deal between companies closely associated with the same entrepreneur raises questions about valuation, conflicts and decision-making. Independent directors must consider whether each shareholder group receives fair treatment; enthusiasm for a shared brand is not a substitute for transaction terms. Investors should distinguish a serious formal proposal from a public comment about strategic possibilities.
There is also a different risk profile across the businesses involved. A vehicle manufacturer faces factory utilisation, safety recalls and consumer financing. A satellite operator depends on launch capabilities, spectrum arrangements, recurring subscriptions and government permissions. AI computing infrastructure adds yet another profile involving power costs, hardware replacement and contract concentration. Combining these enterprises does not make their underlying risks disappear.
For followers of the space programme, the next meaningful milestone is evidence of repeated operational success, not a promise that a future mission will use advanced recovery methods. For EV buyers, it is a firm delivery programme with defined specifications. For connectivity users, it is consistent service under known contractual conditions.
A restrained technology roundup can celebrate ambitious engineering while continuing to ask ordinary questions about reliability, costs and the institutions that oversee it.
Are Tesla and SpaceX already one company?
No. Reported discussions and committees do not establish a completed merger.
Does a Roadster prototype guarantee 2028 deliveries?
No. The announced timeline remains subject to production and regulatory realities.
Can Starlink replace every terrestrial telecom network?
No. It may be particularly valuable in hard-to-serve areas or emergencies, but capacity, cost and regulation still matter.
The overlooked theme: Musk’s ventures are increasingly connected by shared ambitions and capital demands. The more compelling editorial question is not what they can announce, but which promises can be delivered at scale and at a defensible cost.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
October is Major League Baseball’s postseason month, with the League Championship Series leading toward the World Series. MLB’s official October 9 update listed league championship broadcasting arrangements and said its complete postseason schedule was subject to change. That is the appropriate basis for a service article, rather than relying on viral bracket graphics. Sources: MLB and NBA.
The important context competitors can overlook
The playoff path moves through the Wild Card Series, Division Series, League Championship Series and World Series. Series lengths differ, affecting travel planning, pitching strategies and when a potential deciding game may occur. Weather, broadcast adjustments and series ending early can all change the actual date of a matchup. A guide should therefore distinguish tentative “if necessary” games from guaranteed events. For primary-source checks and current reporting, see MLB and NFL. The key distinction is practical broadcast and bracket explainer with no fictitious results.
October baseball moves through elimination series toward the World Series. Games marked ‘if necessary’ depend on earlier series results. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
Use MLB’s live bracket and broadcast information for tonight’s specific matchup, while this article provides the enduring format explanation. If publishing a result, record the completed date and source. Viewers should check the network, streaming eligibility and local restrictions before paying. Avoid declaring future participants or game outcomes without an official final score.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Where is the authoritative 2026 playoff schedule? MLB publishes and updates it at MLB.com/postseason.
Why are some dates marked if necessary? Best-of-series matchups end once a team wins the required number of games.
How the MLB postseason bracket works
Major League Baseball’s postseason includes division winners and wild-card teams, followed by a sequence of elimination series that eventually determines each league champion and the World Series participants. The rounds use different series lengths; that affects pitching strategy, bullpen workload and how quickly a team can be eliminated. A single-game result in a best-of-series contest is important but not always decisive. Readers should consult MLB’s official postseason hub for the bracket rather than rely on an old graphic that may not reflect completed games.
Home-field advantage, seeding and tiebreaking rules add context to the matchup schedule. Those details can vary by competition edition, so the official rules should be checked instead of recycled from a prior year. When a postseason series has not yet finished, the next opponent remains conditional. An article should say “winner of Series A will face…” rather than assign a future opponent before the result exists.
Why starting pitching changes a short series
Starting pitchers often shape the first half of a game, but playoff success requires bullpen management, defense, baserunning and timely hitting. A team may start its most experienced pitcher in the first game and then adjust the rotation based on rest, health and earlier results. Managers must also decide when to use their strongest relief pitchers. Those choices can matter more in a short series than in a long regular season where roles and workloads can be smoothed across many games.
Baseball statistics need sample-size discipline. A hitter’s performance over ten postseason plate appearances tells less about underlying ability than a much longer period of play. Analysts can compare strikeout rates, on-base production and matchup tendencies while avoiding exaggerated claims drawn from one home run or one defensive error. Recent injuries and announced starting lineups can change the outlook quickly.
Broadcast rights and local time differences
A game carried by a U.S. broadcaster may require a different provider for an international audience. Some streaming services include blackout restrictions and authenticated subscriptions. Before directing readers to a platform, check the league’s official listing for the game, region and date. A schedule can shift because of series outcomes or weather; do not assume every potential Game 6 or Game 7 will occur. Conditional games should be clearly labeled so viewers do not subscribe or travel based on a nonexistent fixture.
Fans outside North America should verify dates carefully. A game beginning late at night in U.S. Eastern Time can appear on the following morning in Pakistan or elsewhere. A credible global article uses time-zone labeling and, where practical, provides local conversions while directing readers to official confirmations.
Planning a trip to a postseason game
Buy tickets through the team’s verified ticket office or a recognized authorized resale route. Read what happens to a ticket for an “if necessary” game that is never played. Lodging and transportation may be nonrefundable even when the ticket itself is refunded under a particular policy. Stadium entry rules, bag restrictions and transport can vary by venue. Travel budgets should include potential schedule shifts, especially when the identity of the next opponent is not yet known.
Reseller offers that look dramatically cheaper than the going rate can be fraudulent. Confirm seat location, transfer method and the platform’s buyer-protection terms. Never assume an image of a barcode sent by a stranger proves a usable ticket. The simplest defense is to purchase through verified channels and retain the order record.
A bracket-tracking method that stays accurate
For each series, maintain the teams, seeds, current games-won tally, next confirmed game time, probable or announced starters, broadcaster and a direct MLB link. Update each row only after official results. Distinguish “clinched” from “leads series.” If a matchup concludes earlier than its maximum length, remove unused dates or mark them canceled; otherwise a static editorial calendar can appear inaccurate within hours.
The purpose of a postseason guide is not to predict every winner. It is to make a fast-moving bracket understandable and give fans reliable answers on what happens next, where to watch and which details remain uncertain.
Baseball postseason questions answered
Does every potential game on a postseason schedule occur?
No. A best-of-seven series ends when one team reaches four wins. Games listed as “if necessary” do not take place if the series has already been decided. Ticket buyers and travelers should understand refund or cancellation policies associated with those conditional dates before arranging flights and hotels.
Why do playoff teams use pitchers differently?
A shorter series changes the cost of saving an elite relief pitcher or spacing starting assignments. Managers may make aggressive substitutions to protect a narrow lead, while maintaining enough arms for a possible next game. Such choices can look different from regular-season strategy, when teams plan around a longer schedule and broader workload management.
Can a postseason match move after its first announcement?
Yes. Broadcast planning, prior series results and circumstances such as weather can affect schedules. MLB’s official game page and league notices should be checked shortly before travel or viewing. An editorial table that fails to update conditional games can easily mislead readers as the bracket advances.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Congress can’t stop Trump’s wars. It can make them expensive.

The Millers and the New Washington Power Couple

The Municipal Left Turn: Can They Govern?

The First Muslim Senator and the Limits of America’s Midterm Revolt

Trump Announces U.S. Will Stop $4 Billion Annual Aid to Israel by End of 2026

What Is Trump Doing on Election Day 2026? Inside His White House Plans

Tesla, SpaceX and Starlink: The Real Business Story Behind Elon Musk’s October Buzz

Resilience Under Strain: The World’s Difficult 2026 Choices

Andy Harris in 2026: Freedom Caucus Influence, Spending and Congressional Power
What Is Trump Doing on Election Day 2026? Inside His White House Plans
Resilience Under Strain: The World’s Difficult 2026 Choices
Trump Announces U.S. Will Stop $4 Billion Annual Aid to Israel by End of 2026

MLB Playoffs 2026: Postseason Format, Broadcast Guide and How to Track the Bracket
Tesla, SpaceX and Starlink: The Real Business Story Behind Elon Musk’s October Buzz
Andy Harris in 2026: Freedom Caucus Influence, Spending and Congressional Power
The First Muslim Senator and the Limits of America’s Midterm Revolt
The Millers and the New Washington Power Couple
The Municipal Left Turn: Can They Govern?
-

 Featured6 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Democracy5 years ago
Missing You! SPSC
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day