News
Exploring the Biggest News Channels of the World: The Analysis and Metrics

News channels are an essential part of our daily lives, keeping us informed about what is happening around the world. With the rise of digital media, news channels have become more accessible than ever before. The world’s biggest news channels have a global reach, providing news and information to millions of people around the world. In this article, we will be discussing the top 10 biggest news channels in the world.
Table of Contents
Global Influence and Reach
The world’s biggest news channels have a global influence and reach. They are watched by millions of people around the world, and their content is translated into multiple languages. These news channels have a significant impact on public opinion and are often seen as the voice of authority on important issues.
Audience and Viewership Numbers
The audience and viewership numbers of the world’s biggest news channels are staggering. These news channels have millions of viewers around the world, with some channels having a reach of over 100 million viewers. The audience and viewership numbers of these news channels are a testament to their quality of content and programming.
Key Takeaways
- The world’s biggest news channels have a global influence and reach, providing news and information to millions of people around the world.
- These news channels have staggering audience and viewership numbers, with some channels having a reach of over 100 million viewers.
- The quality of content and programming of these news channels is reflected in their massive audience and viewership numbers.
Global Influence and Reach

When it comes to the biggest news channels in the world, global influence and reach are two crucial factors to consider. The ability to reach a wide audience and have an impact on the world’s affairs is what sets these news channels apart from the rest.
One way to measure the global influence of a news channel is by looking at its viewership numbers. CNN, for example, has an estimated global viewership of over 200 million households, making it one of the most-watched news channels in the world. Other news channels with a significant global reach include BBC News, Al Jazeera, and Fox News.
Another way to measure global influence is by looking at the number of countries where a news channel has a presence. BBC News, for instance, has a network of correspondents in over 200 countries, making it one of the most widely distributed news channels in the world. Similarly, Al Jazeera has a presence in over 100 countries, while CNN has bureaus in more than 30 countries.
In addition to viewership and distribution, the reputation and credibility of a news channel also play a significant role in its global influence. Channels like BBC News and CNN are widely regarded as trustworthy sources of news, and their reporting often has a significant impact on global events.
Overall, the global influence and reach of a news channel are crucial factors to consider when ranking the biggest news channels in the world. While viewership and distribution are essential, the reputation and credibility of a news channel are equally important in determining its global influence.
Audience and Viewership Numbers

Comparative Analysis
When it comes to the biggest news channels in the world, audience and viewership numbers play a critical role in determining their position. CNN (Cable News Network) is one of the most-watched news channels globally, with an estimated 212 million viewers worldwide. CNN’s viewership numbers are followed by BBC News, which has a viewership of around 121 million globally. Fox News Channel, MSNBC, and Al Jazeera English are some other significant players in the news industry.
In terms of specific countries, the United States has the most significant number of news viewers, followed by China, India, and the United Kingdom. CNN and Fox News Channel are the two most popular news channels in the United States, with both channels having a loyal viewership base.
Regional Dominance
In addition to global viewership numbers, regional dominance is also an essential factor in determining the biggest news channels in the world. For example, in the United States, Fox News Channel dominates the cable news market, followed by CNN and MSNBC. In the United Kingdom, BBC News is the most-watched news channel, with Sky News being the second most popular.
In India, the public broadcaster Doordarshan News and private news channel Republic TV are among the most-watched news channels. In China, the state-run China Central Television (CCTV) is the most popular news channel, followed by Phoenix Television and Hong Kong-based Television Broadcasts Limited (TVB).
Overall, the biggest news channels in the world are those that have a loyal viewership base and offer comprehensive coverage of global events. While audience and viewership numbers are essential, the quality of reporting and credibility of the news channel are also critical factors that determine their position in the industry.
Content and Programming Quality

When it comes to news channels, content and programming quality are the most critical factors that determine their success. The biggest news channels of the world have a reputation for providing high-quality content that is informative, engaging, and unbiased.
One of the ways news channels ensure high-quality content is by investing heavily in their newsrooms. They hire experienced journalists, editors, and producers who have a deep understanding of the news and can deliver it in a way that is clear, concise, and engaging. They also have state-of-the-art equipment and technology that allows them to cover breaking news in real-time and provide viewers with up-to-date information.
Another way news channels ensure high-quality content is by having a diverse range of programming. They cover a wide range of topics, including politics, business, sports, entertainment, and more. They also have a mix of live and pre-recorded programming, which allows them to cover breaking news while also providing in-depth analysis and commentary on current events.
News channels also have a responsibility to ensure that their content is unbiased and objective. They strive to provide viewers with the facts and let them form their opinions. To achieve this, they have strict editorial policies and guidelines that ensure that their reporting is fair and balanced.
Overall, the biggest news channels of the world are known for their high-quality content and programming. They invest heavily in their newsrooms, have a diverse range of programming, and strive to provide unbiased and objective reporting. These factors have helped them build a loyal audience and establish themselves as the go-to source for news and information.
Digital Presence and Innovation

In today’s digital age, having a strong online presence is crucial for any news channel to stay relevant and reach a wider audience. The top news channels of the world have recognized this fact and have made significant efforts to establish themselves as leaders in the digital space.
One such example is CNN, which has a strong digital presence with its website and mobile app. The website features a clean and user-friendly interface, with easy navigation and a wide range of news categories. The mobile app is also well-designed and offers users a personalized news experience with customizable alerts and notifications.
Another news channel that has embraced digital innovation is the BBC. The BBC has a strong social media presence, with millions of followers on platforms such as Twitter, Facebook, and Instagram. The BBC also offers a range of podcasts and has its own mobile app, which allows users to access news content on the go.
Al Jazeera is another news channel that has made significant efforts to establish its digital presence. The channel has a well-designed website that offers users a range of news categories and features. Al Jazeera also has a strong social media presence, with millions of followers on platforms such as Twitter and Facebook. Additionally, the channel has its own mobile app, which offers users access to live news streams and on-demand content.
Overall, the top news channels of the world have recognized the importance of digital innovation and have made significant efforts to establish themselves as leaders in the digital space. Through their websites, mobile apps, and social media presence, these news channels have been able to reach a wider audience and stay relevant in today’s fast-paced digital world.
Ownership and Media Conglomerates

The biggest news channels of the world are often owned by large media conglomerates. These corporations have significant influence over the news that is reported and the way it is presented. Here are some of the largest media conglomerates that own major news channels:
- Comcast: Comcast is the largest media conglomerate in the world, with assets that include NBCUniversal, Sky, and DreamWorks Animation. NBCUniversal owns news channels such as NBC News, MSNBC, and CNBC, while Sky has a significant presence in Europe with channels like Sky News.
- The Walt Disney Company: The Walt Disney Company is another major player in the media industry, with assets that include ABC News and ESPN. In addition, Disney owns a controlling stake in Hulu, which has its own news division.
- ViacomCBS: ViacomCBS was formed by the merger of Viacom and CBS in 2019. The company owns news channels such as CBS News, CBSN, and 60 Minutes.
- News Corp: News Corp is a media conglomerate owned by Rupert Murdoch. The company owns news channels such as Fox News, Sky News Australia, and The Wall Street Journal.
- AT&T: AT&T is a telecommunications company that also owns media assets such as WarnerMedia. WarnerMedia owns news channels such as CNN and HLN.
- Bertelsmann: Bertelsmann is a German media conglomerate that owns assets such as RTL Group and Penguin Random House. RTL Group owns news channels such as RTL Television and RTL Radio.
- Sony: Sony is a Japanese conglomerate that owns assets such as Sony Pictures and Sony Music. Sony Pictures owns news channels such as India Today and AXN News.
- Discovery: Discovery is a media company that owns assets such as Discovery Channel and Animal Planet. The company also owns news channels such as Eurosport News and DMAX.
- The New York Times Company: The New York Times Company is a media company that owns assets such as The New York Times and The Boston Globe.
- Gannett: Gannett is a media company that owns assets such as USA Today and local newspapers across the United States.
These media conglomerates have significant influence over the news that is reported to the public. News consumers need to be aware of who owns the news channels they are watching or reading, as this can affect the way the news is presented and the stories that are covered.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.


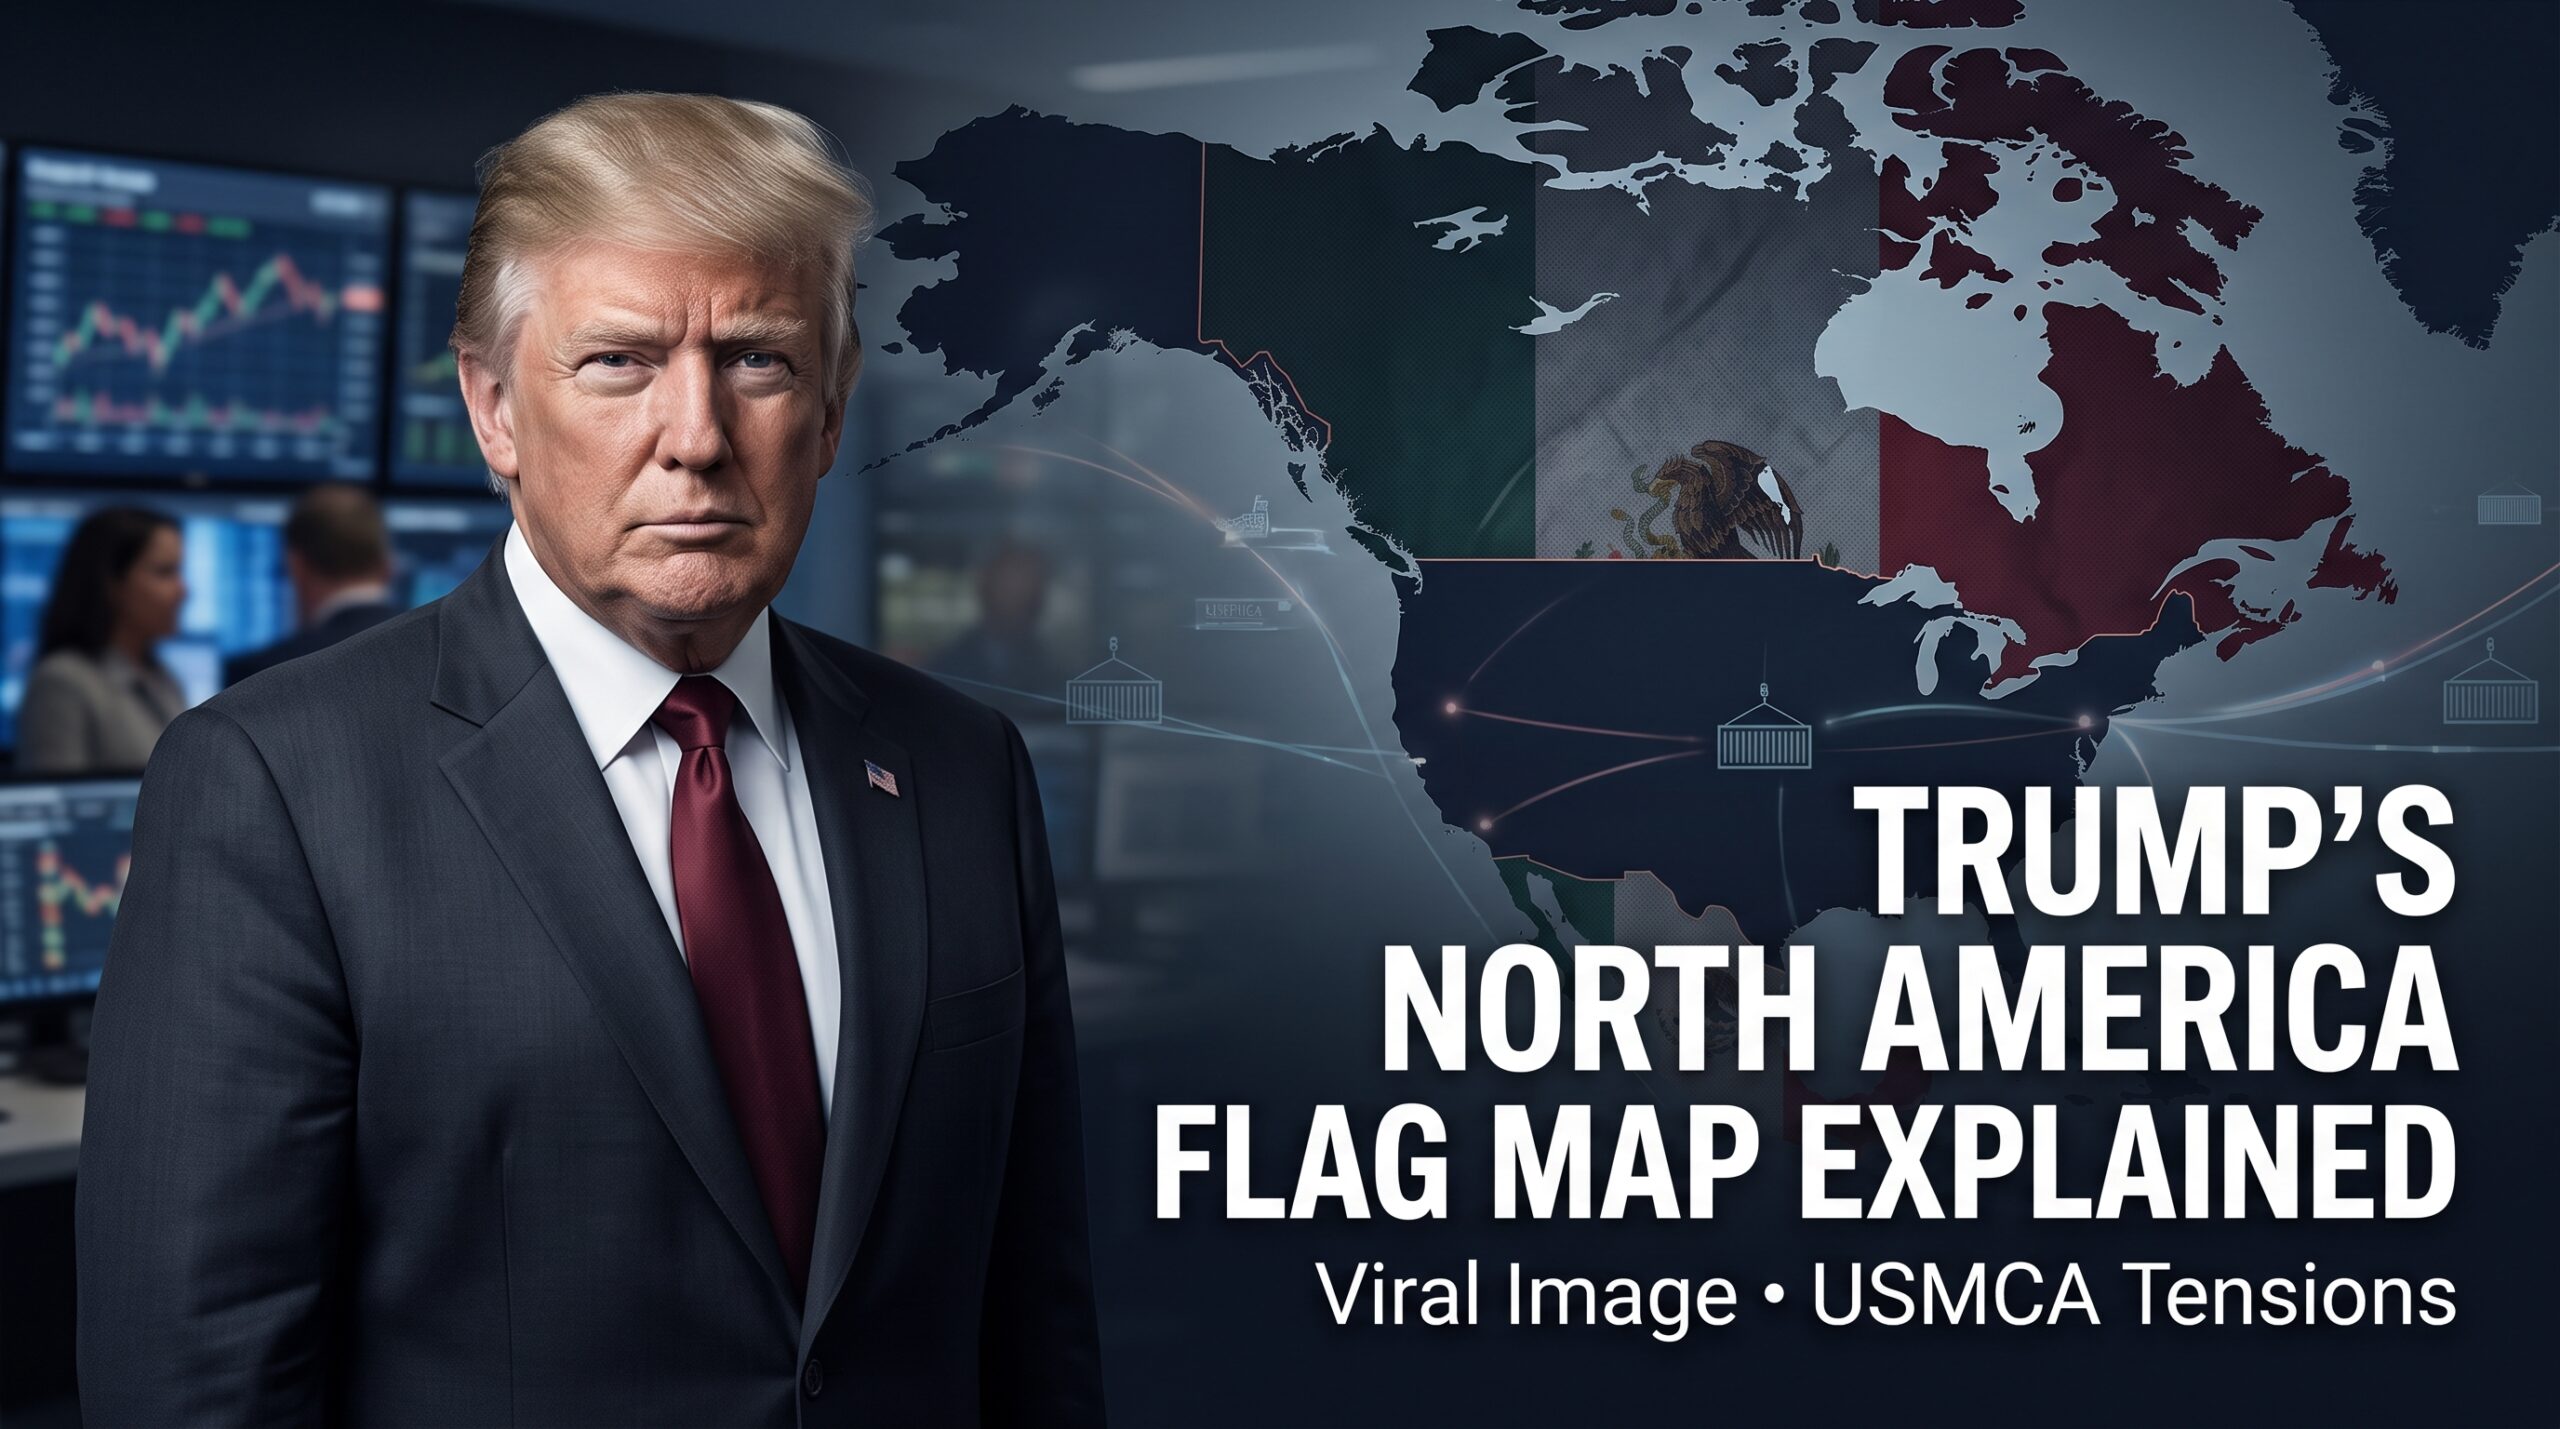
An AI-generated image posted to Truth Social this week has done more to reignite the debate over the future of North American trade and sovereignty than months of formal USMCA review hearings combined. The map — showing the American flag’s stars-and-stripes pattern superimposed over the entire United States, Canada, Mexico, Greenland, Iceland, and a string of Caribbean nations including Cuba and Jamaica — carried no caption, no policy explanation, and no White House clarification. It didn’t need one to go viral.
What the Map Actually Shows
The image, shared without comment, depicts:
- The continental United States, Canada, and Mexico entirely covered by a single American flag graphic.
- Greenland (an autonomous Danish territory) and Iceland (a sovereign European nation) included within the flag’s boundary — despite Iceland having no geographic connection to North America.
- Caribbean nations and territories, including Cuba, Jamaica, and Puerto Rico, folded into the same graphic.
- A flag design bearing 67 stars rather than the standard 50 — widely read online as a visual suggestion of 17 additional “states.”
- The caption “United States of America,” with no further text.
By standard geographic definition, North America comprises 23 sovereign nations. The map’s scope — extending to Iceland, which sits in Europe — signals the image was constructed as a symbolic statement rather than a literal territorial claim, though the White House has not offered that or any other characterization.
The Pattern This Fits
The map did not emerge from nowhere. It is the latest in a documented sequence of Trump statements and actions asserting expanded U.S. territorial interest across the same geography:
- Repeated public suggestions that Canada become the 51st U.S. state.
- Ongoing demands for U.S. control of Greenland, framed around national security, which Danish and Greenlandic officials have consistently rejected.
- An August 27, 2026 executive order directing U.S. federal agencies to refer to Lake Ontario as “Lake America” — a change that applies only to U.S. federal usage and carries no force under Canadian or international law.
- Earlier 2026 statements asserting U.S. control over the Strait of Hormuz, floated as “Trump Strait,” and a separate declaration regarding the Moon.
- A prior push to add New Mexico to the same renaming pattern, which state officials publicly rejected.
Commentators have characterized the map as consistent with — rather than a departure from — this established rhetorical pattern of using symbolic territorial claims and unilateral renaming actions as instruments of political signaling.
International Reaction
The map produced immediate diplomatic friction:
- Iceland summoned the U.S. ambassador in direct response to its inclusion in the graphic — a formal diplomatic protest step, despite Iceland’s inclusion appearing to be geographically nonsensical even within the map’s own logic.
- Foreign policy commentators have explicitly warned against dismissing the image as “empty noise,” arguing that when a sitting president overlays the American flag on the territory of Mexico, Canada, Iceland, Cuba, and Jamaica simultaneously, neighboring and allied governments are compelled to respond, since silence risks being read as tacit acceptance.
- Domestic reaction split sharply along predictable lines, with critics calling the post an “unhinged” territorial provocation and supporters characterizing it as satire or a negotiating gesture tied to ongoing trade friction.
The Real Economic Backdrop: USMCA’s Mandatory 2026 Review
The map’s viral spread is inseparable from a genuine, high-stakes trade process underway in parallel: the United States-Mexico-Canada Agreement (USMCA) is subject to a mandatory joint review in July 2026, and the process has been contentious well before the map surfaced.
Key developments in the USMCA review:
- U.S. Trade Representative Jamieson Greer has publicly accused Mexico of failing to comply with existing USMCA provisions, stating it “doesn’t make a lot of sense to talk about extending the USMCA or updating it when Mexico is not even complying with important parts of it.”
- Trump has floated abandoning the trilateral structure entirely in favor of separate bilateral deals with Mexico and Canada, arguing the current agreement’s terms explicitly allow for “different deals” with each partner.
- Mexico’s Economy Minister Marcelo Ebrard has acknowledged that the 2026 review will likely include distinct bilateral negotiating tracks, effectively conceding that the trilateral framework may not survive the review intact.
- Trump has separately ended trade negotiations with Canada at points during 2026, and floated 25% tariffs on Mexican and Canadian imports tied to fentanyl and migration flows — with both countries threatening retaliatory tariffs.
- The review is meant to address genuinely substantive issues — critical minerals access, EV supply chains, and AI-related trade provisions — that have been overshadowed in public discourse by the symbolic controversy of the flag map.
Reading the Signal: Negotiating Tactic or Genuine Ambition?
Trade and foreign-policy analysts are divided on how to interpret the map within the broader USMCA context:
- As leverage: A maximalist symbolic gesture ahead of contentious bilateral negotiations could be read as an opening position designed to make subsequent, more modest asks (tariff concessions, market-access changes) appear reasonable by comparison.
- As genuine signaling of territorial ambition: Given the map’s consistency with substantive prior actions — the Lake Ontario renaming executive order is a real federal policy change, not merely rhetoric — some analysts argue the pattern reflects an actual, if incrementally pursued, expansionist posture rather than pure negotiating theater.
- As a distraction mechanism: Some commentary, including from media figures, has framed the map and related renaming actions as attention-diverting moves timed against separate, less favorable news cycles (for instance, criticism tying the Lake Ontario order’s timing to concurrent coverage of Middle East policy).
The Trump North America flag map is simultaneously a viral internet moment and a genuine diplomatic incident, arriving in the middle of a substantively important USMCA review process where the trilateral trade agreement’s future is already in question. Whether read as negotiating leverage, distraction, or authentic signal of territorial ambition, the map has forced Iceland into formal diplomatic protest and added a symbolic layer of tension onto trade talks that were already fraught over tariffs, fentanyl enforcement, and Mexican compliance disputes — with the mandatory USMCA review outcome likely to matter far more to North American economic integration than the map itself.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
For six years, the USMCA functioned as a predictable backstop for North American supply chains — a rare constant through a volatile trade era. That predictability ended on July 1, 2026. The United States Trade Representative confirmed it would not agree to renew the USMCA in its current form following the agreement’s mandatory six-year joint review, and by September, the standoff had escalated sharply: new Section 338 tariffs on Canadian goods, a doubling of steel and aluminum duties, and stalled Canada-US talks, even as Mexico continued active, if difficult, bilateral negotiations. For supply chain executives, the question is no longer whether North American trade rules will change — it is how fast, and which sourcing models survive the transition.
Key Takeaways
- The USTR announced on July 1, 2026 that it would not renew the USMCA in its current form, following the agreement’s mandatory six-year joint review — though the agreement remains legally in force while negotiations continue, and full withdrawal by any party would take six months to take effect.
- New Section 338 tariffs on Canada-origin goods took effect August 19, 2026 at a 50% ad valorem duty, applying even where USMCA duty-free status would otherwise apply, following the collapse of a September round of Canada-US talks.
- An estimated 85% of Mexican exports to the US remain USMCA-compliant and exempt from newer tariff actions, including a Section 301 forced-labor enforcement action covering 60 economies — while Canada has not opened formal, text-based bilateral negotiations tied to the review at all.
- The central unresolved dispute with Mexico is automotive content requirements: Washington is seeking a 50% US-specific content threshold for vehicles to qualify for preferential USMCA access, which Mexico is resisting and has linked to relief from existing Section 232 tariffs on autos (25%) and steel/aluminum (50%).
- Despite the tariff escalation, nearly 60% of goods imported from Canada and Mexico continue to enter the US duty-free, underscoring that North American trade disruption in 2026 remains targeted and negotiated rather than a wholesale breakdown of integration.
How the Standoff Reached This Point
The current confrontation traces back through a specific legal and political sequence. After the US Supreme Court struck down IEEPA-based tariffs in February 2026, the administration pivoted to alternative legal authorities: a 10% tariff on Canada and Mexico under Section 122 of the Trade Act of 1974 (with an exemption maintained for USMCA-compliant goods), alongside a separate, unaffected 25% tariff on Canadian and Mexican steel, aluminum, and certain auto products under Section 232 of the Trade Expansion Act of 1962 — subsequently raised to 50% for steel and aluminum.
The USMCA’s mandatory six-year joint review, triggered by a provision written into the original 2020 agreement, then became the vehicle for a more fundamental renegotiation push. On July 1, 2026, the USTR confirmed it would not renew the agreement in its current form, citing purported shortcomings and ongoing trade deficits with both neighbors. Crucially, this announcement did not terminate the agreement or preferential trade — the USMCA remains in force while the three governments work through the issues raised, and any formal withdrawal by a party would not take effect for six months, a design feature intended to preserve negotiation leverage without triggering an immediate supply chain shock.
The situation escalated further by September: the US deployed the rarely used Section 338 tariff authority against Canada specifically, roughly doubling existing steel and aluminum rates and reintroducing tariffs from a zero baseline across a much wider set of Canadian goods, after a round of talks collapsed. Canada, notably, has not yet opened a substantive, text-based bilateral negotiating round tied to the joint review itself, unlike Mexico — engagement has remained largely at the ministerial-call level between Canada’s Trade Minister and the US Trade Representative.
The Two-Track Negotiation: Mexico vs. Canada
A critical, underappreciated fact for 2026 supply chain planning is that the US is running genuinely different negotiating tracks with its two USMCA partners:
Mexico has completed two full bilateral negotiating rounds covering automotive rules of origin, steel and aluminum, economic security, industrial goods, agriculture, labor, environmental standards, and regulatory compatibility. The core sticking point remains automotive content: Washington’s push for a 50% US-specific content requirement (versus the current North American-content framework) is being actively resisted by Mexico, which has explicitly linked any concessions to relief from existing Section 232 auto and metals tariffs. Mexican officials have noted that a separate Section 301 forced-labor enforcement action covering 60 economies produces no practical change for Mexican exporters specifically, since USMCA-compliant goods — an estimated 85% of Mexico’s US-bound exports — remain exempt as long as rules-of-origin requirements are satisfied.
Canada, by contrast, has not begun formal bilateral negotiations tied to the review at all, and its position has deteriorated sharply since July 1: the September Section 338 action roughly doubled steel and aluminum rates and reintroduced tariffs across a substantially broader set of goods from a zero baseline, representing the most significant escalation in the relationship since the review began.
What This Means for Supply Chain Restructuring
Rules of Origin Are Now a Live Compliance Risk, Not a Static Baseline
With automotive content requirements under active renegotiation and other sectors facing scrutiny, businesses that have treated USMCA rules-of-origin qualification as a fixed, one-time certification exercise face material risk. A targeted change to a single rule of origin, tariff classification, or certification requirement can affect thousands of suppliers and shipments across an integrated production network simultaneously — meaning sourcing and logistics models that currently qualify for preferential treatment may not continue to qualify under a revised framework, even without any change to the physical supply chain itself.
Mexico Remains the More Stable Near-Term Sourcing Base
Given Mexico’s active, structured bilateral negotiation track and the 85% USMCA-compliance exemption rate for its exports, Mexico currently presents a comparatively more predictable near-term sourcing environment than Canada, where the absence of formal negotiations combined with the September escalation has introduced acute uncertainty. This is a reversal of the historical assumption that Canada — as the more institutionally aligned partner — represents lower trade-policy risk.
Automotive and Metals-Intensive Supply Chains Face the Sharpest Exposure
The unresolved automotive content dispute with Mexico and the doubled steel/aluminum tariffs on Canada concentrate risk specifically in vehicle manufacturing, auto parts, and any metals-intensive industrial supply chain — sectors where BCG’s analysis has noted that tariff costs, layered onto supply disruption, could threaten the survival of some auto and auto parts companies, with downstream effects on retail prices, annual vehicle sales, and industry employment.
The Duty-Free Baseline Still Holds — For Now
The single most important stabilizing fact for supply chain planning is that nearly 60% of goods imported from Canada and Mexico continue to enter the US duty-free despite the standoff, and full treaty withdrawal by any party remains widely viewed as unlikely given the depth of North American supply chain integration and the six-month withdrawal notice period built into the agreement’s design. This suggests businesses should plan for continued negotiation-driven volatility in specific sectors (autos, steel, aluminum) rather than a wholesale collapse of North American trade preference.
Supply Chain Restructuring Strategies for 2026–2027
- Segment supplier risk by rules-of-origin sensitivity, not just by country. A supplier whose qualification depends on automotive content thresholds under active renegotiation carries fundamentally different risk than one in a sector untouched by the current disputes.
- Build contractual flexibility into sourcing agreements for tariff-classification changes. Given that thousands of suppliers can be affected by a single rule change, procurement contracts should include tariff-exposure adjustment mechanisms rather than assuming static classification.
- Treat Canada-sourced steel, aluminum, and metals-intensive inputs as higher near-term risk than comparable Mexican inputs, given the divergent negotiation tracks and the September escalation specifically targeting Canadian goods.
- Monitor the Section 232 auto tariff–content requirement linkage closely. Mexico’s explicit linking of content-rule concessions to Section 232 relief means any resolution is likely to arrive as a package, not sector by sector — businesses should model scenarios for both continued impasse and a bundled resolution.
- Avoid over-reacting to headline tariff announcements without checking USMCA-compliance exemption status. With roughly 85% of Mexican exports and 60% of combined Canada-Mexico imports still qualifying for duty-free treatment, the practical tariff exposure for a specific supply chain often differs substantially from the headline rate.
Frequently Asked Questions
Is the USMCA ending in 2026?
No. The USTR declined to renew the USMCA in its current form as of July 1, 2026, but the agreement remains legally in force while negotiations continue; a formal withdrawal by any party would take six months to take effect and is considered unlikely given deep supply chain integration.
How are US tariffs on Canada different from tariffs on Mexico in 2026?
Canada faces a more severe and less negotiated situation: new Section 338 tariffs took effect in August 2026 at 50% on certain goods, talks collapsed in September, and Canada has not opened formal bilateral negotiations. Mexico has completed two full bilateral negotiating rounds, and roughly 85% of its US-bound exports remain USMCA-compliant and tariff-exempt.
What is the main unresolved issue in the USMCA renegotiation with Mexico?
Automotive content requirements — the US is seeking a 50% US-specific content threshold for vehicles to qualify for preferential access, which Mexico is resisting and has linked to relief from existing steel, aluminum, and auto tariffs.
Conclusion
The 2026 North American tariff standoff is best understood not as a collapse of continental trade integration but as a genuine, high-stakes renegotiation running on two very different tracks — a structured, if difficult, Mexico process and a stalled, escalating Canada process. With nearly 60% of Canada-Mexico imports still entering the US duty-free and full treaty withdrawal remaining a low-probability outcome, the practical task for supply chain leaders is precision: distinguishing which specific inputs, sectors, and supplier relationships carry genuine renegotiation risk from the broader base of trade that remains, for now, stable.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.
With the November 3, 2026 midterm elections roughly two months away, multiple independent forecasting models are converging on a similar conclusion: Democrats are currently favored to retake control of the U.S. House of Representatives, though the size of any majority — and control of the Senate — remains genuinely uncertain.
This piece breaks down what the leading models actually say, why historical patterns favor the out-of-power party in midterms, and which structural factors could still complicate a Democratic pickup.
The Current Numbers
Heading into the cycle, Republicans hold a narrow 218-seat majority, with Democrats at 212 seats and several vacancies. Because of that narrow margin, Democrats need to flip only a small net number of seats — commonly cited as roughly three to six, depending on how upcoming special elections in safely Democratic vacant seats resolve — to reclaim the majority.
Several independent models have published 2026 House projections:
- A Cornell University-based academic forecasting team, presenting at the American Political Science Association’s annual meeting, projects Democrats winning approximately 226 seats to Republicans’ 209, with simulations showing a plausible range as wide as 206 to 258 Democratic seats.
- A separate independent forecasting outlet (FiftyPlusOne) gives Democrats an 85% probability of winning the House majority, with a median projected outcome of 230 seats, and a national House popular-vote margin estimated at roughly +7 points for Democrats.
- Aggregator and prediction-market platforms tracking the race show a broadly consistent picture: Democrats favored, with meaningful — not negligible — uncertainty remaining.
Researchers behind the Cornell model were notably direct about what it would take for the forecast to be wrong: given the model’s historical accuracy, a Republican House majority holding would likely mean “either everything has gone their way or something unprecedented has happened.”
Why History Favors Democrats Structurally
Election forecasters lean heavily on one of the most consistent patterns in American politics: the president’s party almost always loses House seats in midterm elections.
- Looking back across 36 midterm elections since 1882, the White House party avoided losing a net of at least three seats in only four of them — 1934, 1962, 1998, and 2002 — each occurring under unusual circumstances (the Great Depression recovery, the Cuban Missile Crisis aftermath, post-9/11 unity, and the Clinton impeachment backlash, respectively).
- Democrats need a uniform national swing of roughly 1.1% from the 2024 House results to flip control — a relatively low bar by historical standards.
- Special elections held throughout 2025 provide an early, concrete signal: across roughly 31 state legislative and House special elections, Democratic candidates outperformed the 2024 presidential ticket’s vote share by an average of 15.4 points (median 13 points) — more than ten times the swing needed to flip the House.
The Redistricting Wildcard
No 2026 forecast is complete without accounting for the unusual mid-decade redistricting activity that has reshaped the House map since the 2024 election. Aggressive redistricting in several Republican-controlled states has given the GOP additional structural insulation heading into this cycle — a countervailing force against the historical midterm pattern and the favorable special-election trendline described above. This is the central tension every current model is trying to price in: strong Democratic generic political environment signals, against a map that has been deliberately reshaped to blunt exactly that kind of environment.
The GOP Counter-Strategy
Republican strategists are not treating the historical pattern as inevitable. Key elements of the party’s defensive posture include:
- Leaning on redistricting gains in states where new maps have already been implemented, effectively “banking” seats that would otherwise be more competitive under prior district lines.
- Fundraising and turnout operations targeted specifically at the small number of genuinely competitive districts where the national environment is expected to matter most.
- Nationalizing the midterm around specific policy contrasts rather than running on incumbency alone, given that broad “stay the course” messaging tends to perform poorly for an incumbent president’s party in a midterm.
What Swing Districts Are Actually Deciding This
Rather than the national popular vote, the real decision point sits in a relatively small number of competitive districts — often those that saw redistricting changes, those with retiring incumbents, or historically split-ticket suburban seats. Readers tracking this race closely should watch:
- Districts with open seats created by incumbent retirements, which historically see larger swings than seats with incumbents running for reelection.
- Suburban districts that have trended away from the GOP in recent cycles, where the current generic-ballot environment would need to hold through November to matter.
- Newly redrawn districts in states where redistricting fights are still working through courts — some maps used in 2026 could still face late legal challenges.
What Competitors Are Missing
Much of the horserace coverage of this cycle reports the topline “Democrats favored” number without explaining why two structurally different forces — a strongly Democratic-leaning political environment on one hand, and an aggressively re-drawn map on the other — are pulling against each other simultaneously. That tension, not the headline probability number, is the actual story of the 2026 House cycle, and it’s why even a “85% favored” forecast still carries real uncertainty worth taking seriously rather than treating as a foregone conclusion.
Key Dates to Watch
- Ongoing — ballot access deadlines and any late redistricting litigation in contested states
- September–October 2026 — final pre-election generic ballot and fundraising disclosures
- November 3, 2026 — Election Day
- Early November 2026 — initial results; close districts may take days to certify
Q: Are Democrats favored to win the House in the 2026 midterms?
As of early September 2026, multiple independent forecasting models favor Democrats to win a U.S. House majority. One academic model projects roughly 226 Democratic seats to 209 Republican seats; another independent forecaster puts Democrats’ probability of winning the House at 85%, with a median projection of 230 seats. Republicans currently hold an 218-seat majority, and Democrats need only a small net seat gain to flip control.
Discover more from The Monitor
Subscribe to get the latest posts sent to your email.

Trump’s North America Flag Map Explained: Viral Image, USMCA Tensions

2026 Midterms: How Democrats Are Competing in Deep-Red Senate Seats

North American Tariff Standoff 2026: Supply Chain Guide

2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover

Analyzing Anthropic’s $15 Billion Credit Facility: What It Means for Stock Health

Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown

Johnny Ray and Nicole Mississippi: Attala County Case Explained

Clarence Thomas Unfiltered: The Ted Cruz Interview on Ethics and Identity

Fond du Lac Stalking Case: Serial-Killer Memorabilia, Skulls & the Criminal Complaint
Johnny Ray and Nicole Mississippi: Attala County Case Explained

Best Fitness Apps and Wearables That Connect to Health Insurance in 2026
2026 Midterm Election Forecast: The Data Behind the Projected Democratic House Takeover
Eileen Gu’s Mindset Framework & $50M Brand: Full Breakdown

RFK Jr. Confirmation Investigation 2026: Health Policy Fallout Explained
Fond du Lac Stalking Case: Serial-Killer Memorabilia, Skulls & the Criminal Complaint

CRM Stock, Workday, Cisco: What Earnings Signal Now
Clarence Thomas Unfiltered: The Ted Cruz Interview on Ethics and Identity

Shanghai Ravioli Chicken Recall 2026: Full Product List & Refund Guide
-

 Featured5 years ago
The Right-Wing Politics in United States & The Capitol Hill Mayhem
-

 News5 years ago
Prioritizing health & education most effective way to improve socio-economic status: President
-

 China5 years ago
Coronavirus Pandemic and Global Response
-

 Canada5 years ago
Socio-Economic Implications of Canadian Border Closure With U.S
-

 Democracy5 years ago
Missing You! SPSC
-

 Conflict5 years ago
Kashmir Lockdown, UNGA & Thereafter
-
Democracy5 years ago
President Dr Arif Alvi Confers Civil Awards on Independence Day
-

 Digital6 years ago
Pakistan Moves Closer to Train One Million Youth with Digital Skills